洞察
新闻稿2026年4月6日1 分钟阅读

Potential of Sihanoukville Autonomous Port and Site Visit

Potential of Sihanoukville Autonomous Port and Site Visit

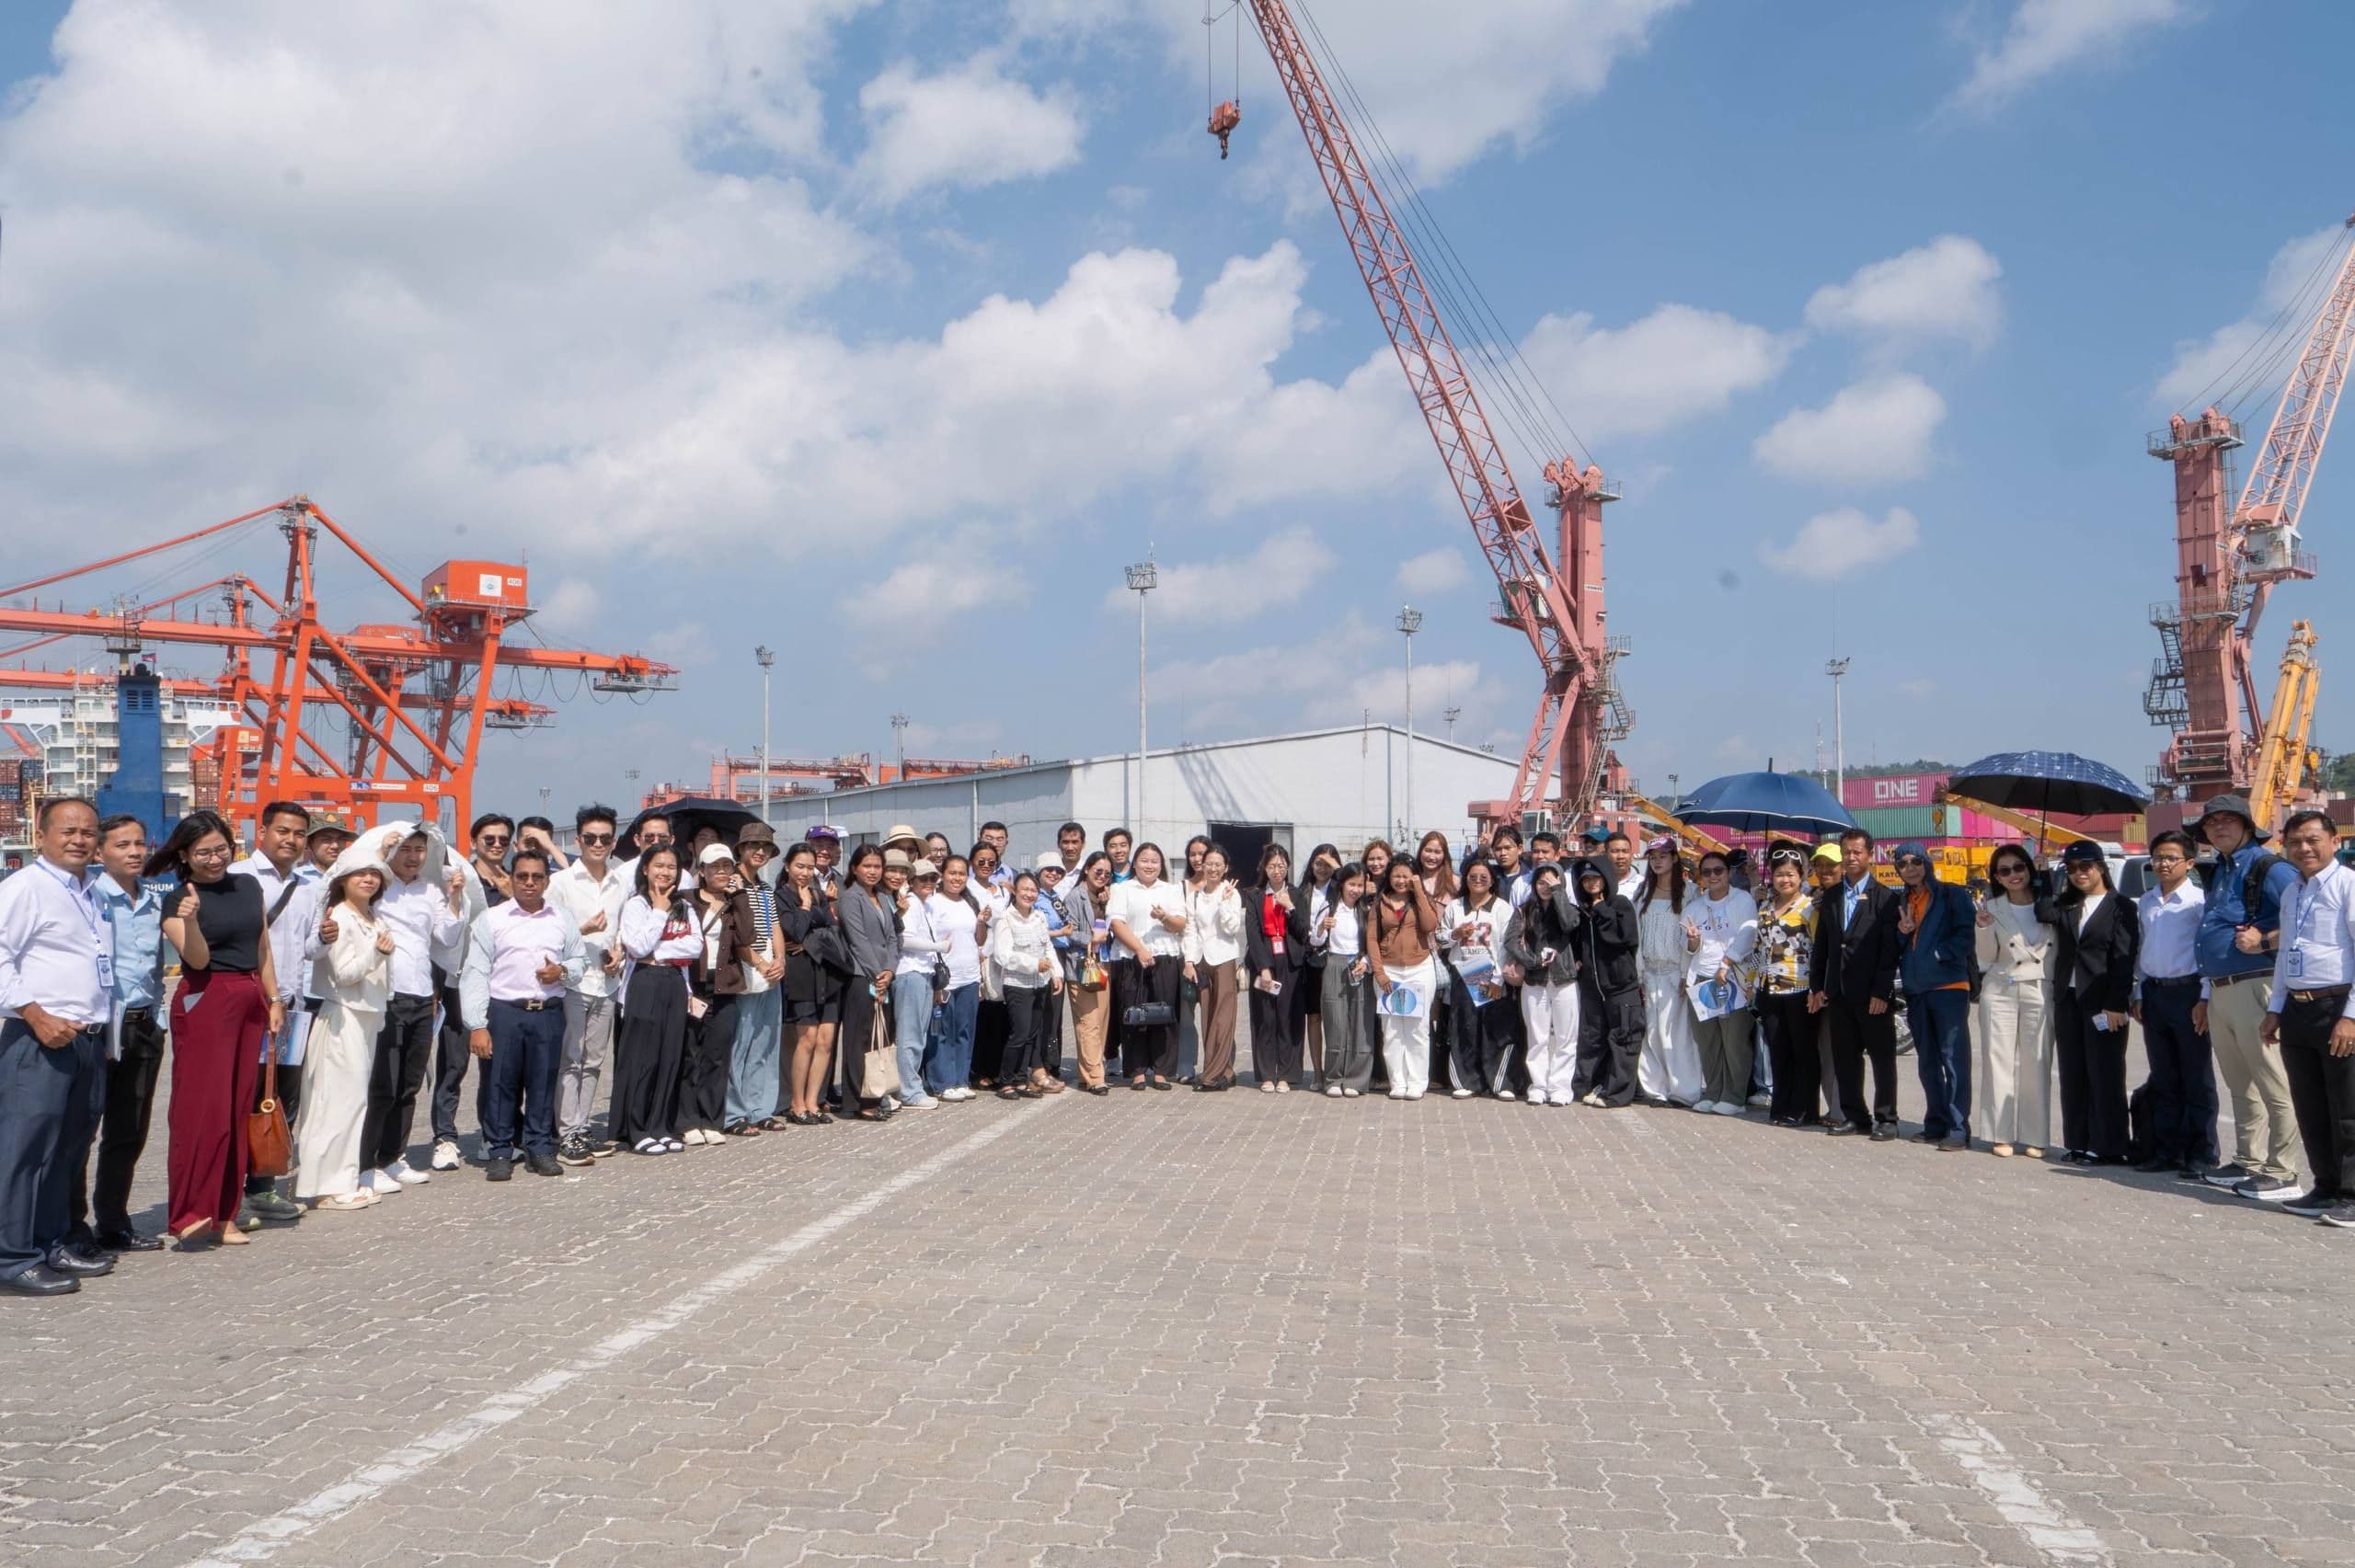
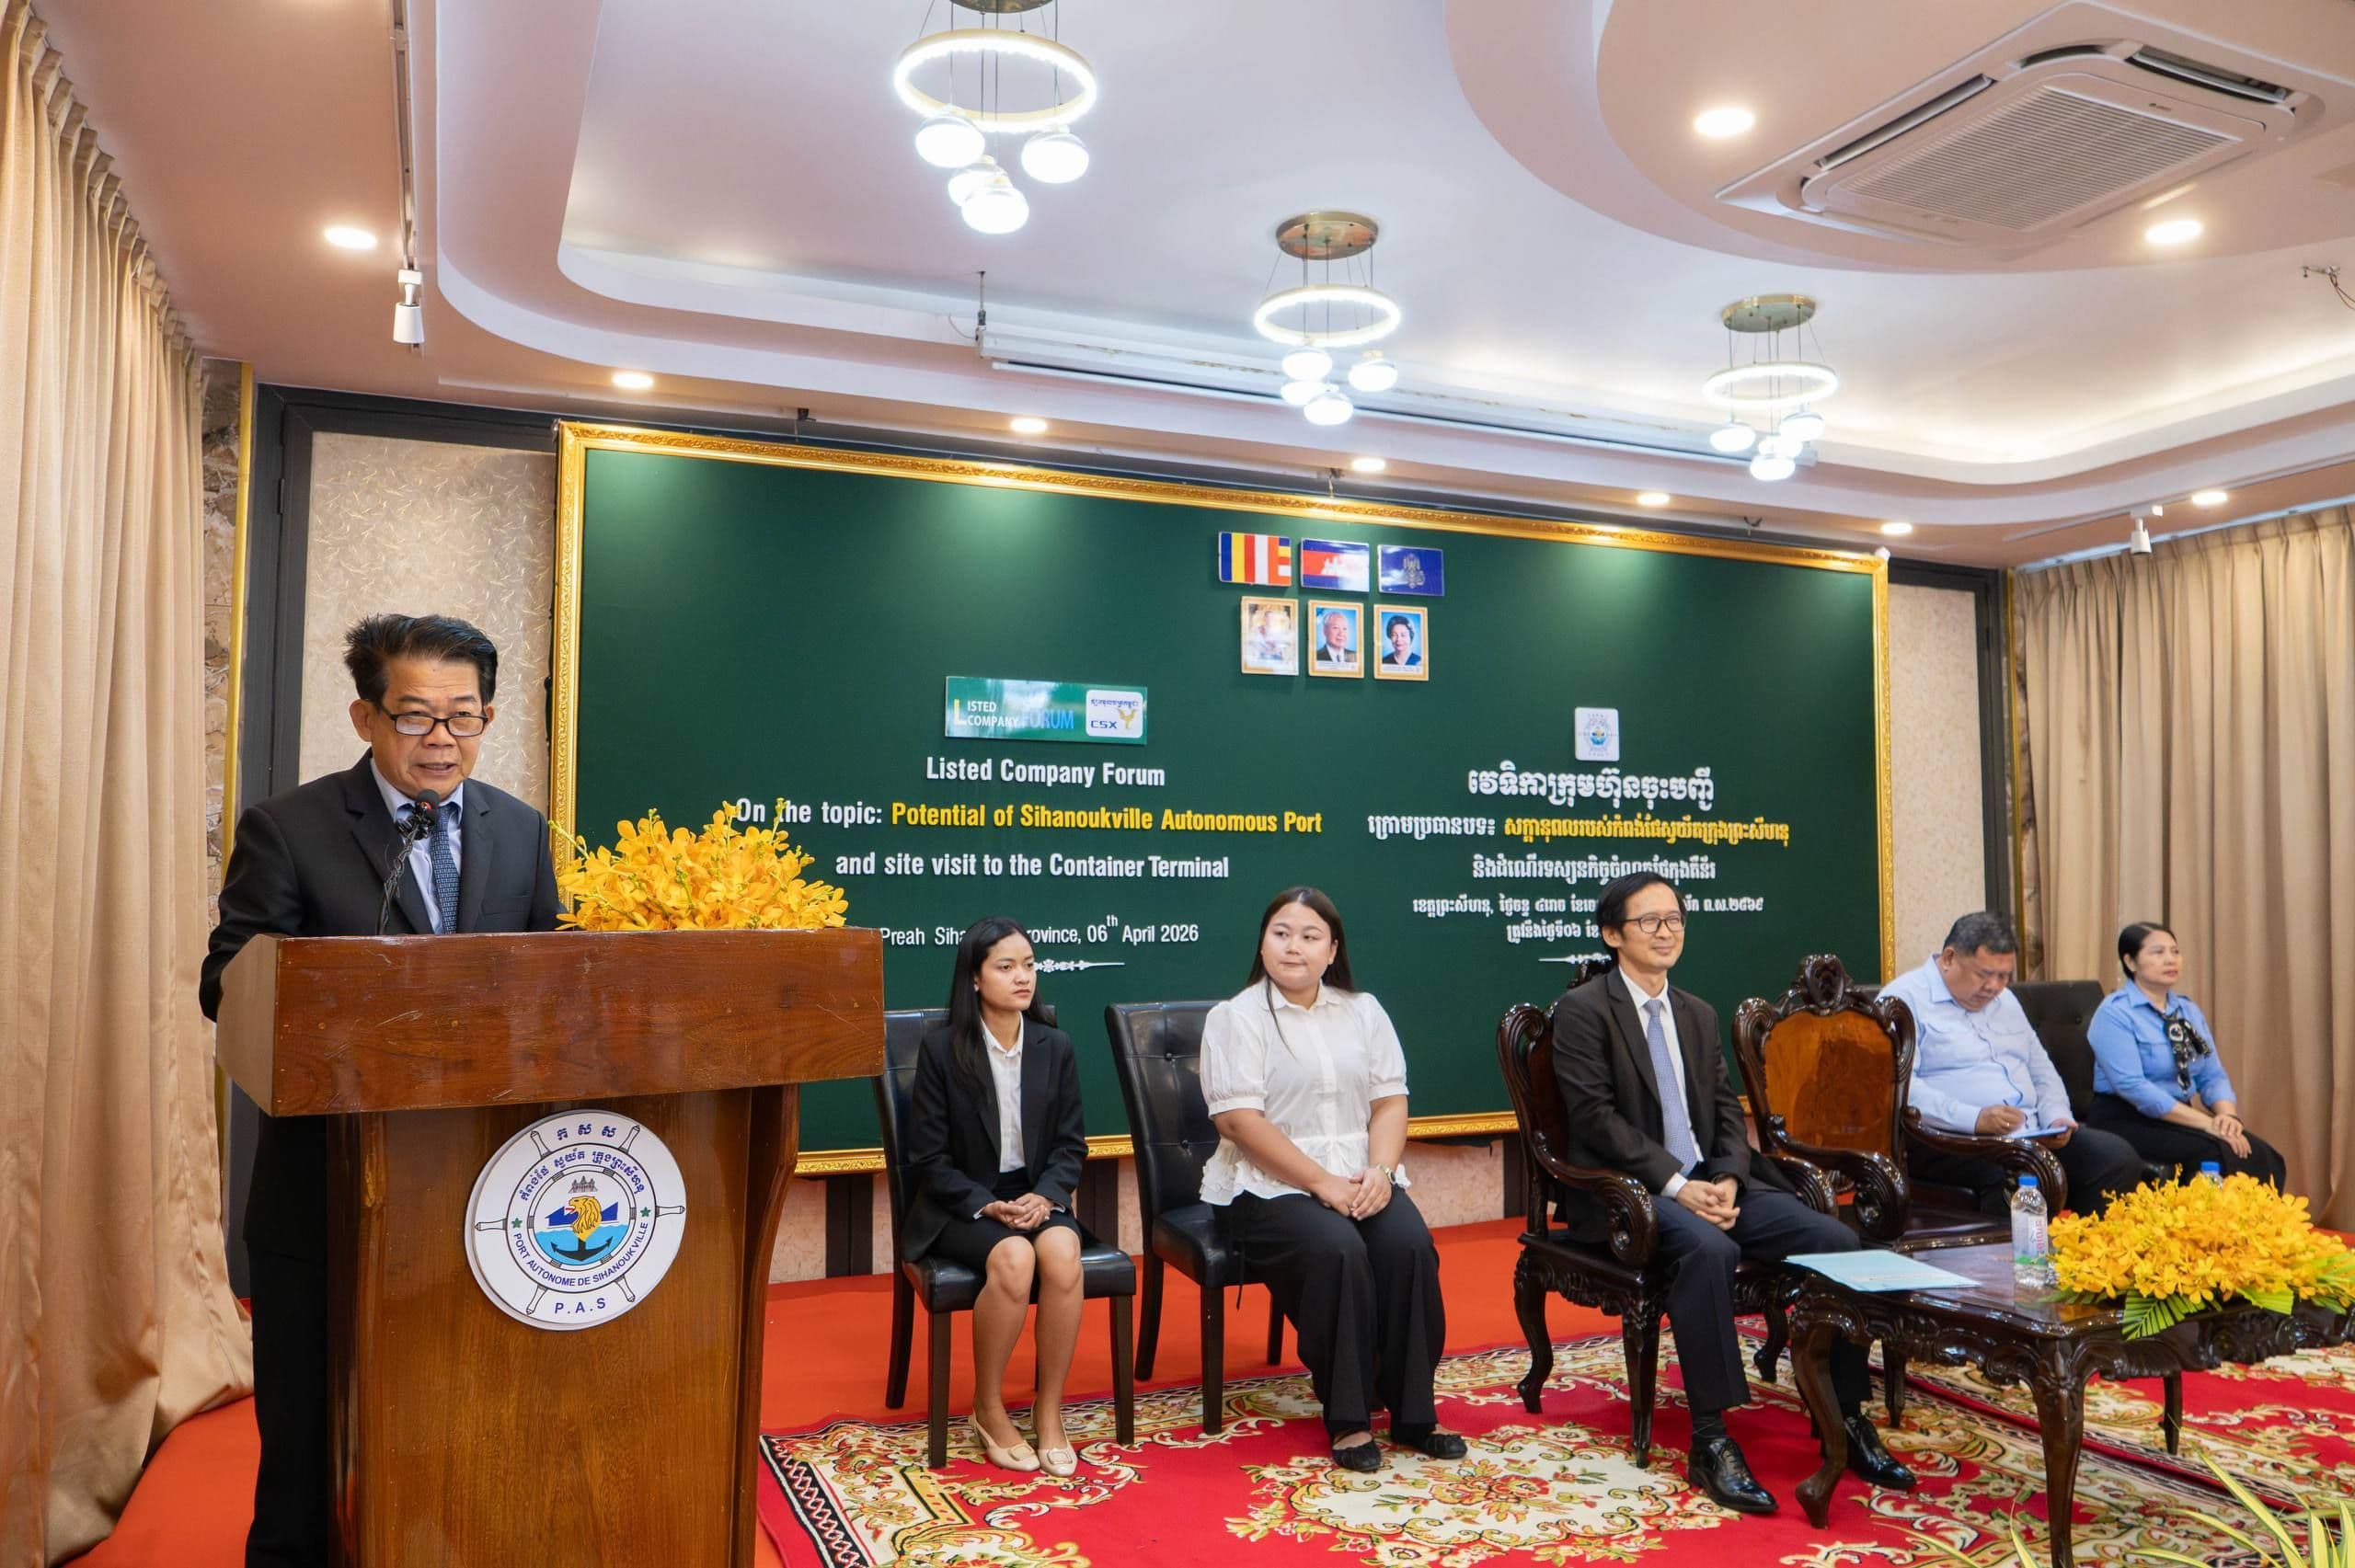
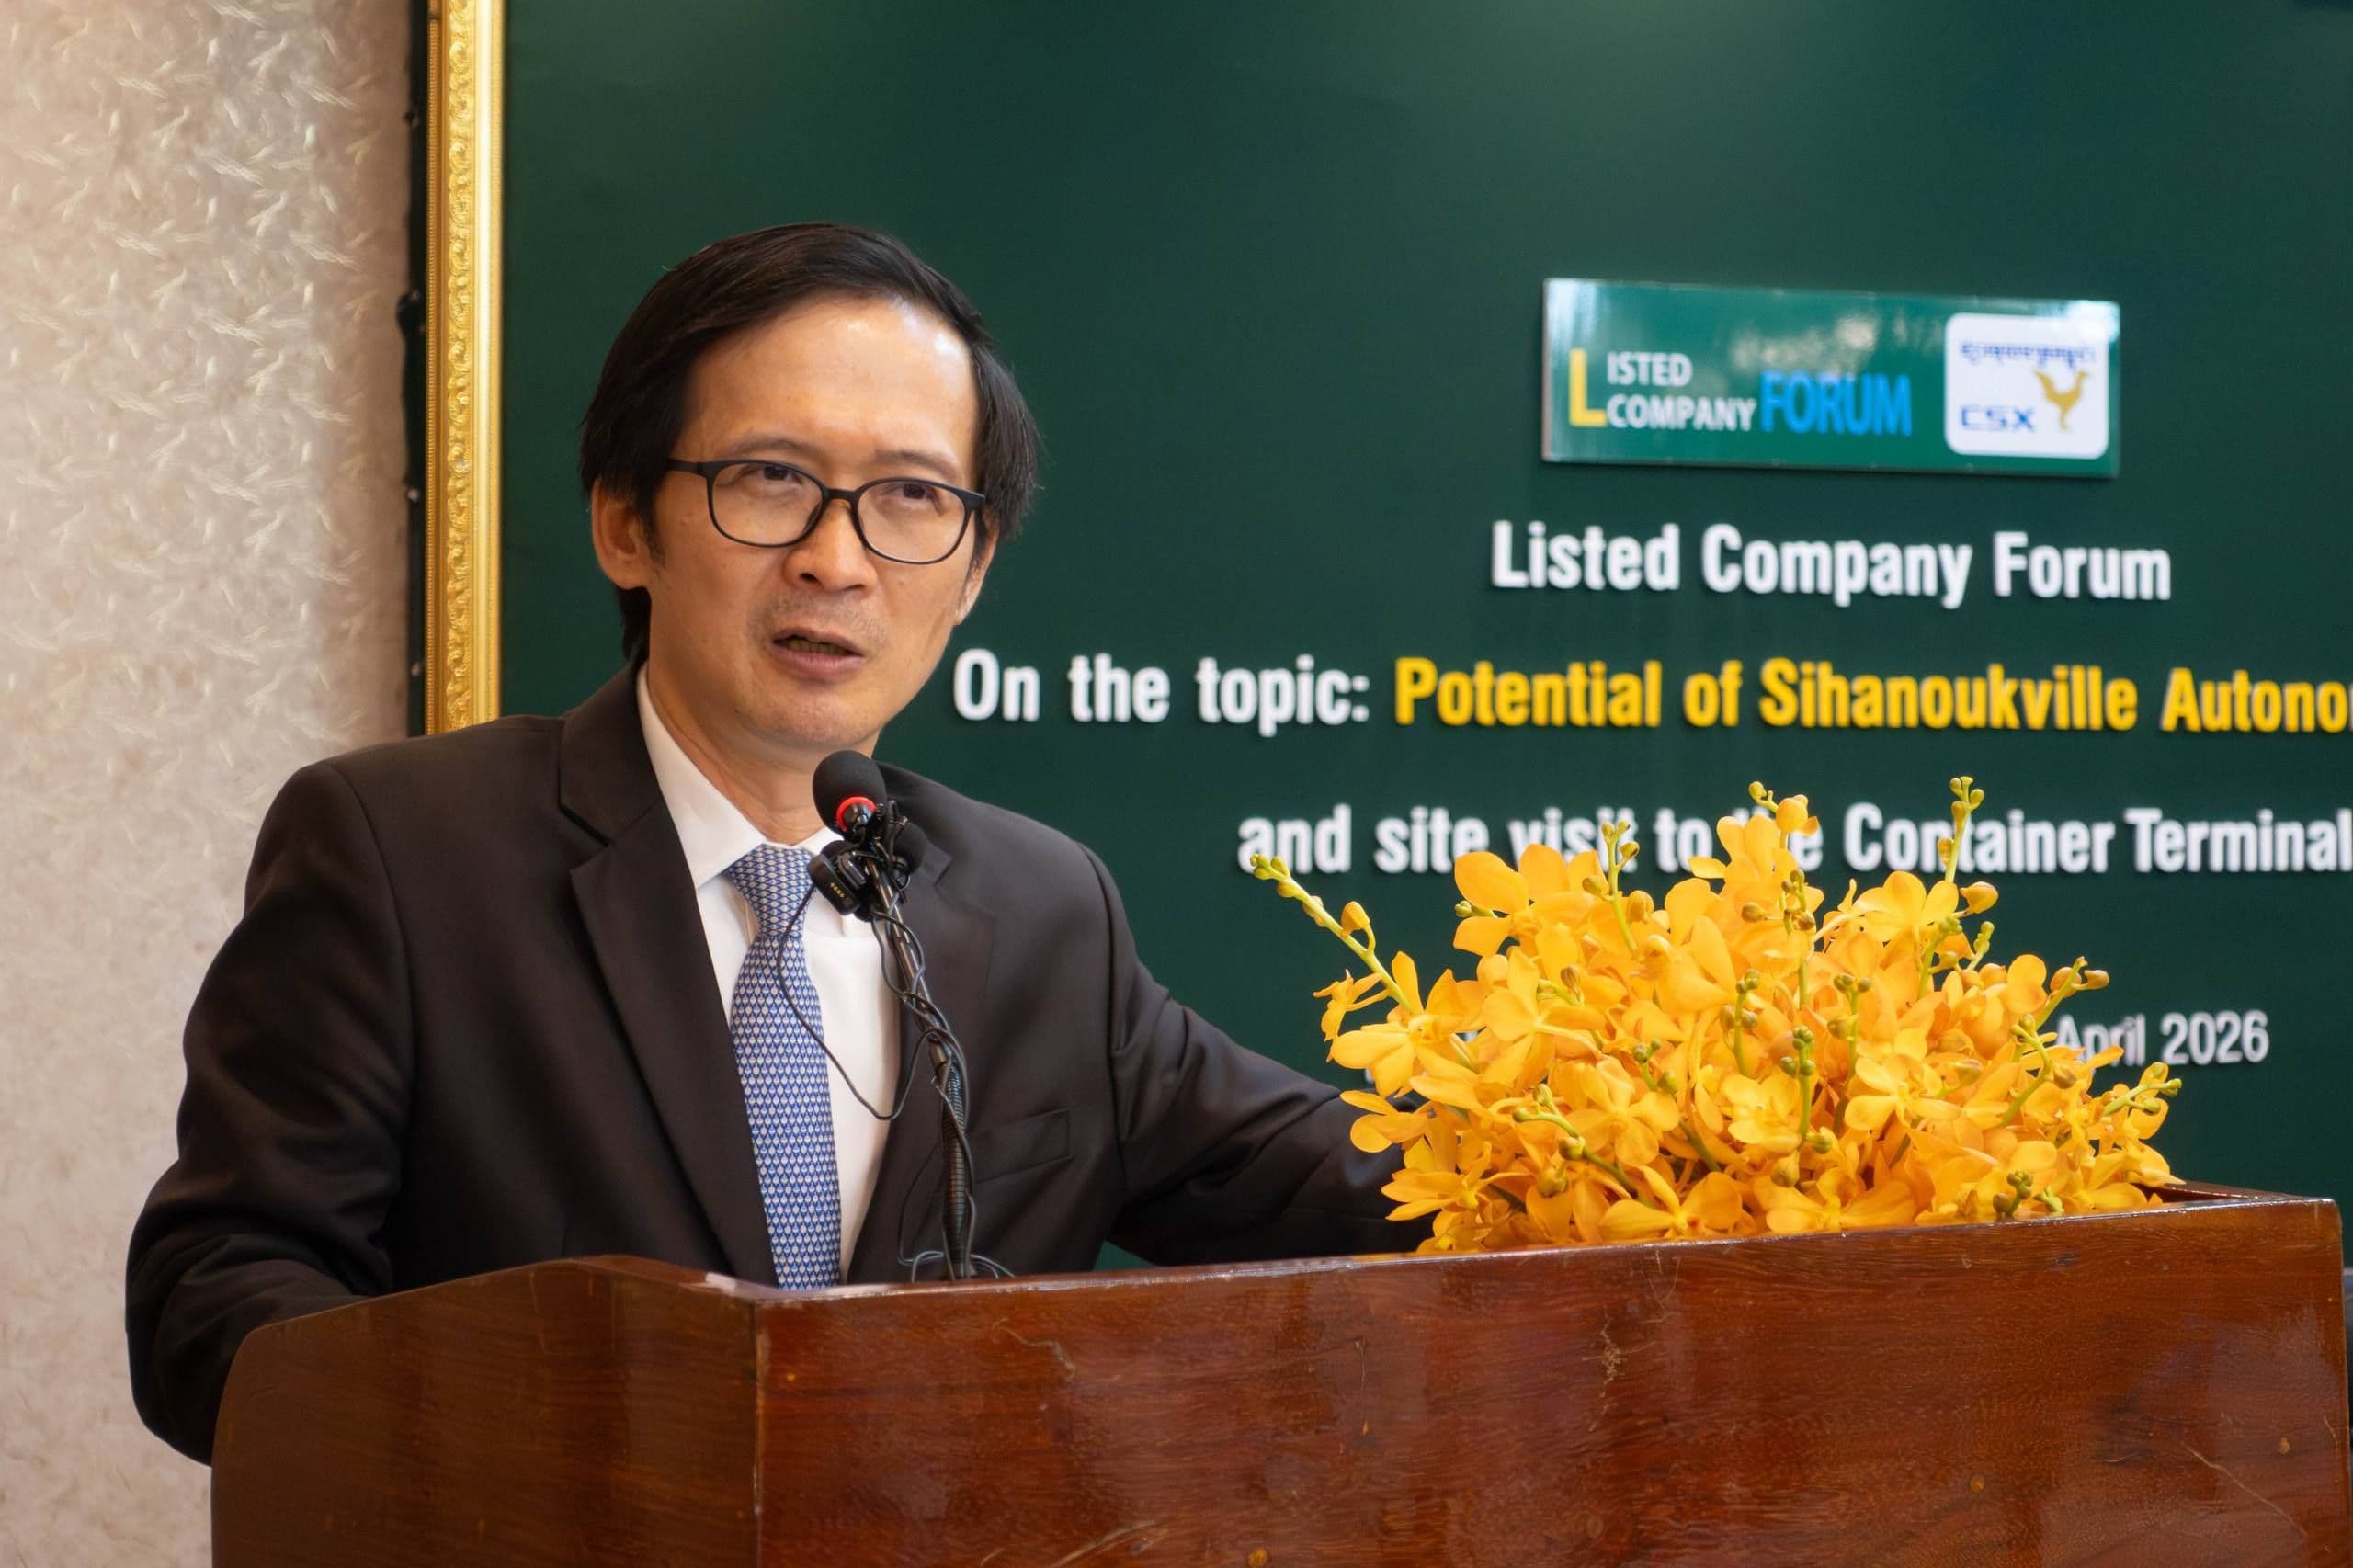
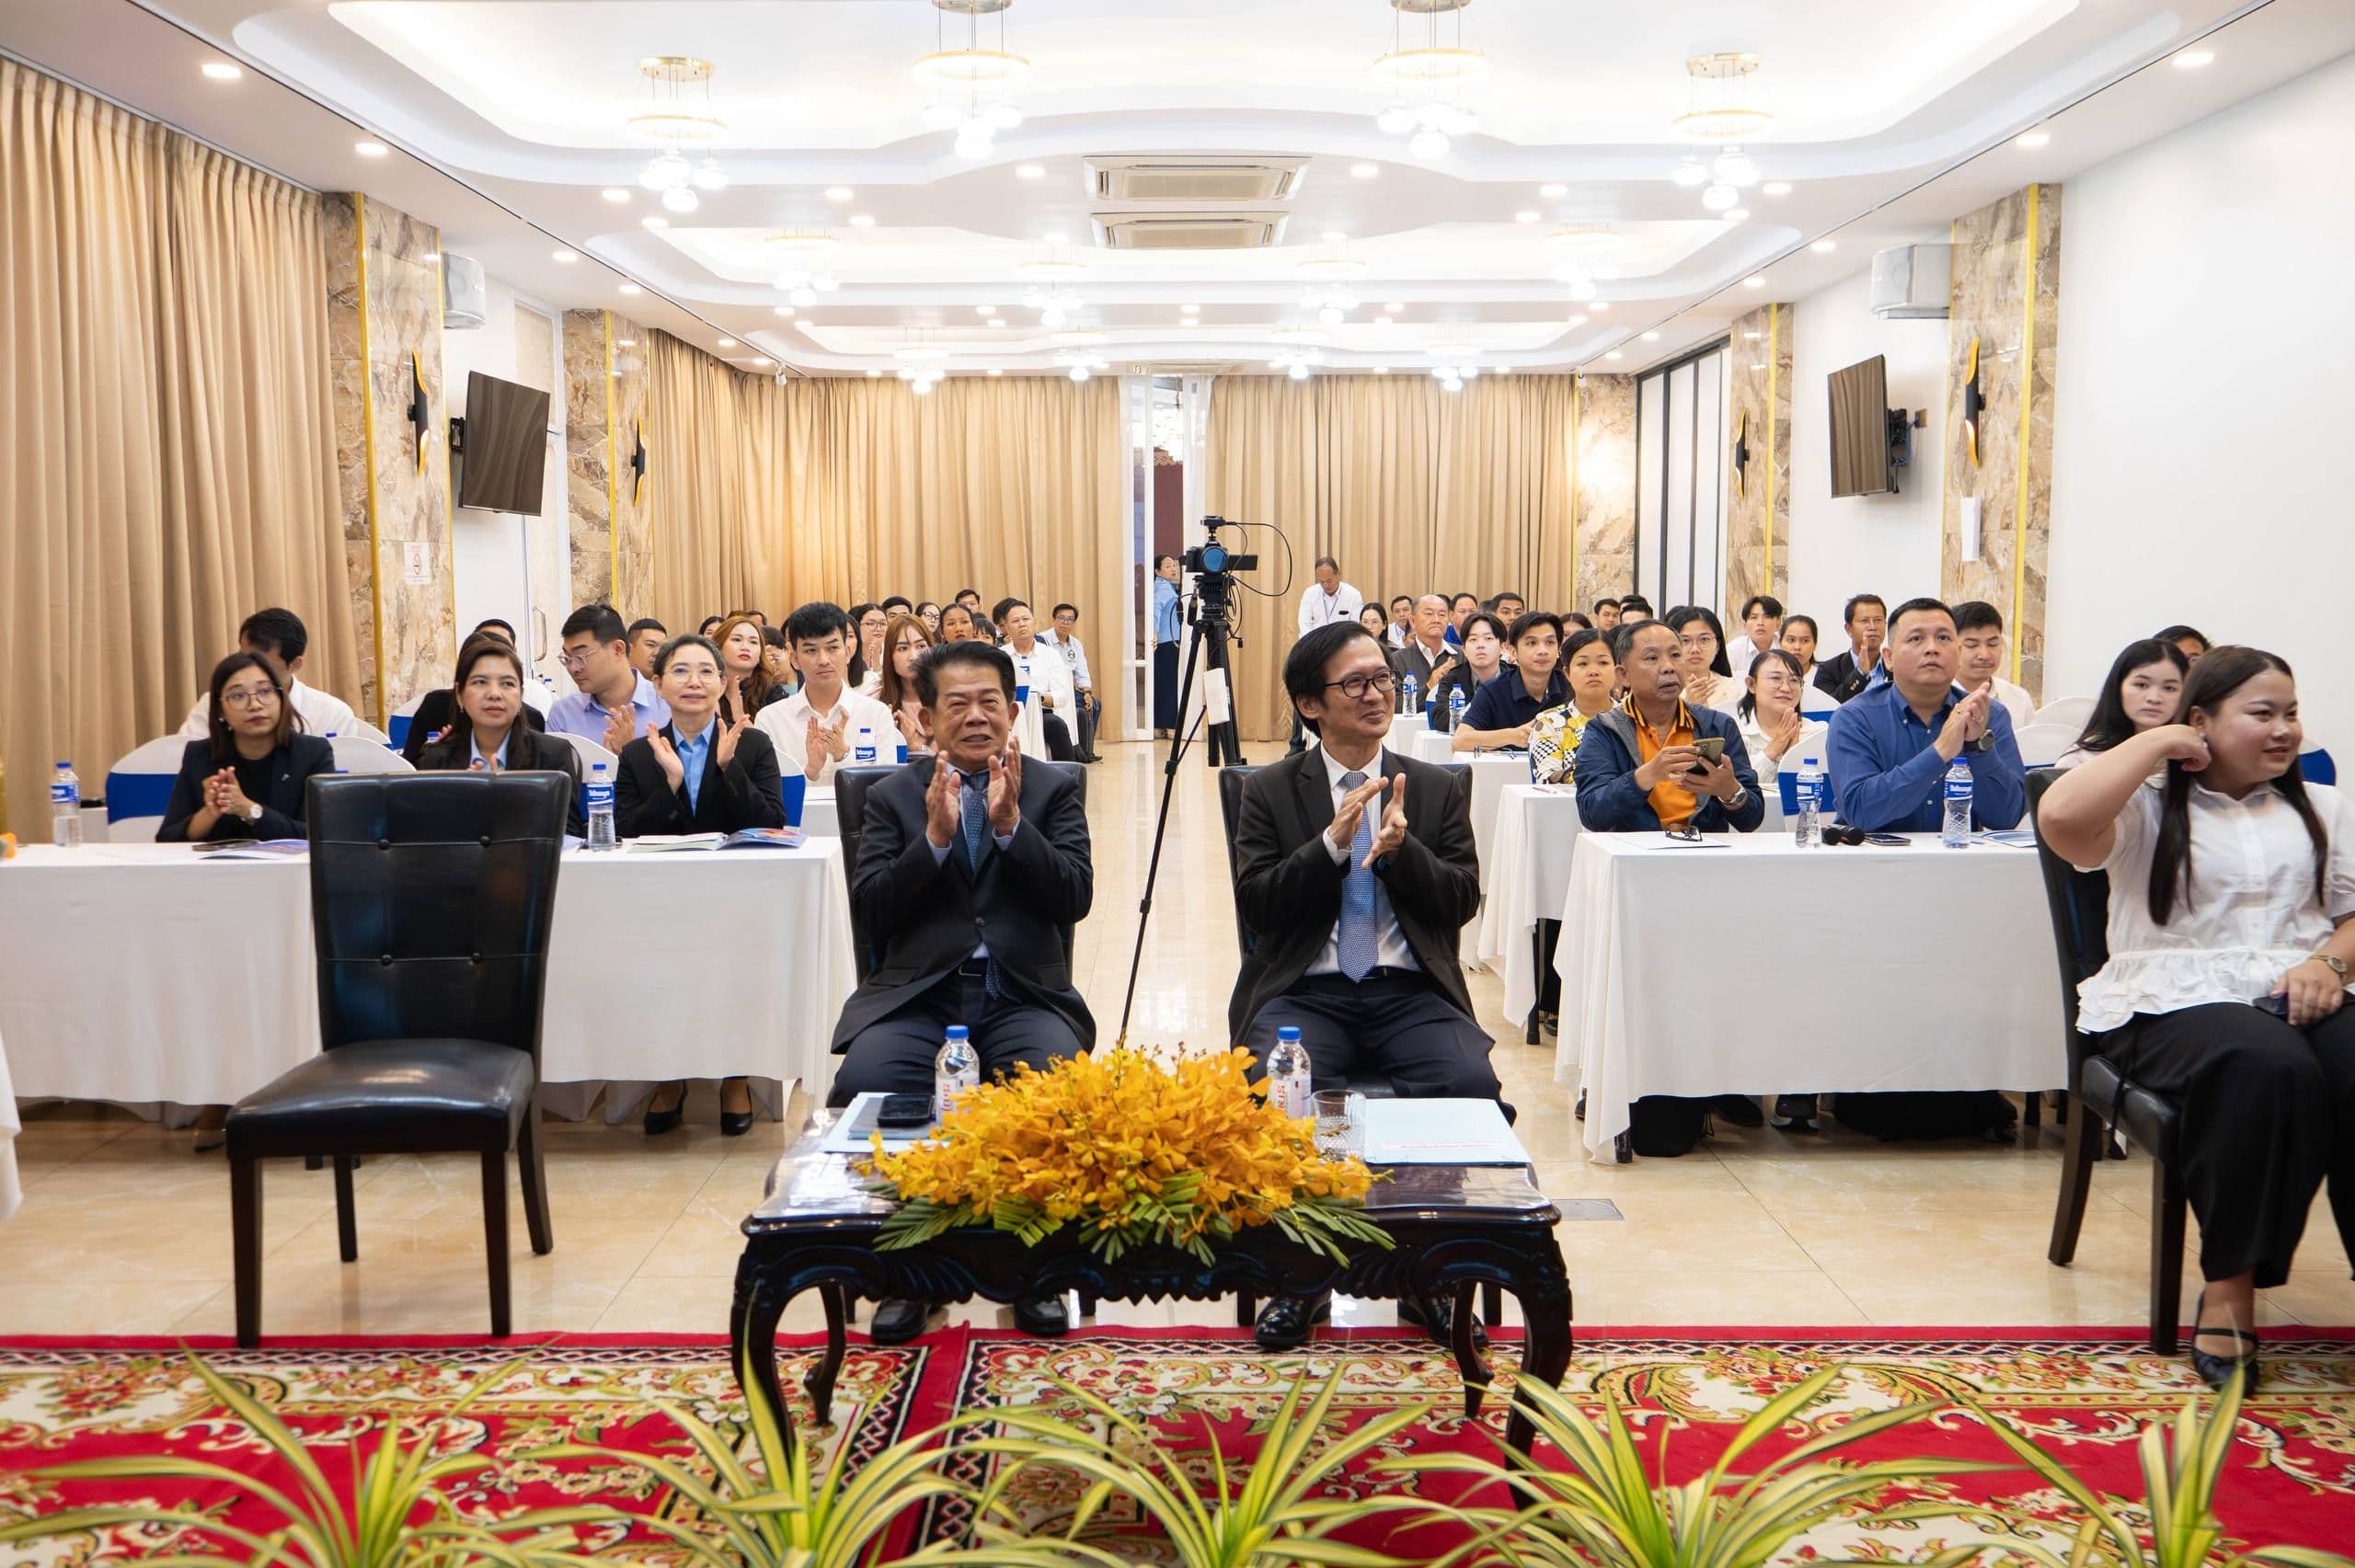
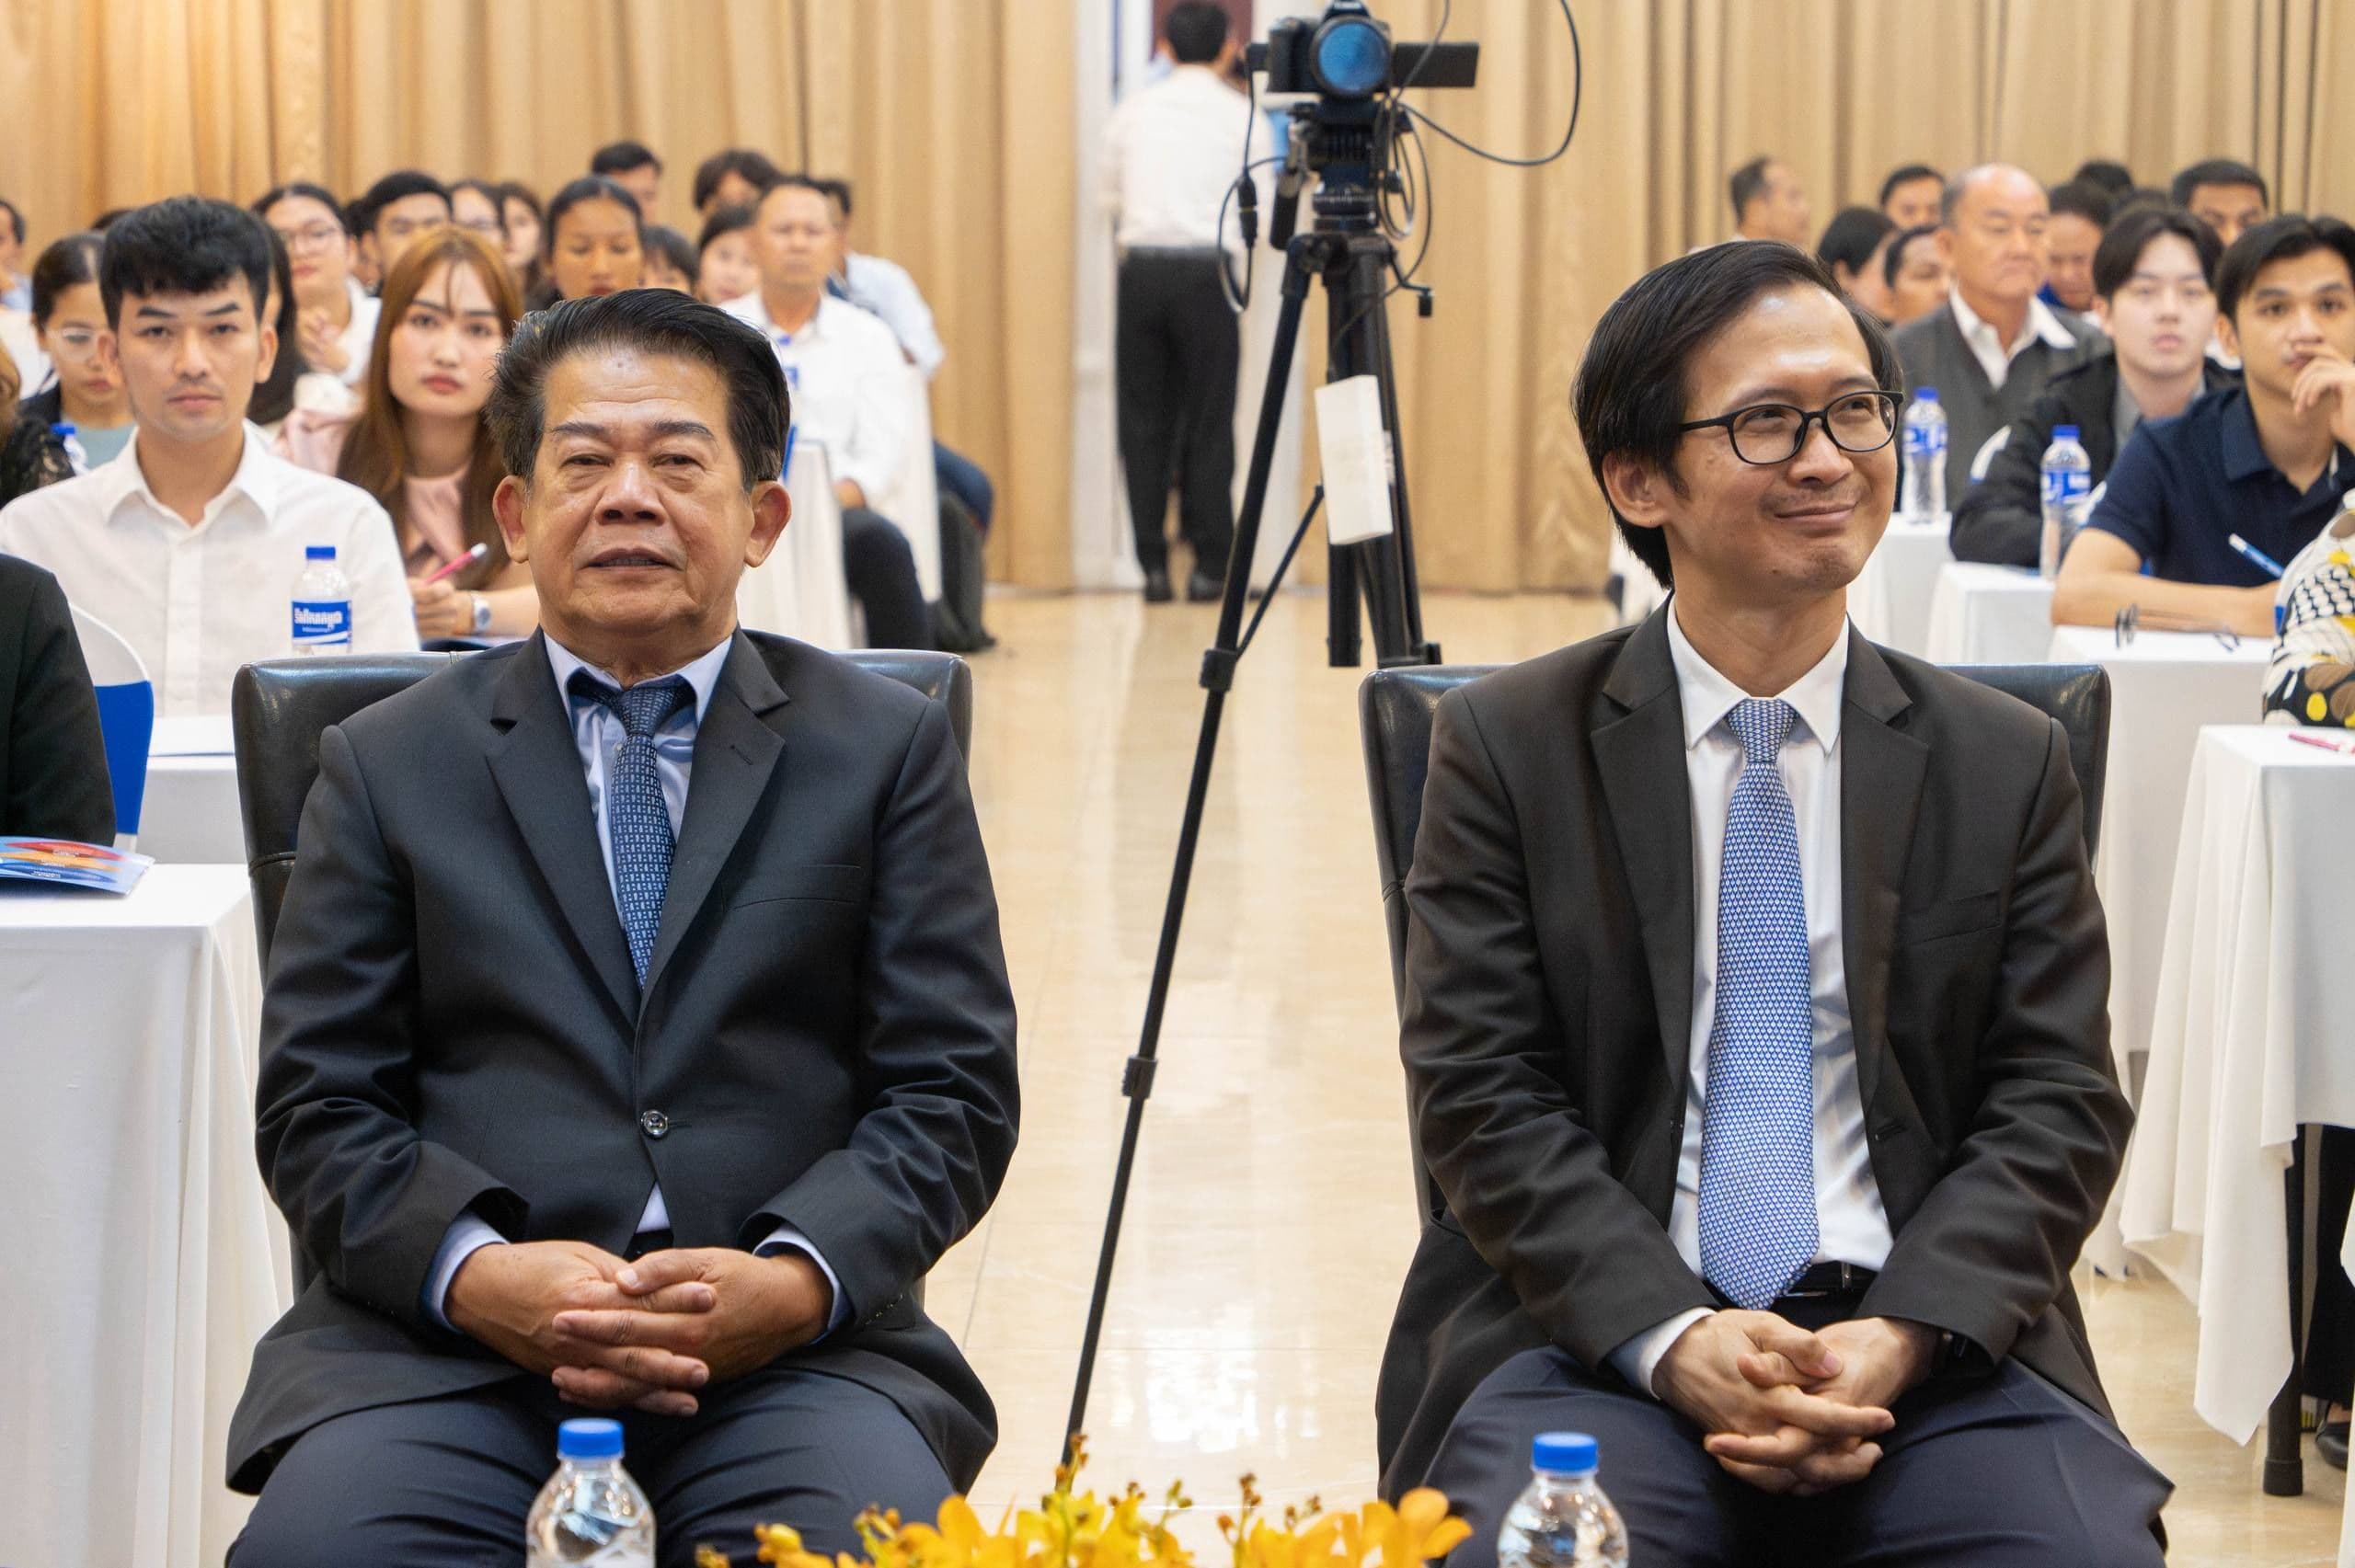
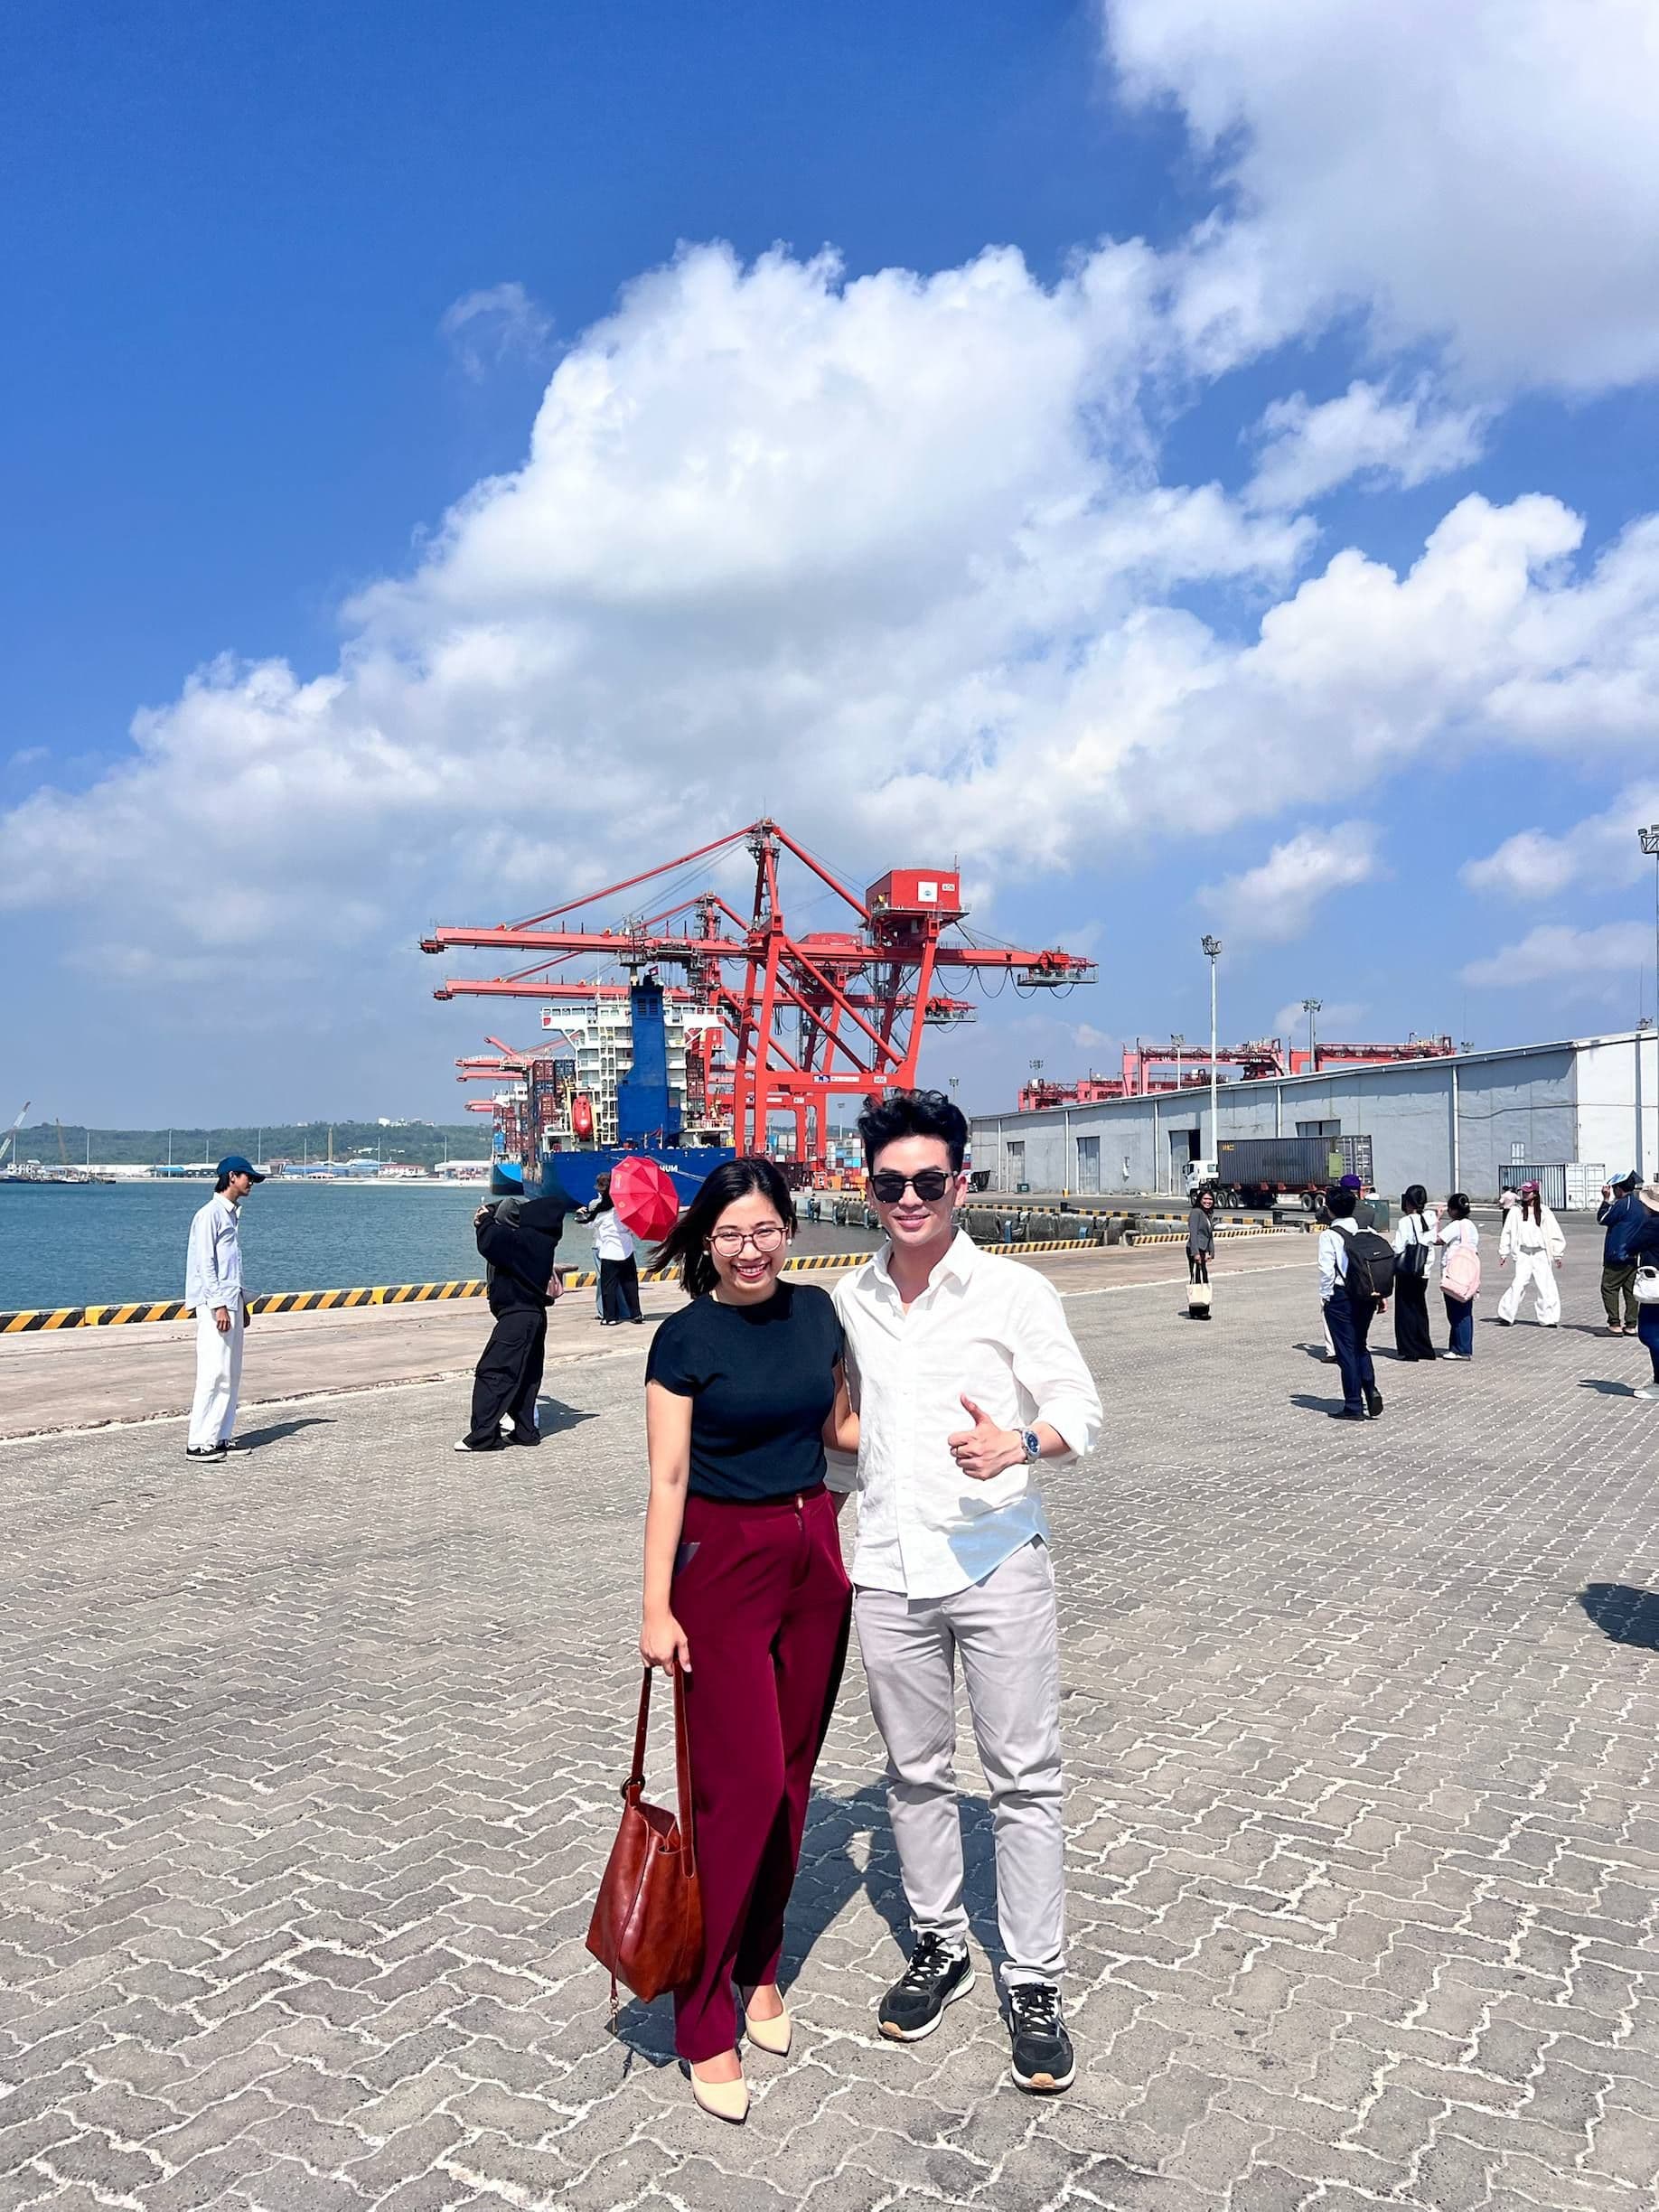
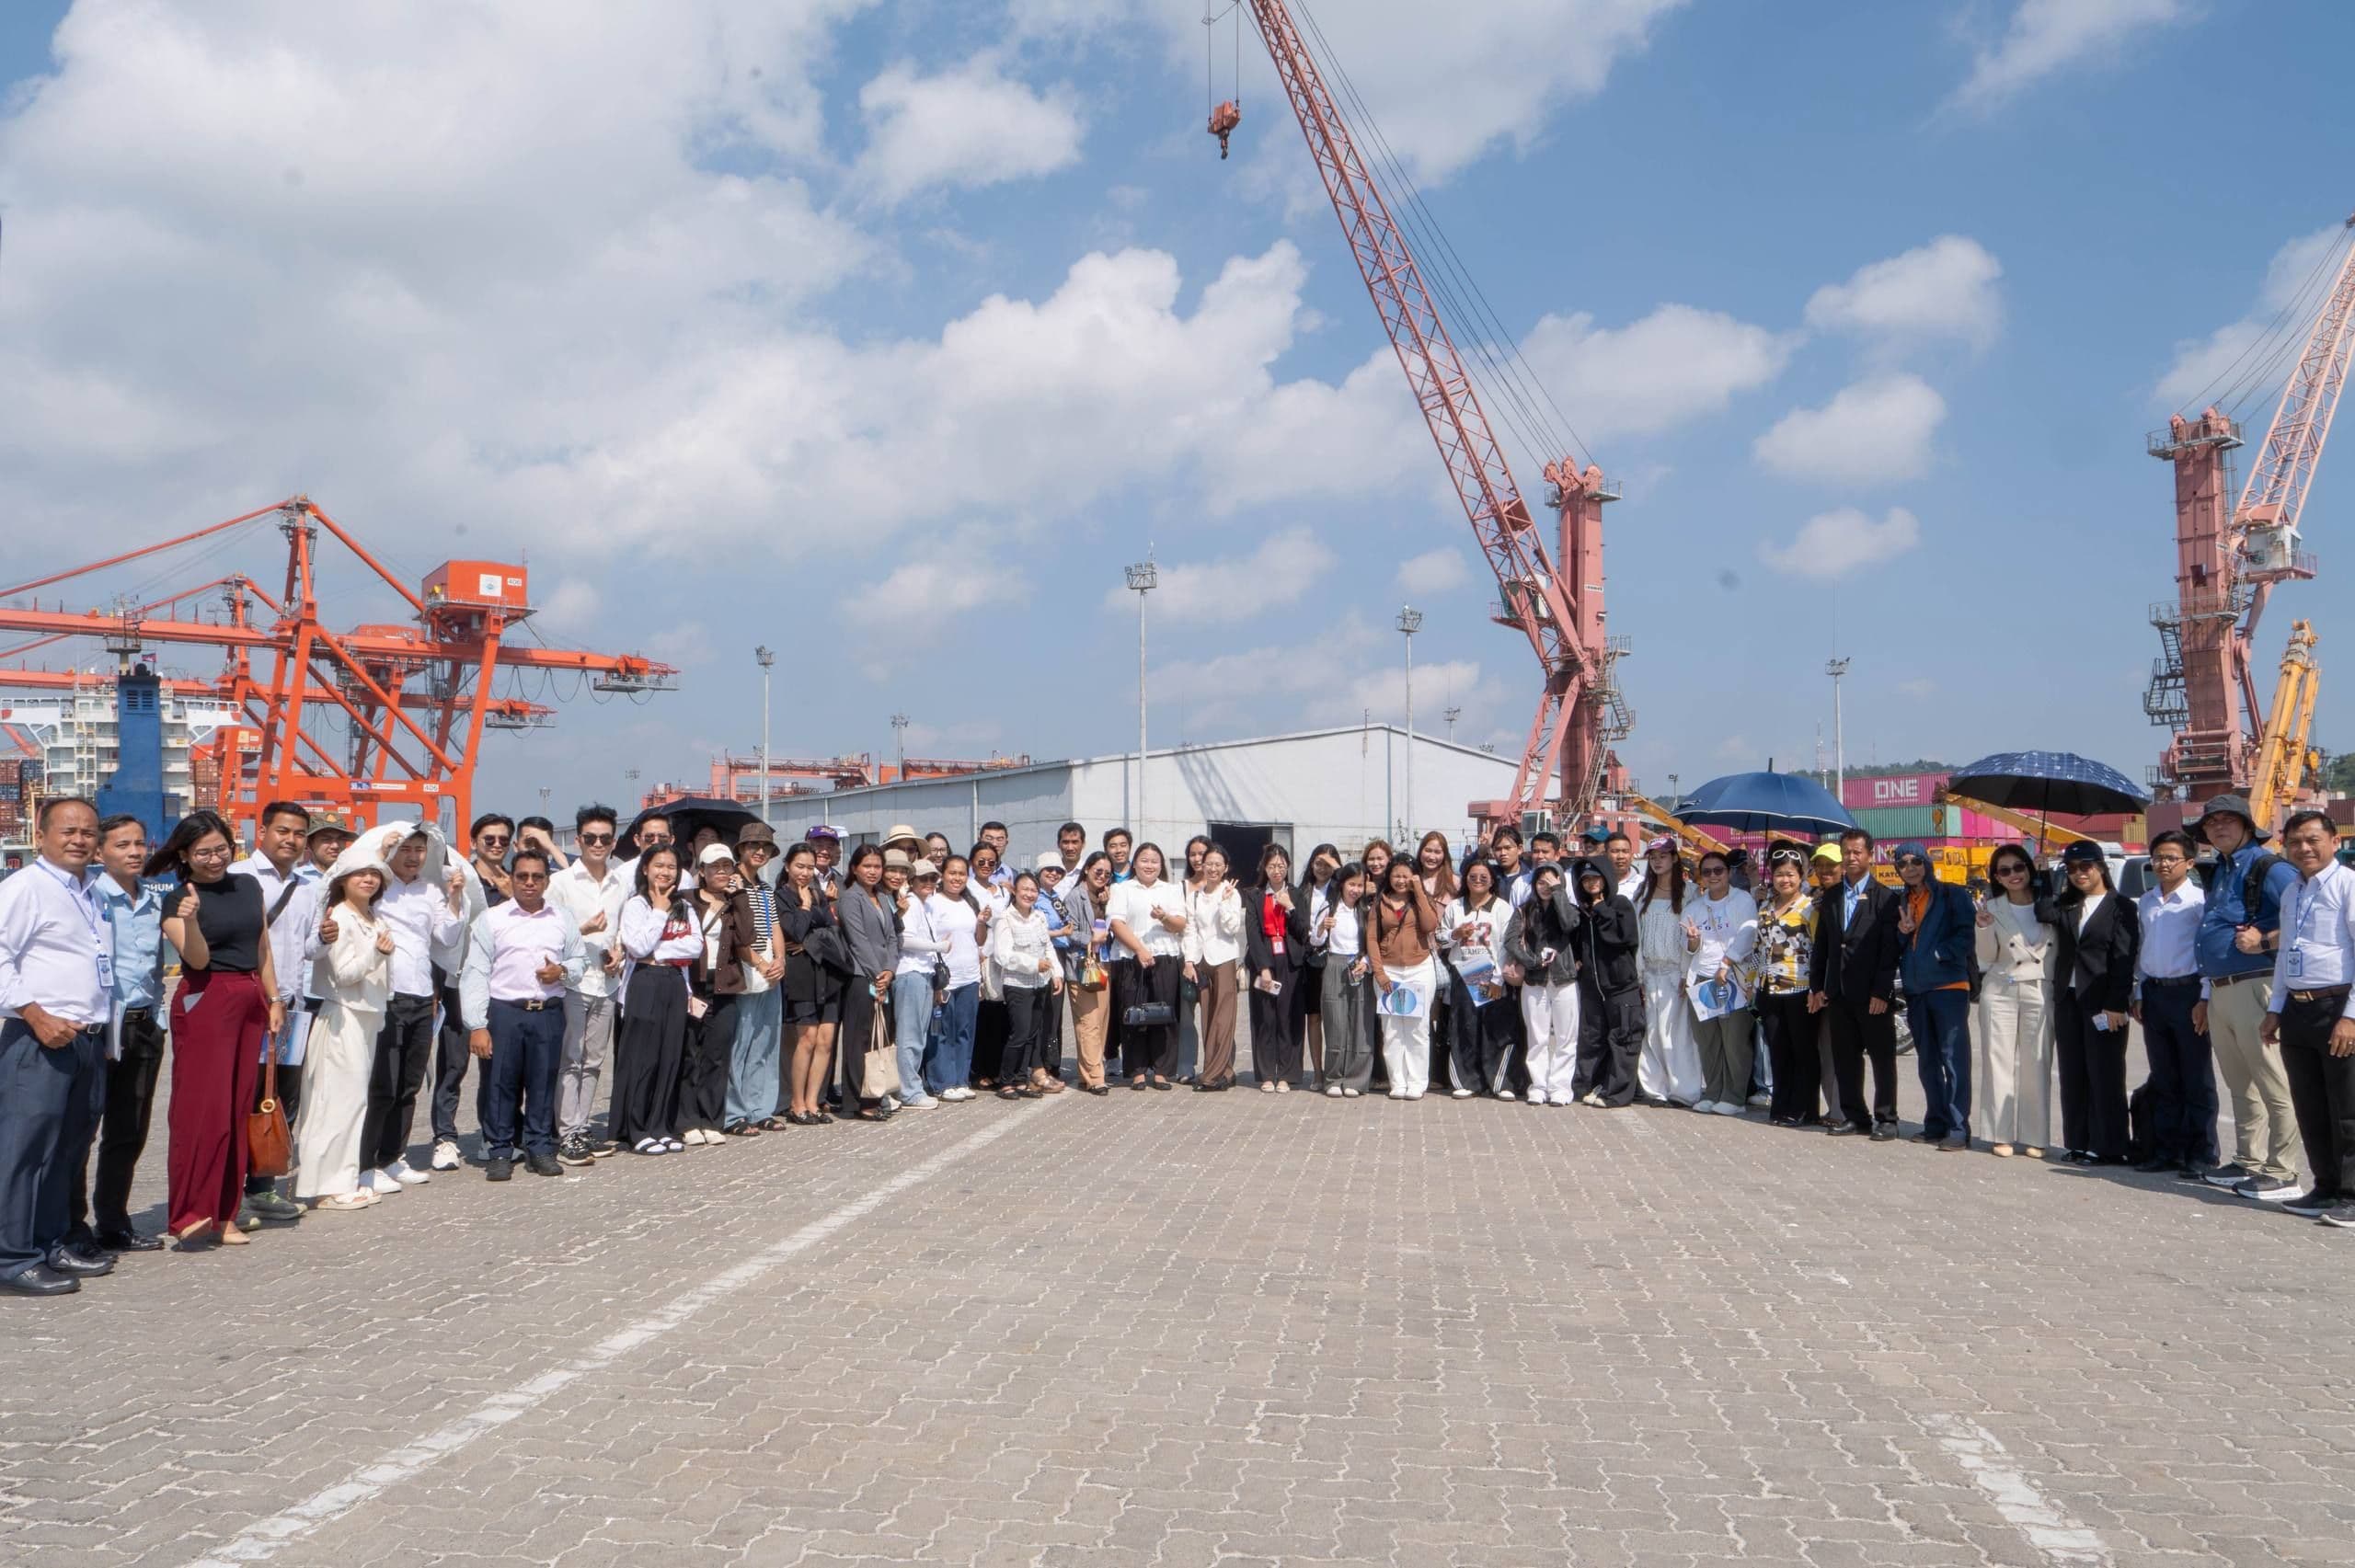
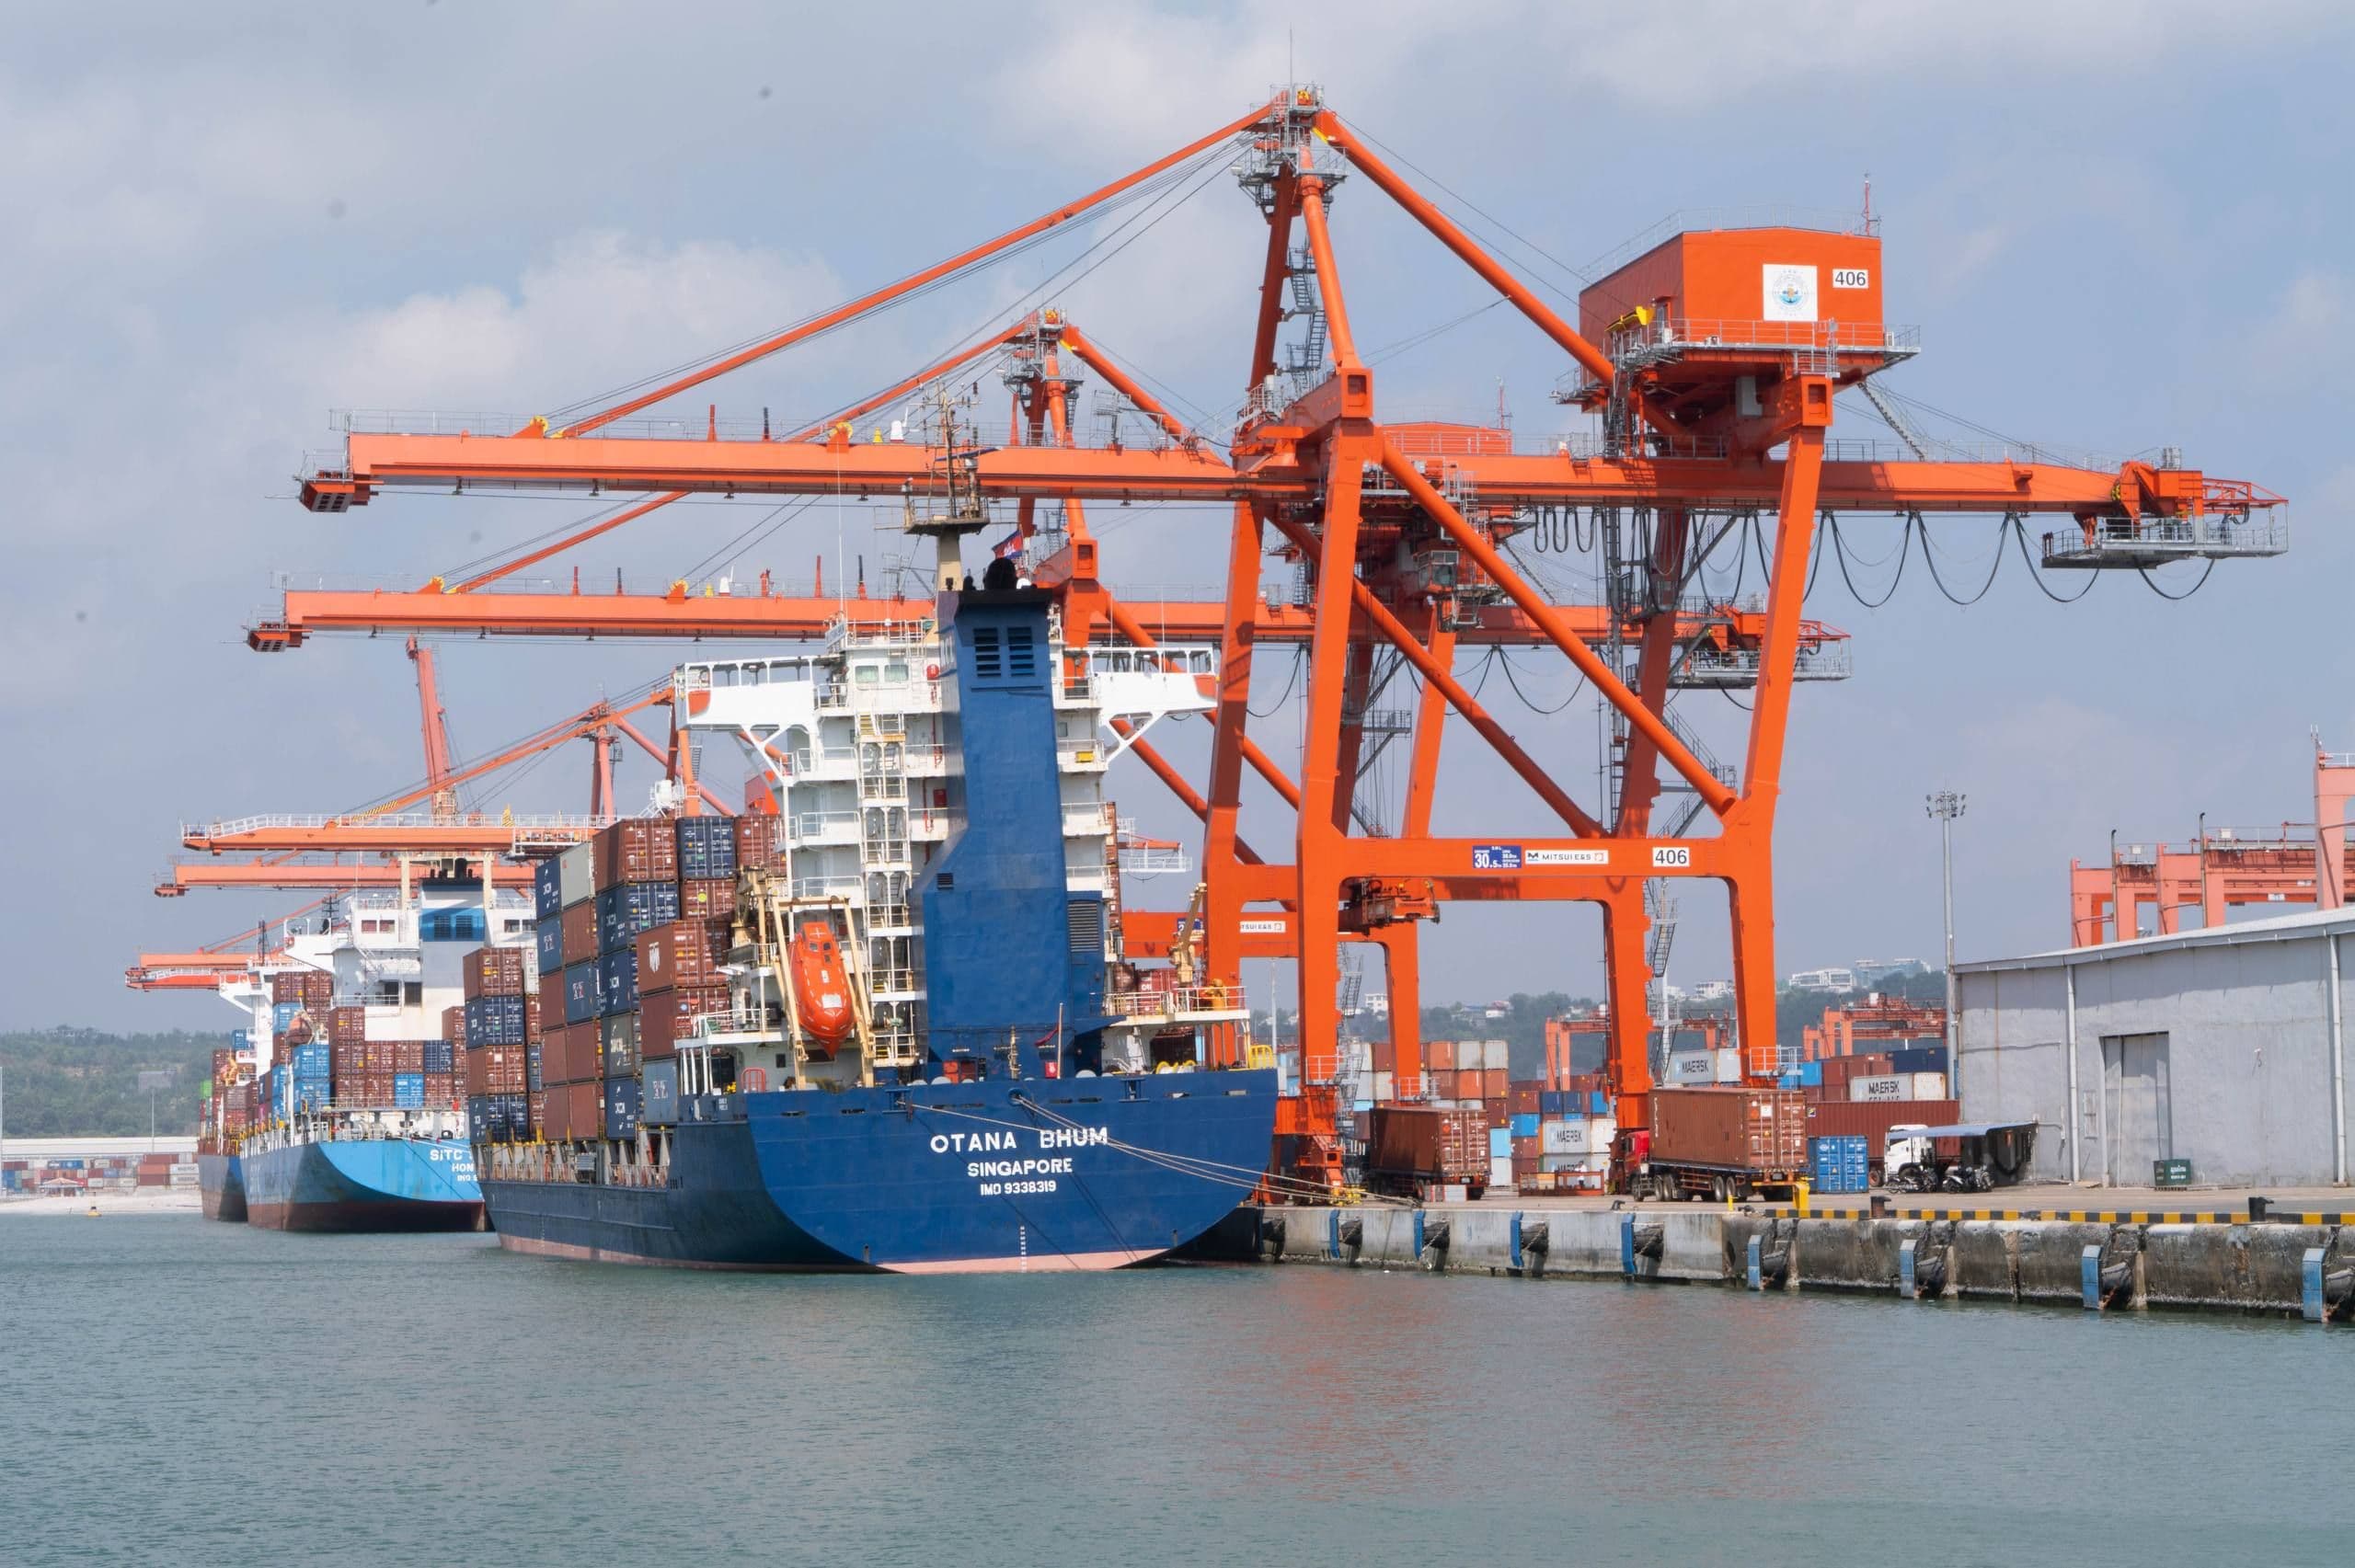
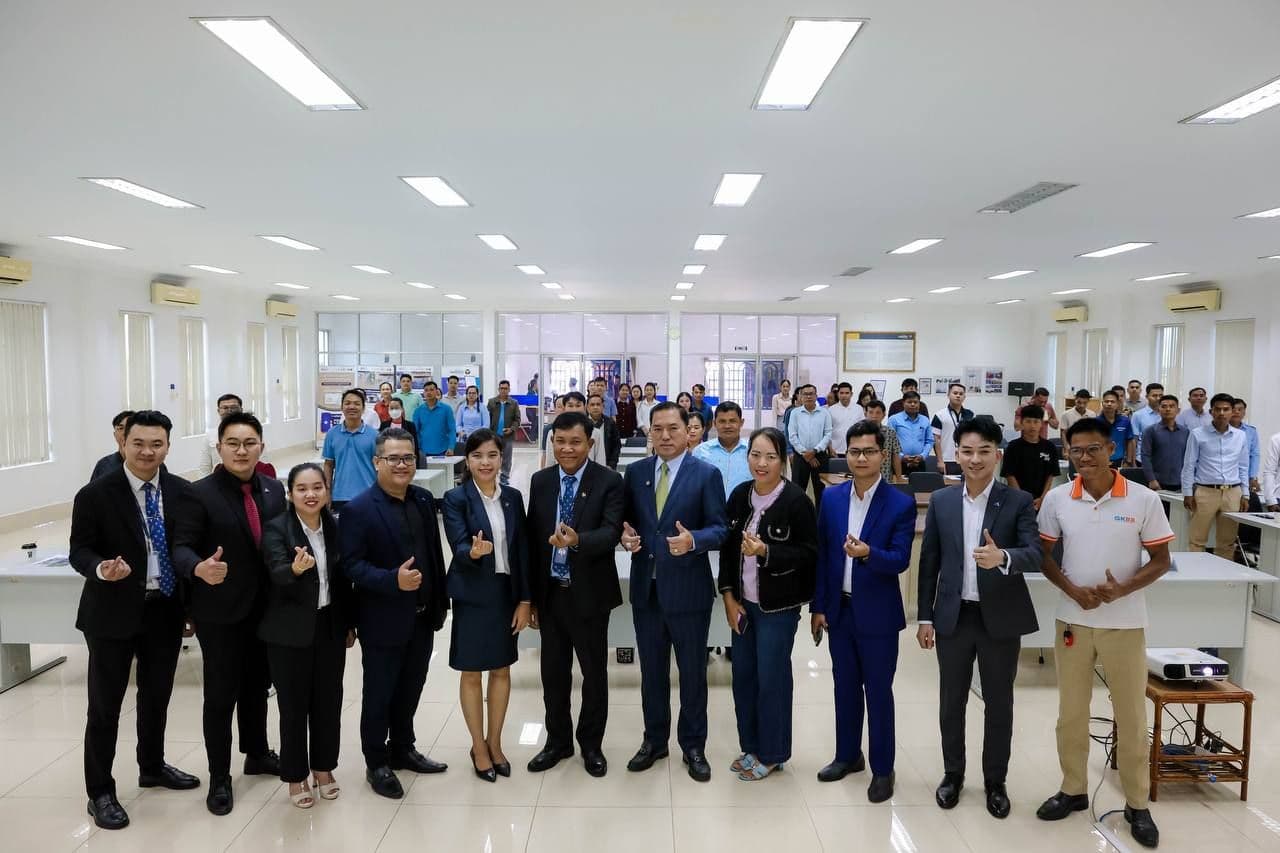
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the Listed Companies Forum on the topic: Potential of Sihanoukville Autonomous Port and Site Visit, organized by Cambodia Securities Exchange (CSX) on 06 April 2026.

The forum, held at Sihanoukville Autonomous Port (PAS), was under the high presidency of H.E. Lou Kim Chhun, Delegate of the Royal Government of Cambodia in charge as Chairman & CEO of the Cambodia Securities Exchange (CSX), and H.E. Hong Sokhour, Delegate of the Royal Government in charge as CEO of the Cambodia Securities Exchange (CSX), highlighting the potential and business operations of the port.

Our representatives, Mrs. Edeza Banquilis, Head of Growth & Strategy, and Mr. Sok Chantola, Deputy Sales & Marketing Manager, attended the event. The session and site visit provided valuable perspectives on Cambodia’s capital market growth and port development.

分享

更多洞察

2026 October Market Outlook: Asia Markets – AI Valuation Concerns and Rising Geopolitical Risks
Market Outlook2026年11月2日

2026 October Market Outlook: Asia Markets – AI Valuation Concerns and Rising Geopolitical Risks

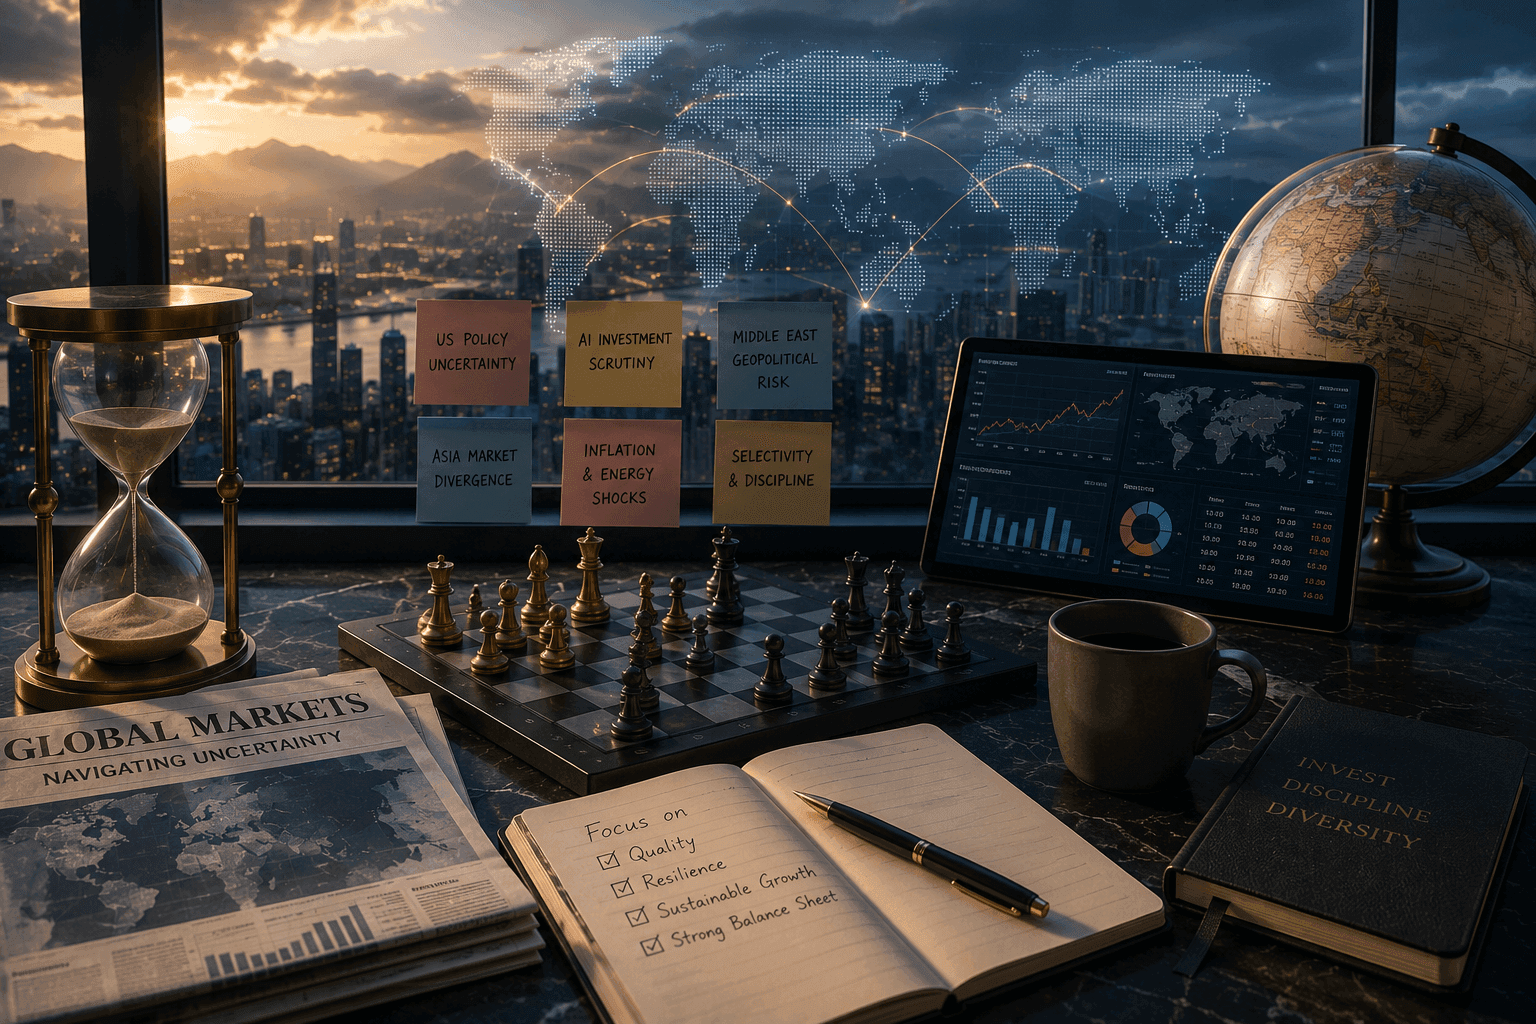
The direction of US monetary policy remains a key source of uncertainty. Minutes from the September Federal Open Market Committee (“FOMC”) meeting indicated that a further rate increase before year-end remains possible. However, Chair Warsh has declined to commit to a path, identifying the October and December meetings as the key decision points. Ahead of the next FOMC meeting on 27–28 October, the International Monetary Fund has cautioned that uncertainty over US monetary policy could keep Asian financial markets volatile. The recent sell-off has also brought the financing of AI investment into sharper focus. Chair Warsh noted that large technology companies raising funds in the bond market are adding to competition for capital. In our view, investors are likely to place greater scrutiny on the returns these companies generate from their AI spending. Developments in the Middle East remain a key swing factor for oil prices and inflation. Before the conflict began in late February, the Strait of Hormuz carried around one-fifth of global oil supply. Within Asia, the most significant development has been in Indonesia. On 15 October, index provider MSCI Inc. launched a consultation on reclassifying Indonesia from Emerging Market to Standalone Market status, citing insufficient progress on market transparency, concentrated shareholdings and weak enforcement. This contrasts with FTSE Russell, which reaffirmed Indonesia’s emerging market status. The Jakarta Composite Index fell 8.0% following the announcement, which triggered a trading halt. MSCI has also frozen certain index changes for Indonesian securities, including new additions, until further notice. The announcement adds to a difficult year for Indonesia, whose stock market has fallen more than 30% to become the world’s worst performing this year, according to Bloomberg, while Moody’s and Fitch have both revised the sovereign rating outlook to negative. With the consultation open until 30 April 2027, analysts expect foreign outflows to continue. In North Asia, the October sell-off highlighted how exposed South Korea and Taiwan have become to swings in AI sentiment after very strong gains over the past year. The KOSPI and TAIEX rose 86.7% and 80.6% respectively over the past year, and the TAIEX’s price-to-earnings ratio has expanded to 27.9 times from 23.1 times. Singapore again demonstrated its defensive qualities, with the Straits Times Index declining only 0.5% on 15 October, a far smaller fall than its North Asian peers. Overall, investor sentiment has shifted from chasing AI momentum towards greater caution on valuations, funding costs, and geopolitical risk. In this environment, we remain focused on businesses with strong balance sheets, sustainable earnings and pricing power, which we believe are better positioned to navigate persistent inflation and energy price shocks. We continue to apply a disciplined, bottom-up approach to stock selection and to maintain diversification across geographies and themes.

3 分钟阅读阅读更多
BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026
公告2026年10月23日

BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026

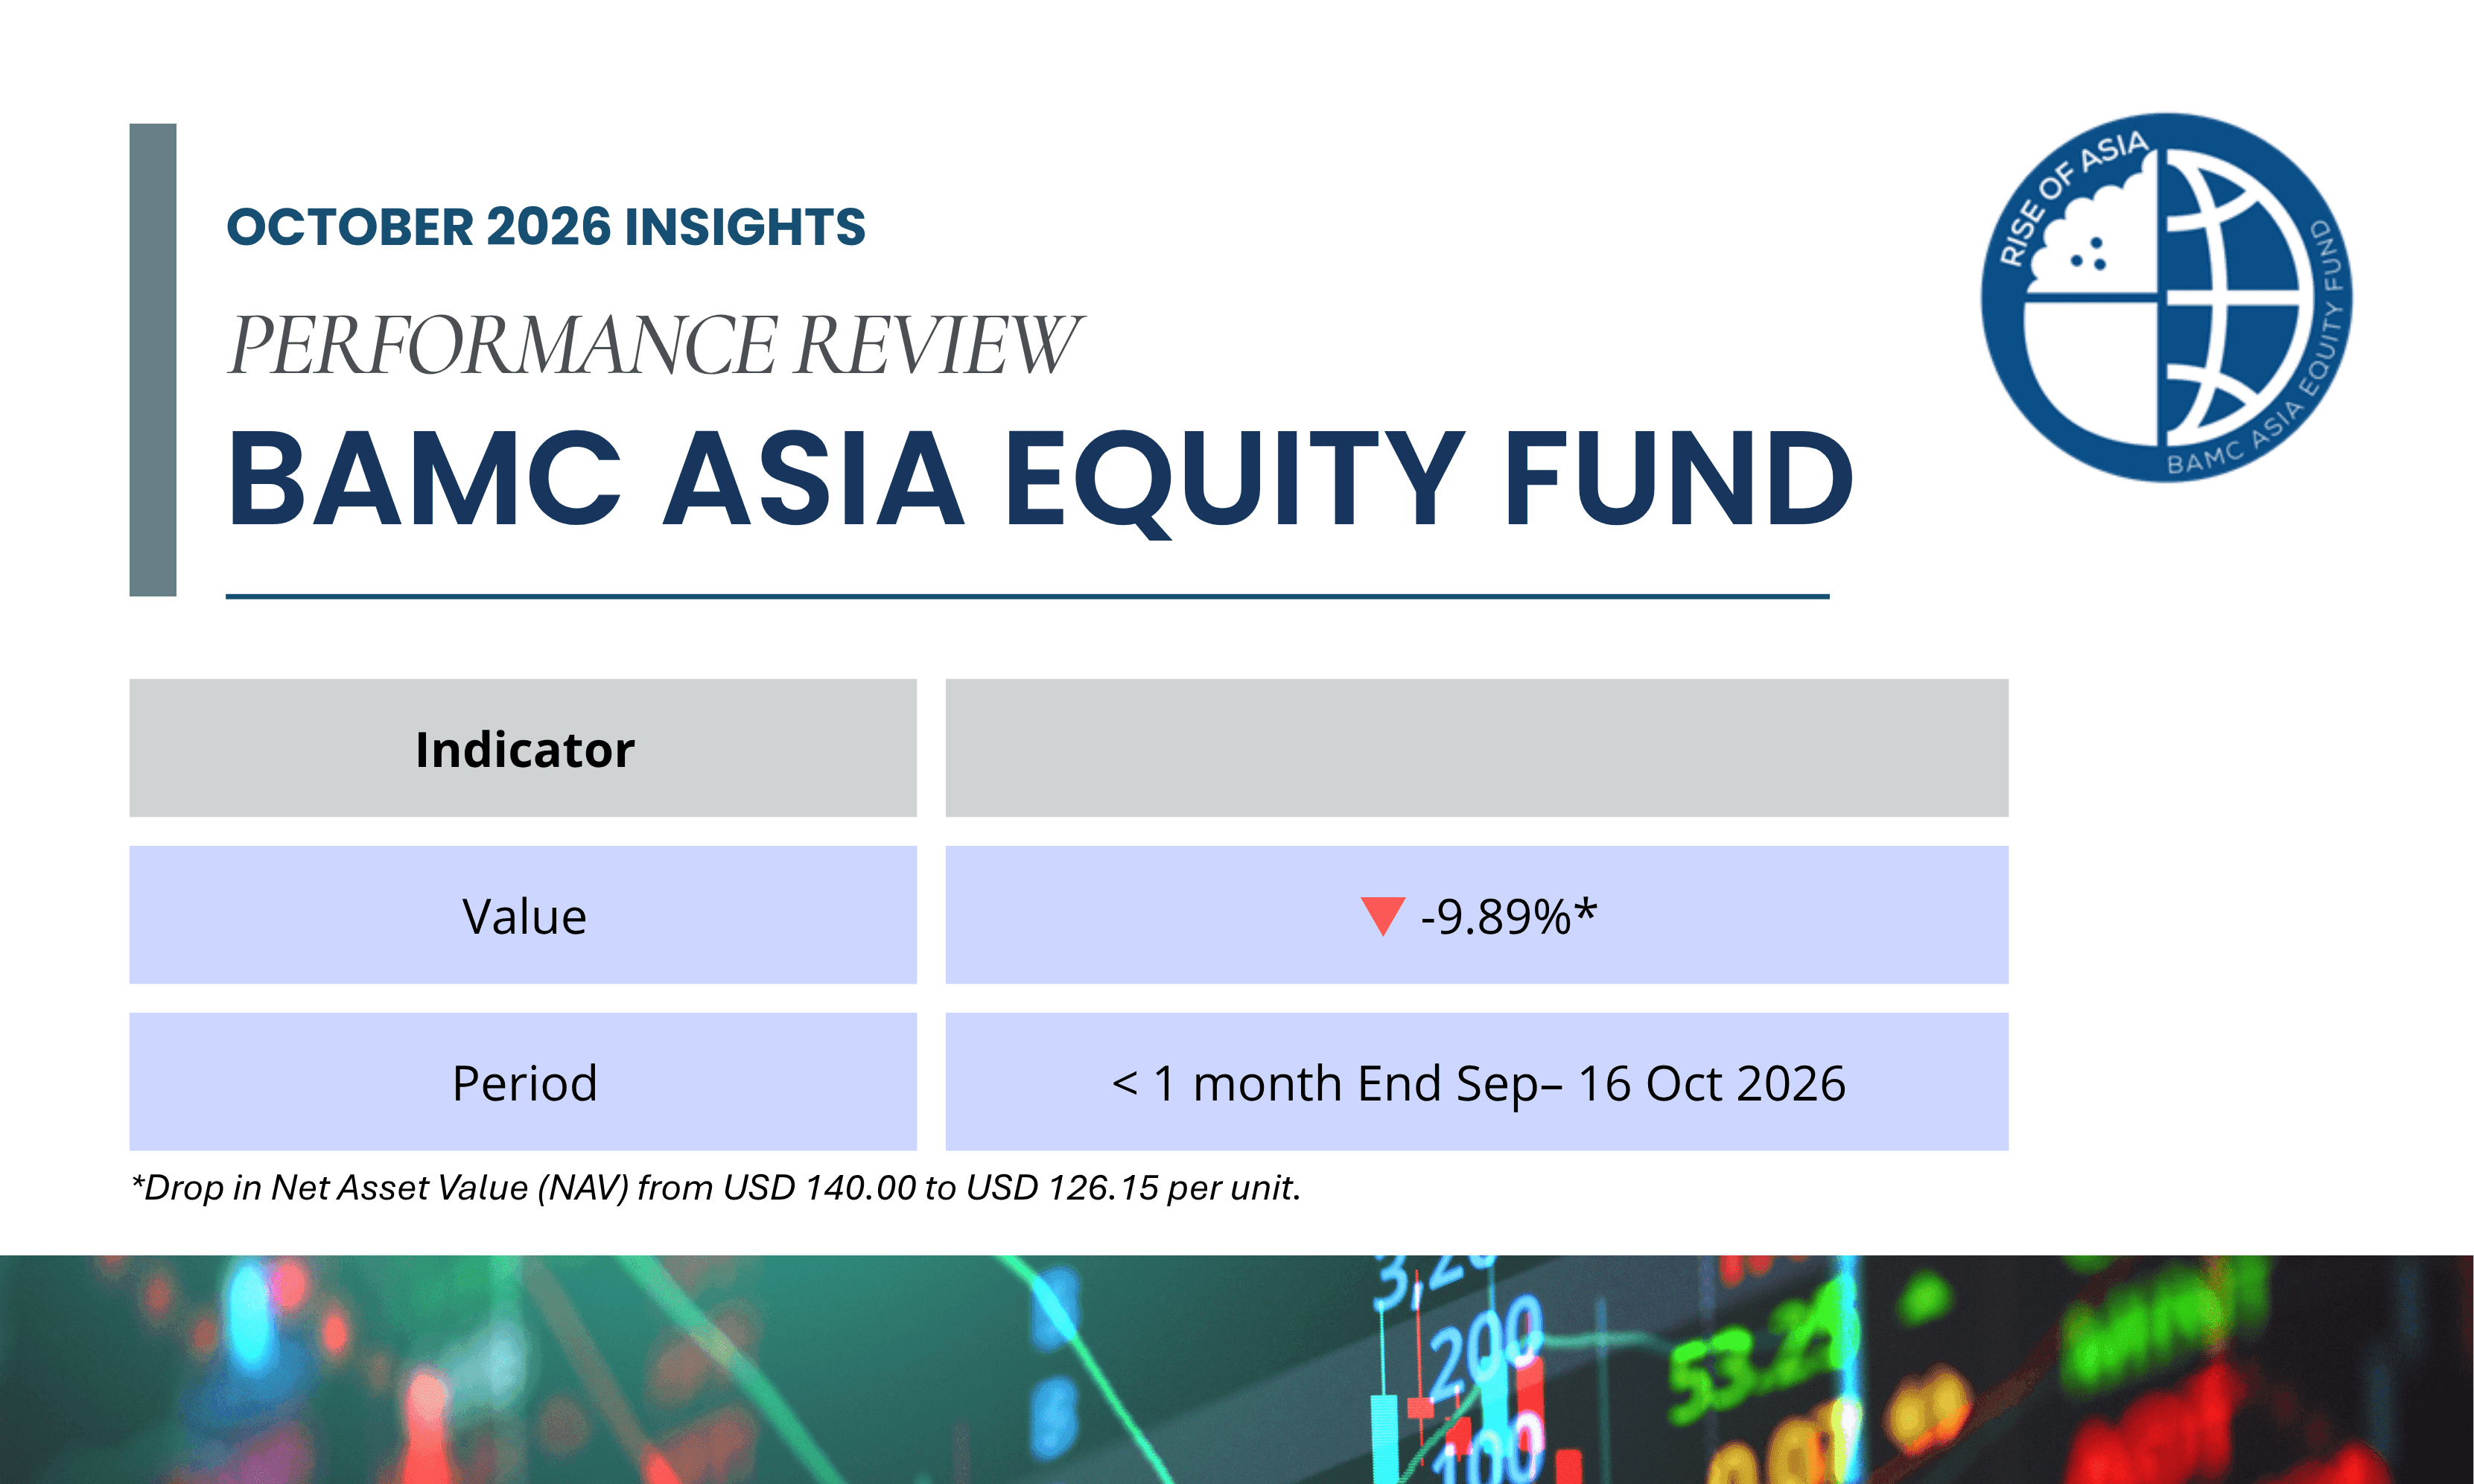
Markets in October Since end September, global equities have faced pressure from higher borrowing costs and growing scrutiny of the returns from AI related spending. Stronger than expected US inflation reinforced expectations of further Federal Reserve tightening, weighing particularly on technology and semiconductor valuations. Elevated oil prices added further pressure on inflation concerns. Overall, technology-heavy Asian markets bore a greater share of the selling in October’s global tech weakness. Our exposure to Asian equities reflects our focus on the region’s long-term growth opportunities. Short-term volatility is an inherent risk of this approach, but our investment decisions remain anchored in companies’ fundamentals and their potential to generate sustainable returns over time. Portfolio underperformance Against this backdrop, BAEF’s main drag was its concentration in Korean and Taiwanese equities and semiconductor related holdings, which together accounted for 32.3% of the portfolio and approximately 4% of the calculated drag. The Korea ETF and Samsung alone contributed roughly 2%. Korea was particularly affected by the unwinding of AI-related positions. On 15 October, its benchmark equity index fell approximately 8%. Samsung’s weakness came despite guidance for a substantial increase in third-quarter operating profit, suggesting that concerns over valuations, financing conditions and competition outweighed the near-term earnings improvement. The drop was compounded by sharp falls in several Singapore small caps and financials. Addvalue fell 22.9%, UOB Kay-Hian 25.2%, OCBC 10.3%. OCBC faced a specific catalyst when Citi downgraded the stock from “neutral” to “sell”, citing risks to third-quarter earnings, pressure on net interest margins from higher deposit costs, and the potential normalisation of exceptionally strong first-half wealth-related income. Addvalue’s share price weakness is due to profit-taking after a strong run. Singapore’s semiconductor-related suppliers to chipmakers fell harder than the larger chipmakers; Frencken fell 14.9%, UMS 14.8% and AEM 9.9%. Together, these holdings constituted approximately 14% of the portfolio and implied another 2.3% of drag. Like the global technology sell-off, broader concerns over the AI investment cycle were weighing on sentiment beyond individual companies’ reported performance. There were few meaningful offsets in the portfolio as gains elsewhere were insufficient to counter the losses. Why we still hold these stocks Despite the recent weakness, we retain these holdings because the underlying earnings drivers remain relevant to our investment horizon. The sell-off has weakened share prices more than the underlying medium- to long-term investment case. In semiconductors, the correction has coincided with continued growth in demand for AI compute. TSMC’s latest results and guidance pointed to sustained demand for advanced chips, while Samsung’s earnings guidance reflected stronger memory sales and pricing. These developments support maintaining exposure to the sector, although we recognise that strong operating performance does not eliminate valuation risk or the possibility of further share price volatility. Our Singapore semiconductor holdings provide exposure to different parts of this investment cycle. UMS benefits from equipment demand and increasing exposure to advanced packaging, AEM offers participation in increasingly complex semiconductor testing, and Frencken provides a more diversified manufacturing exposure. The rationale for retaining these positions rests on their prospective earnings as customers invest in additional capacity and advanced chip architectures, rather than an expectation that all semiconductor-related stocks will recover together. For the financial holdings, recent operating results provide a basis for distinguishing share price weakness from deterioration in the businesses. OCBC’s wealth-management and other non-interest income have helped offset pressure on lending margins, while its capital position continues to support business growth and distributions. UOB Kay Hian reported substantially higher first-half earnings, supported by stronger trading activity, commission income and interest income. We retain exposure to these earnings streams, while recognising that wealth related revenue and brokerage activity are market sensitive and that recent growth rates may not persist. We retain exposure to Addvalue to the long-term growth in satellite connectivity and space infrastructure. Recent share-price weakness appears to reflect, in part, profit-taking following a strong rally, while continued orders support the underlying growth outlook. In september, Addvalue announced US$15 million of new orders across its space connectivity and advanced digital radio business, bringing its order book to US$20.2 million. Converting these orders into earnings and cash flow remains central to our investment case. Overall, we remain selective and view the decline as a potential opportunity to top up positions rather as a reason to hold every position unchanged. Continued ownership must be supported by company fundamentals, an acceptable valuation, and grounded in earnings growth. Moving forward Looking ahead, we intend to increase exposure to quality large-cap and blue-chip companies to strengthen portfolio resilience amid continued volatility. We will prioritise businesses with sound balance sheets, sustainable earnings and cash flows, and durable competitive advantages. Further market weakness could provide opportunities to build positions at more attractive entry prices, while maintaining a disciplined approach to valuation. Disclaimer : This Document is issued for information and investor awareness purposes only to explain the factors contributing to the changes in BAEF’s NAV. It does not constitute investment advice, an investment recommendation, an offer, or a solicitation to buy, sell, or hold units of BAEF. The information provided herein should not be relied upon as the sole basis for any investment decision and does not guarantee future performance. Investors should refer to the Fund’s official offering documents and disclosures and carefully assess their own investment objectives and risk tolerance before making any investment decision.

4 分钟阅读阅读更多
2026 September Market Outlook: Navigating Market Divergence
Market Outlook2026年10月1日

2026 September Market Outlook: Navigating Market Divergence

The Fed maintained a restrictive, data-dependent stance through August and subsequently raised the federal funds target range by 25 basis points to 3.75-4.00% citing persistent inflationary pressures. Updated projections point to the possibility of one further increase in 2026. Elevated long-dated US Treasury yields continue to present a valuation risk particularly for growth, technology and AI-related companies, whose expected cash flows lie further in the future. At the same time, continued corporate earnings delivery and investments in strategic technologies along the tech supply chain have so far helped the global economy absorb tighter financial conditions. Strong earnings guidance from major global technology companies supports the view that investment in data centres, advanced chips and supporting infrastructure remains resilient. Within Asia, performance has diverged meaningfully across countries. Singapore remains the region’s defensible market, with strong banking profitability and wealth management inflows attracting investor interest amid global uncertainty. Taiwan and South Korea’s technology sector continues to be major beneficiaries of surging AI-related demand. On the other hand, confidence towards China’s and Indonesia’s growth outlook remains fragile. China’s slow economic momentum is a result of a weak property market and slow domestic consumption, while Indonesia’s commodity price normalisation and concerns over capital outflows weigh on sentiment. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.

1 分钟阅读阅读更多
Banjaran AMC Brings BAEF Investment Opportunities to Investors in Phnom Penh Through 3rd Round Roadshow
路演2026年9月5日

Banjaran AMC Brings BAEF Investment Opportunities to Investors in Phnom Penh Through 3rd Round Roadshow

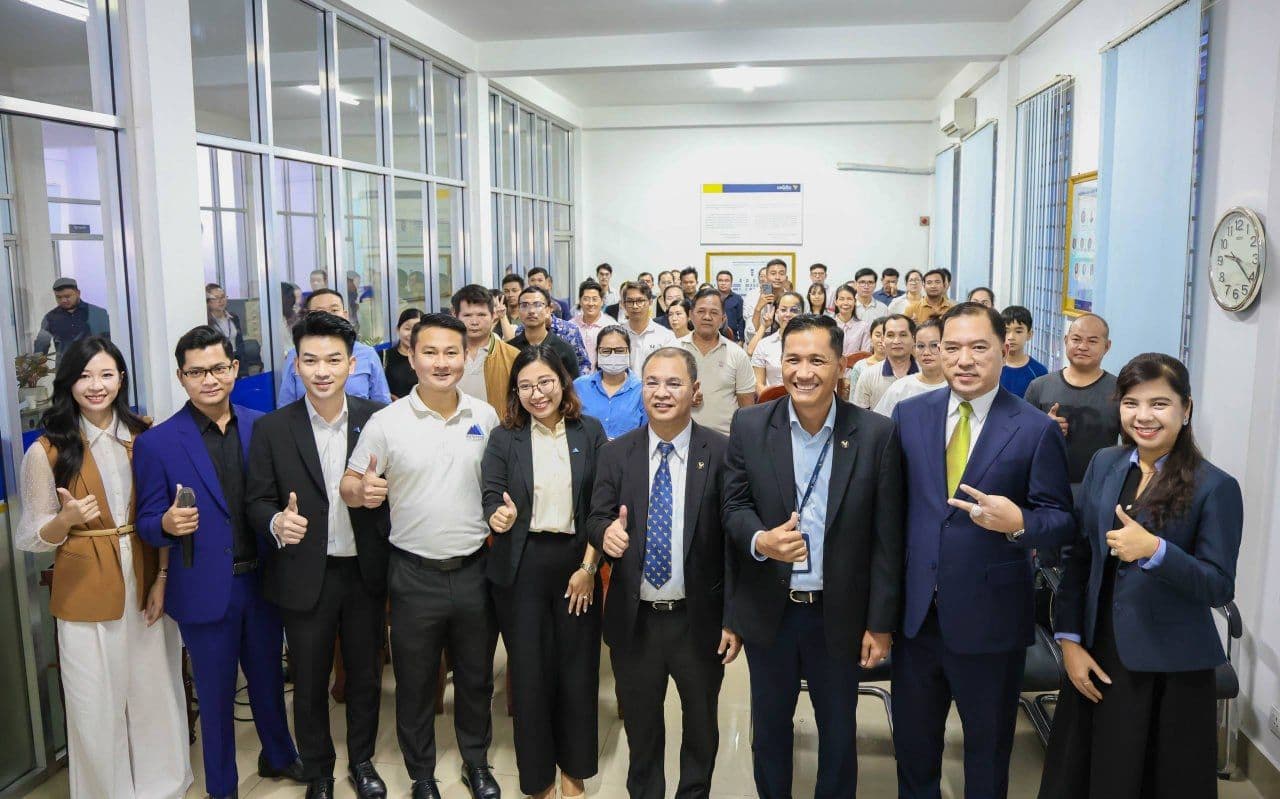
Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01) on the morning of 05 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial

1 分钟阅读阅读更多
2026 August Market Outlook: Navigating Volatility
Market Outlook2026年9月1日

2026 August Market Outlook: Navigating Volatility

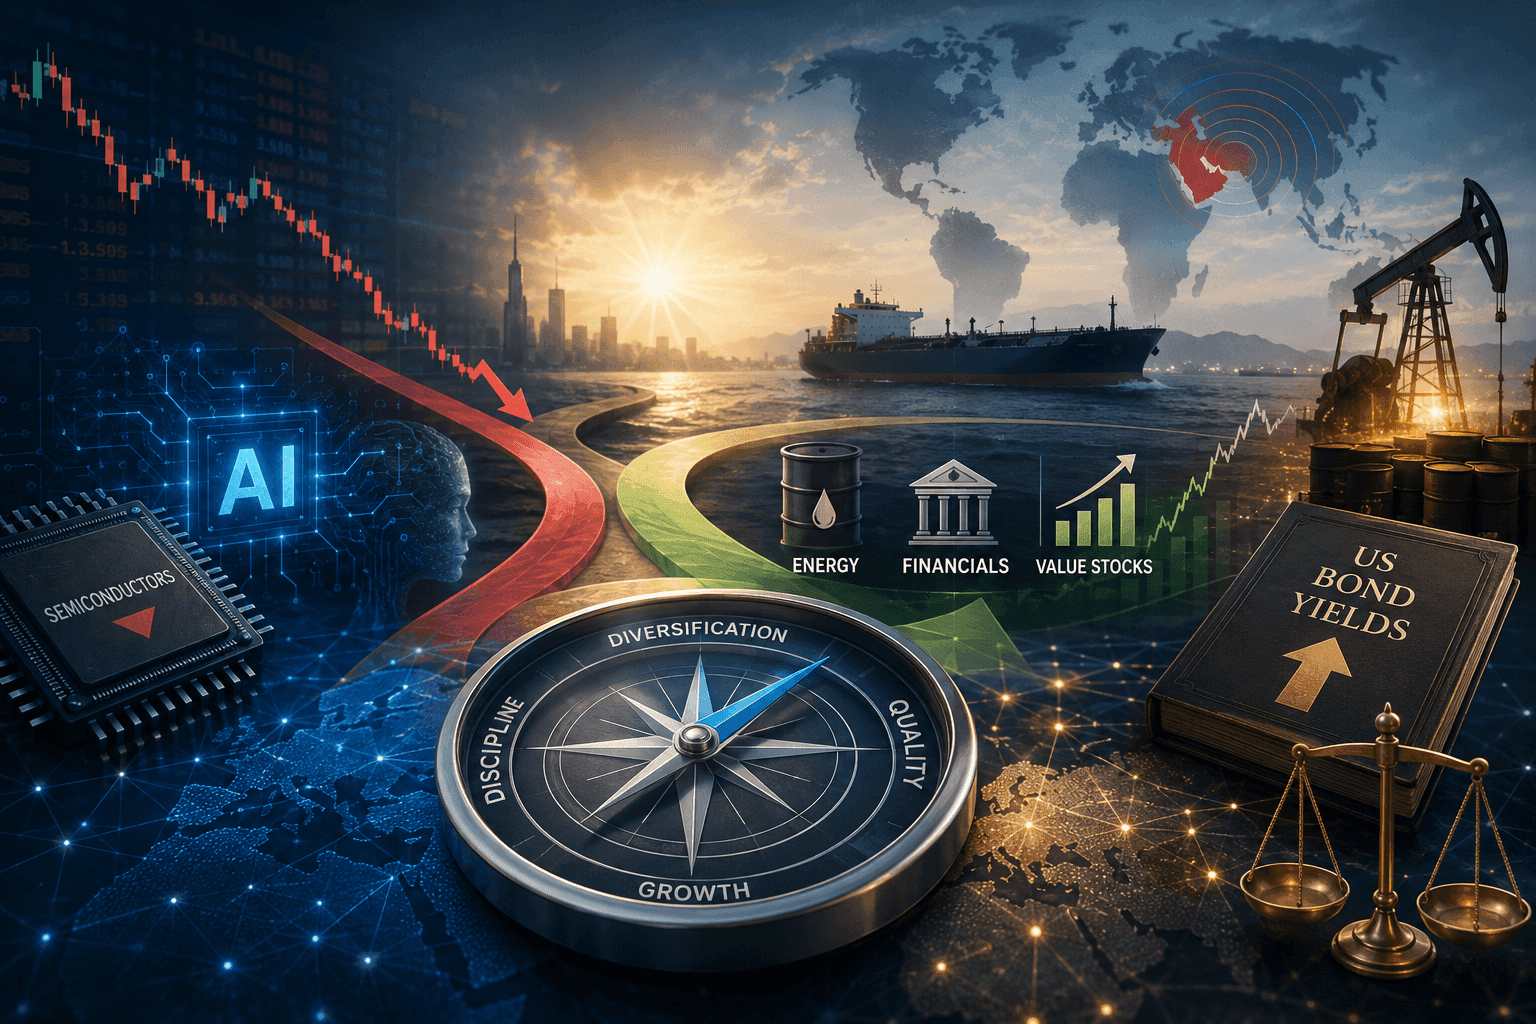
Concerns around the durability of AI-related capital expenditure and intensifying competition triggered a sharp sector sell-off after a mid-July peak. Investor sentiment turned more discerning on the back of earnings season, and questions arose regarding how sustainable the AI investment pace is without eating into cash generation. Capital rotated out of semiconductors and into energy, financials and value stocks, shifting to markets and names seen as less exposed to a single-theme correction. Layered on top was renewed Middle East escalation and its effect on rates expectations. Brent crude spiked back above $100/barrel intermittently after the US reinstated a naval blockade on Iran and announced plans to impose a levy on cargo transiting Hormuz, although the levy was never implemented. This revived inflation concerns and caused markets to price a reduced likelihood of further Fed easing. Elevated US bond yields further weighed on stocks. Looking ahead, renewed conflict or another AI-related pullback could swiftly unwind recent sentiment gains and force a repricing of both rates and earnings expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.

1 分钟阅读阅读更多
Banjaran AMC Expands Securities Investment Awareness Through 3rd Round Roadshow in Svay Rieng
路演2026年8月22日

Banjaran AMC Expands Securities Investment Awareness Through 3rd Round Roadshow in Svay Rieng

Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., and ACLEDA Bank Plc. Local Branch (Svay Rieng Province), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Svay Rieng Province) on the morning of 22 August 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Taing Hoy, Legal and Compliance Officer of Banjaran Asset Management (Cambodia) Plc., on the topic “Investment Value and Benefits of the BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial

1 分钟阅读阅读更多