洞察
活动2024年10月10日1 分钟阅读

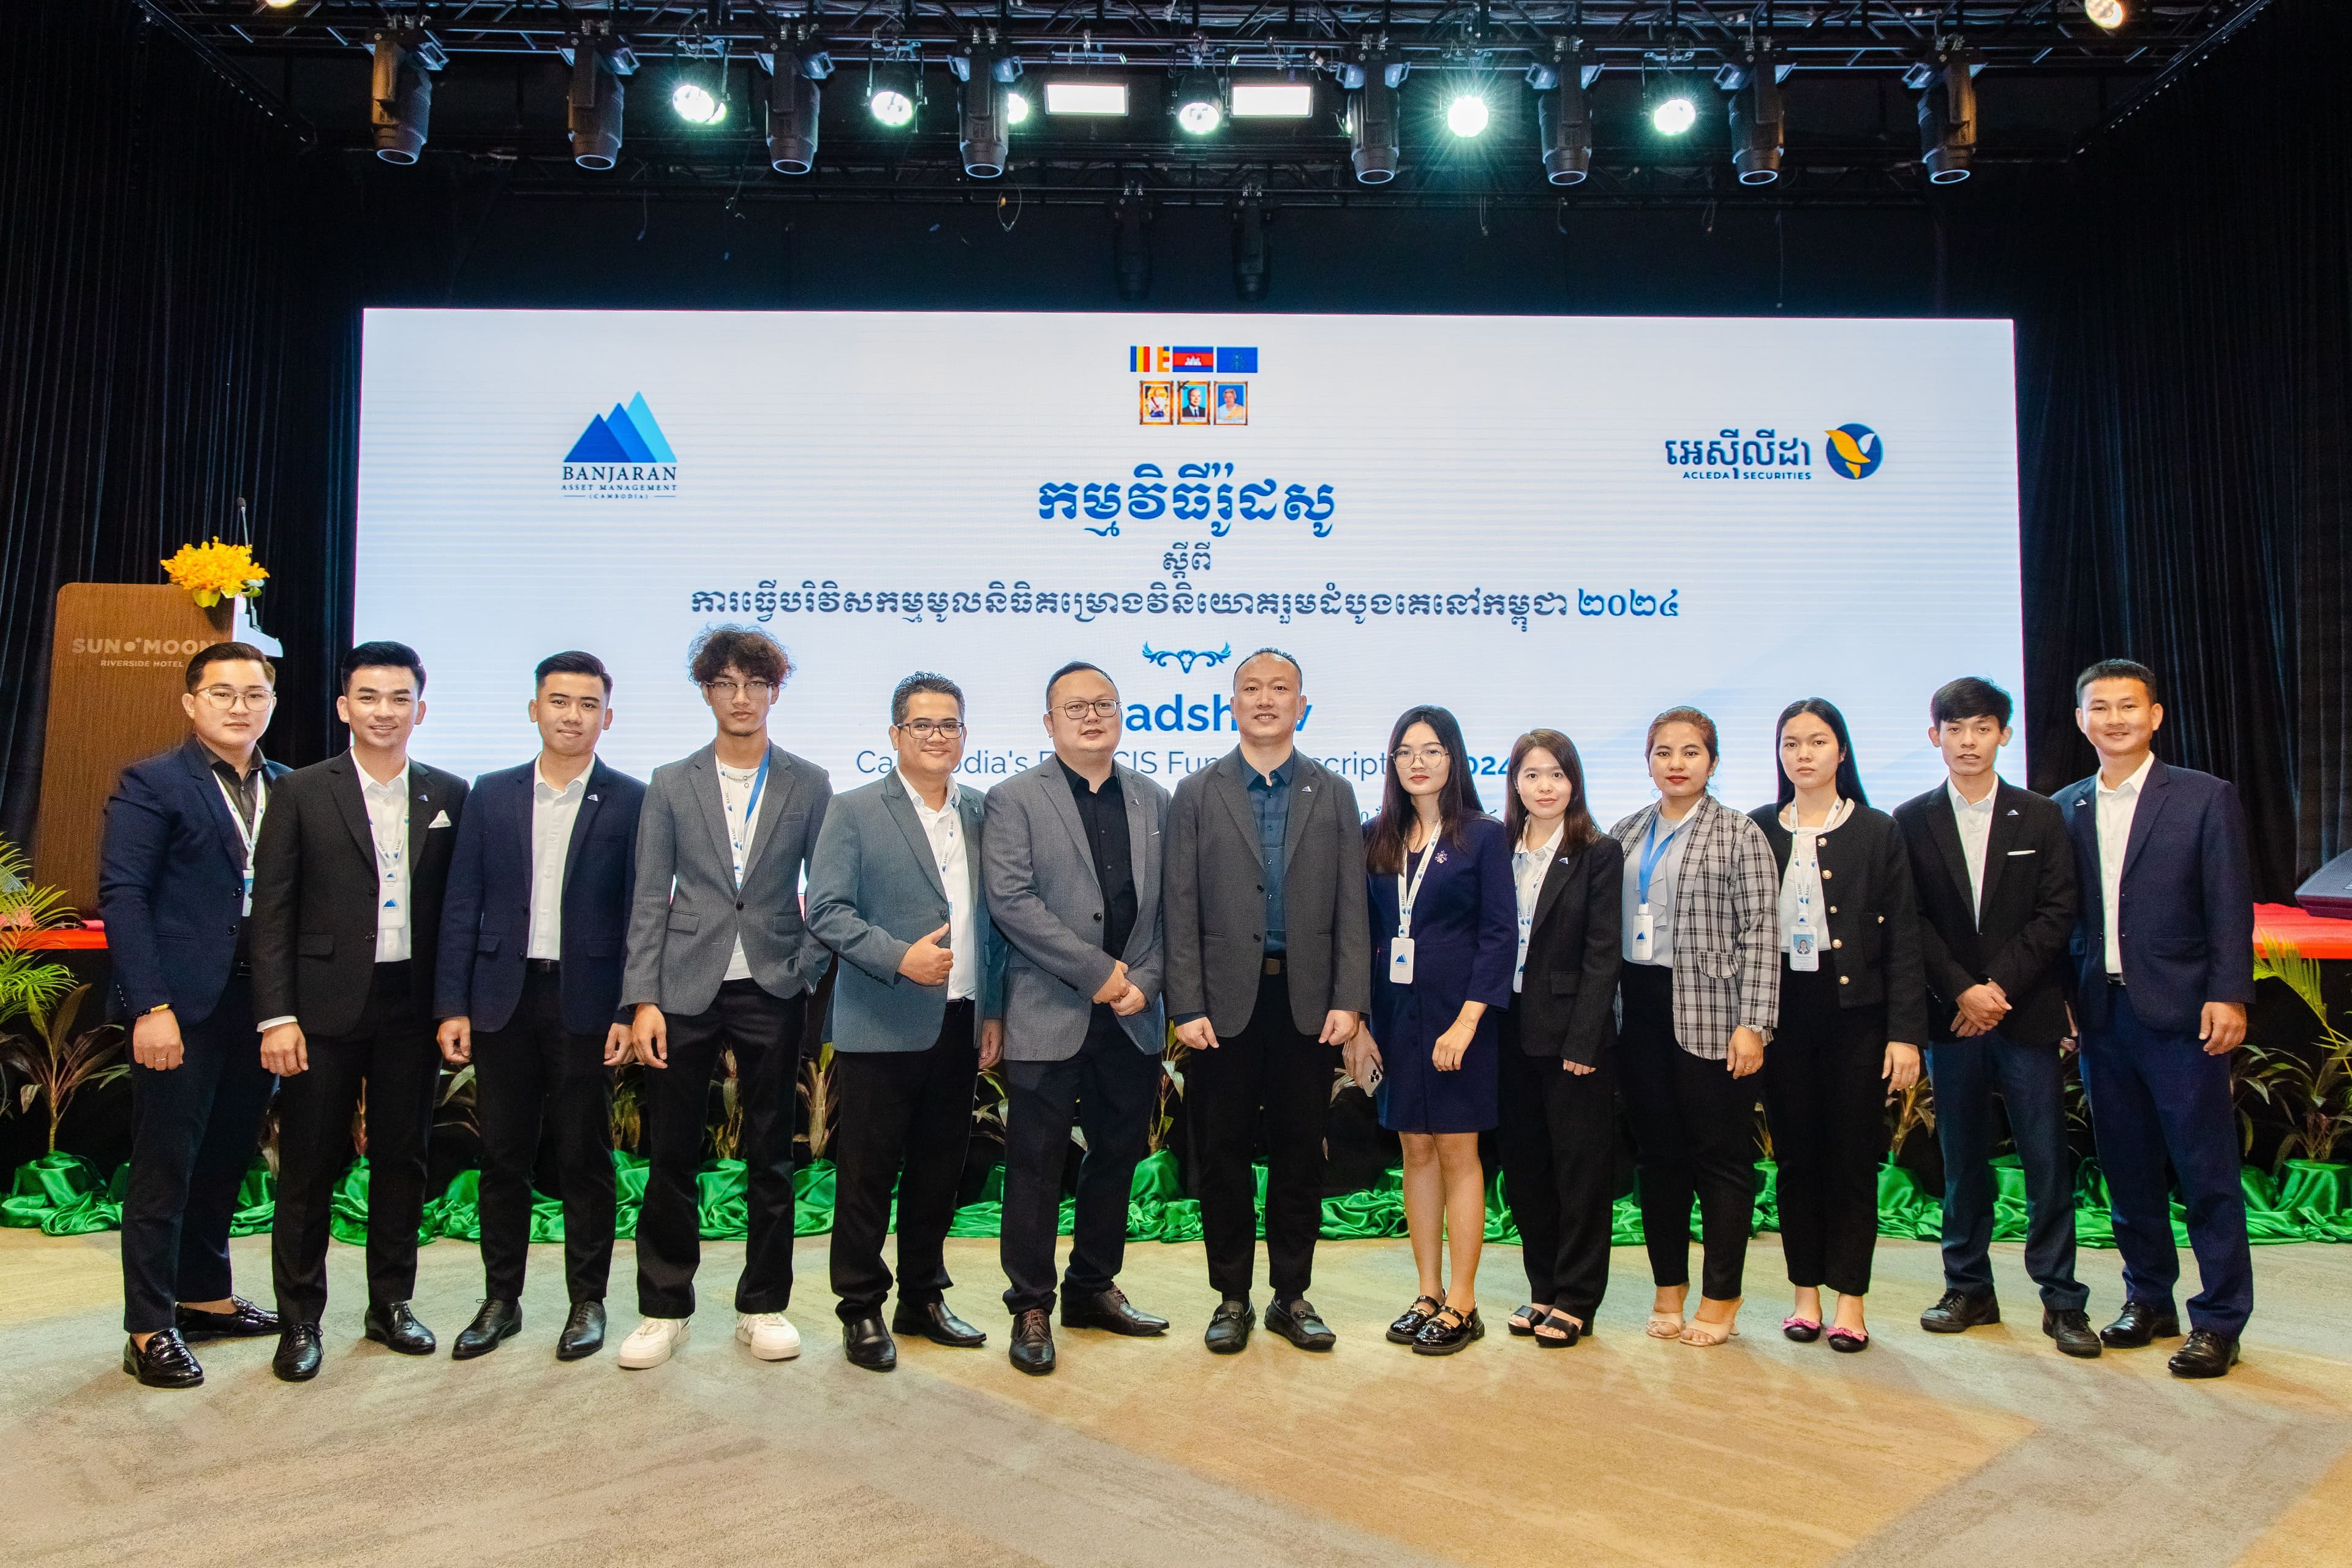
路演活动:2024 年柬埔寨首支集体投资计划基金认购启动

路演活动:2024 年柬埔寨首支集体投资计划基金认购启动

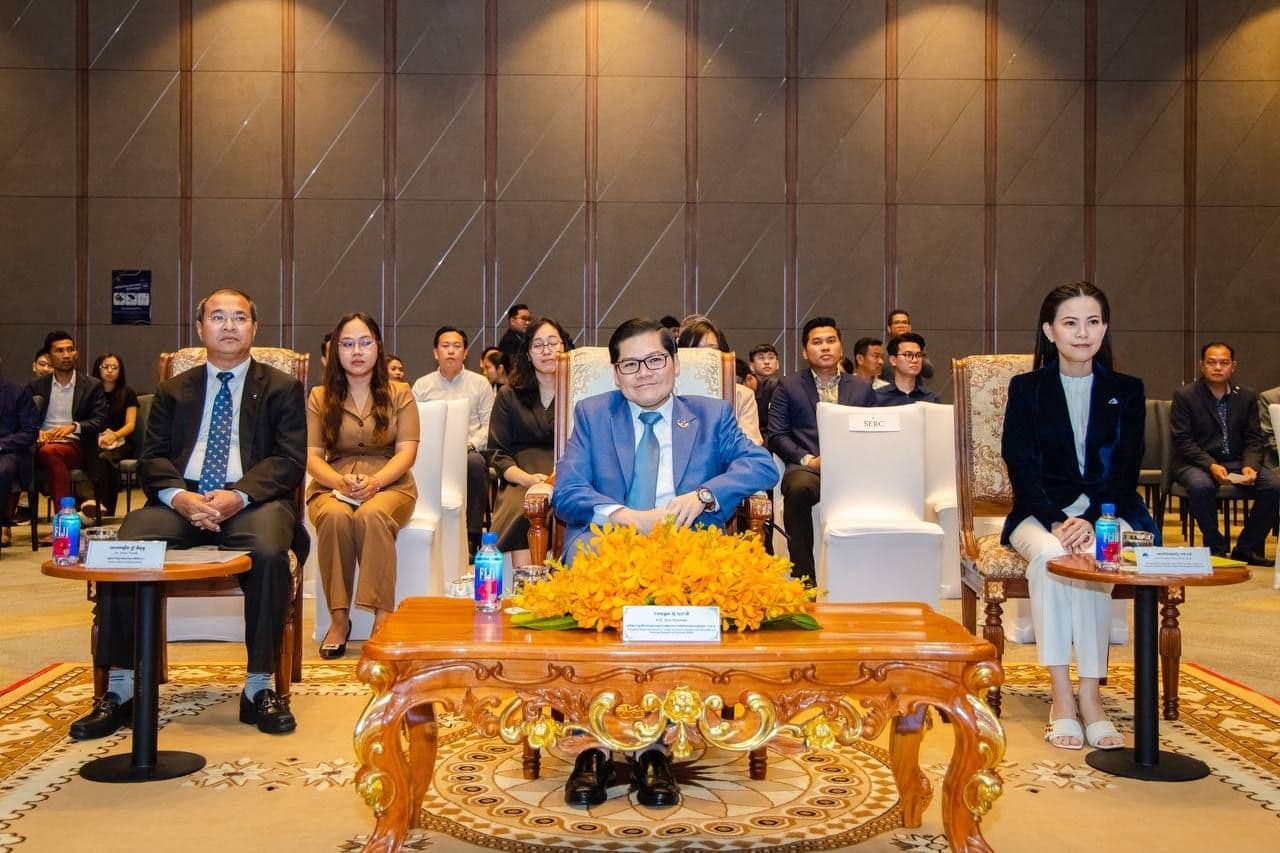
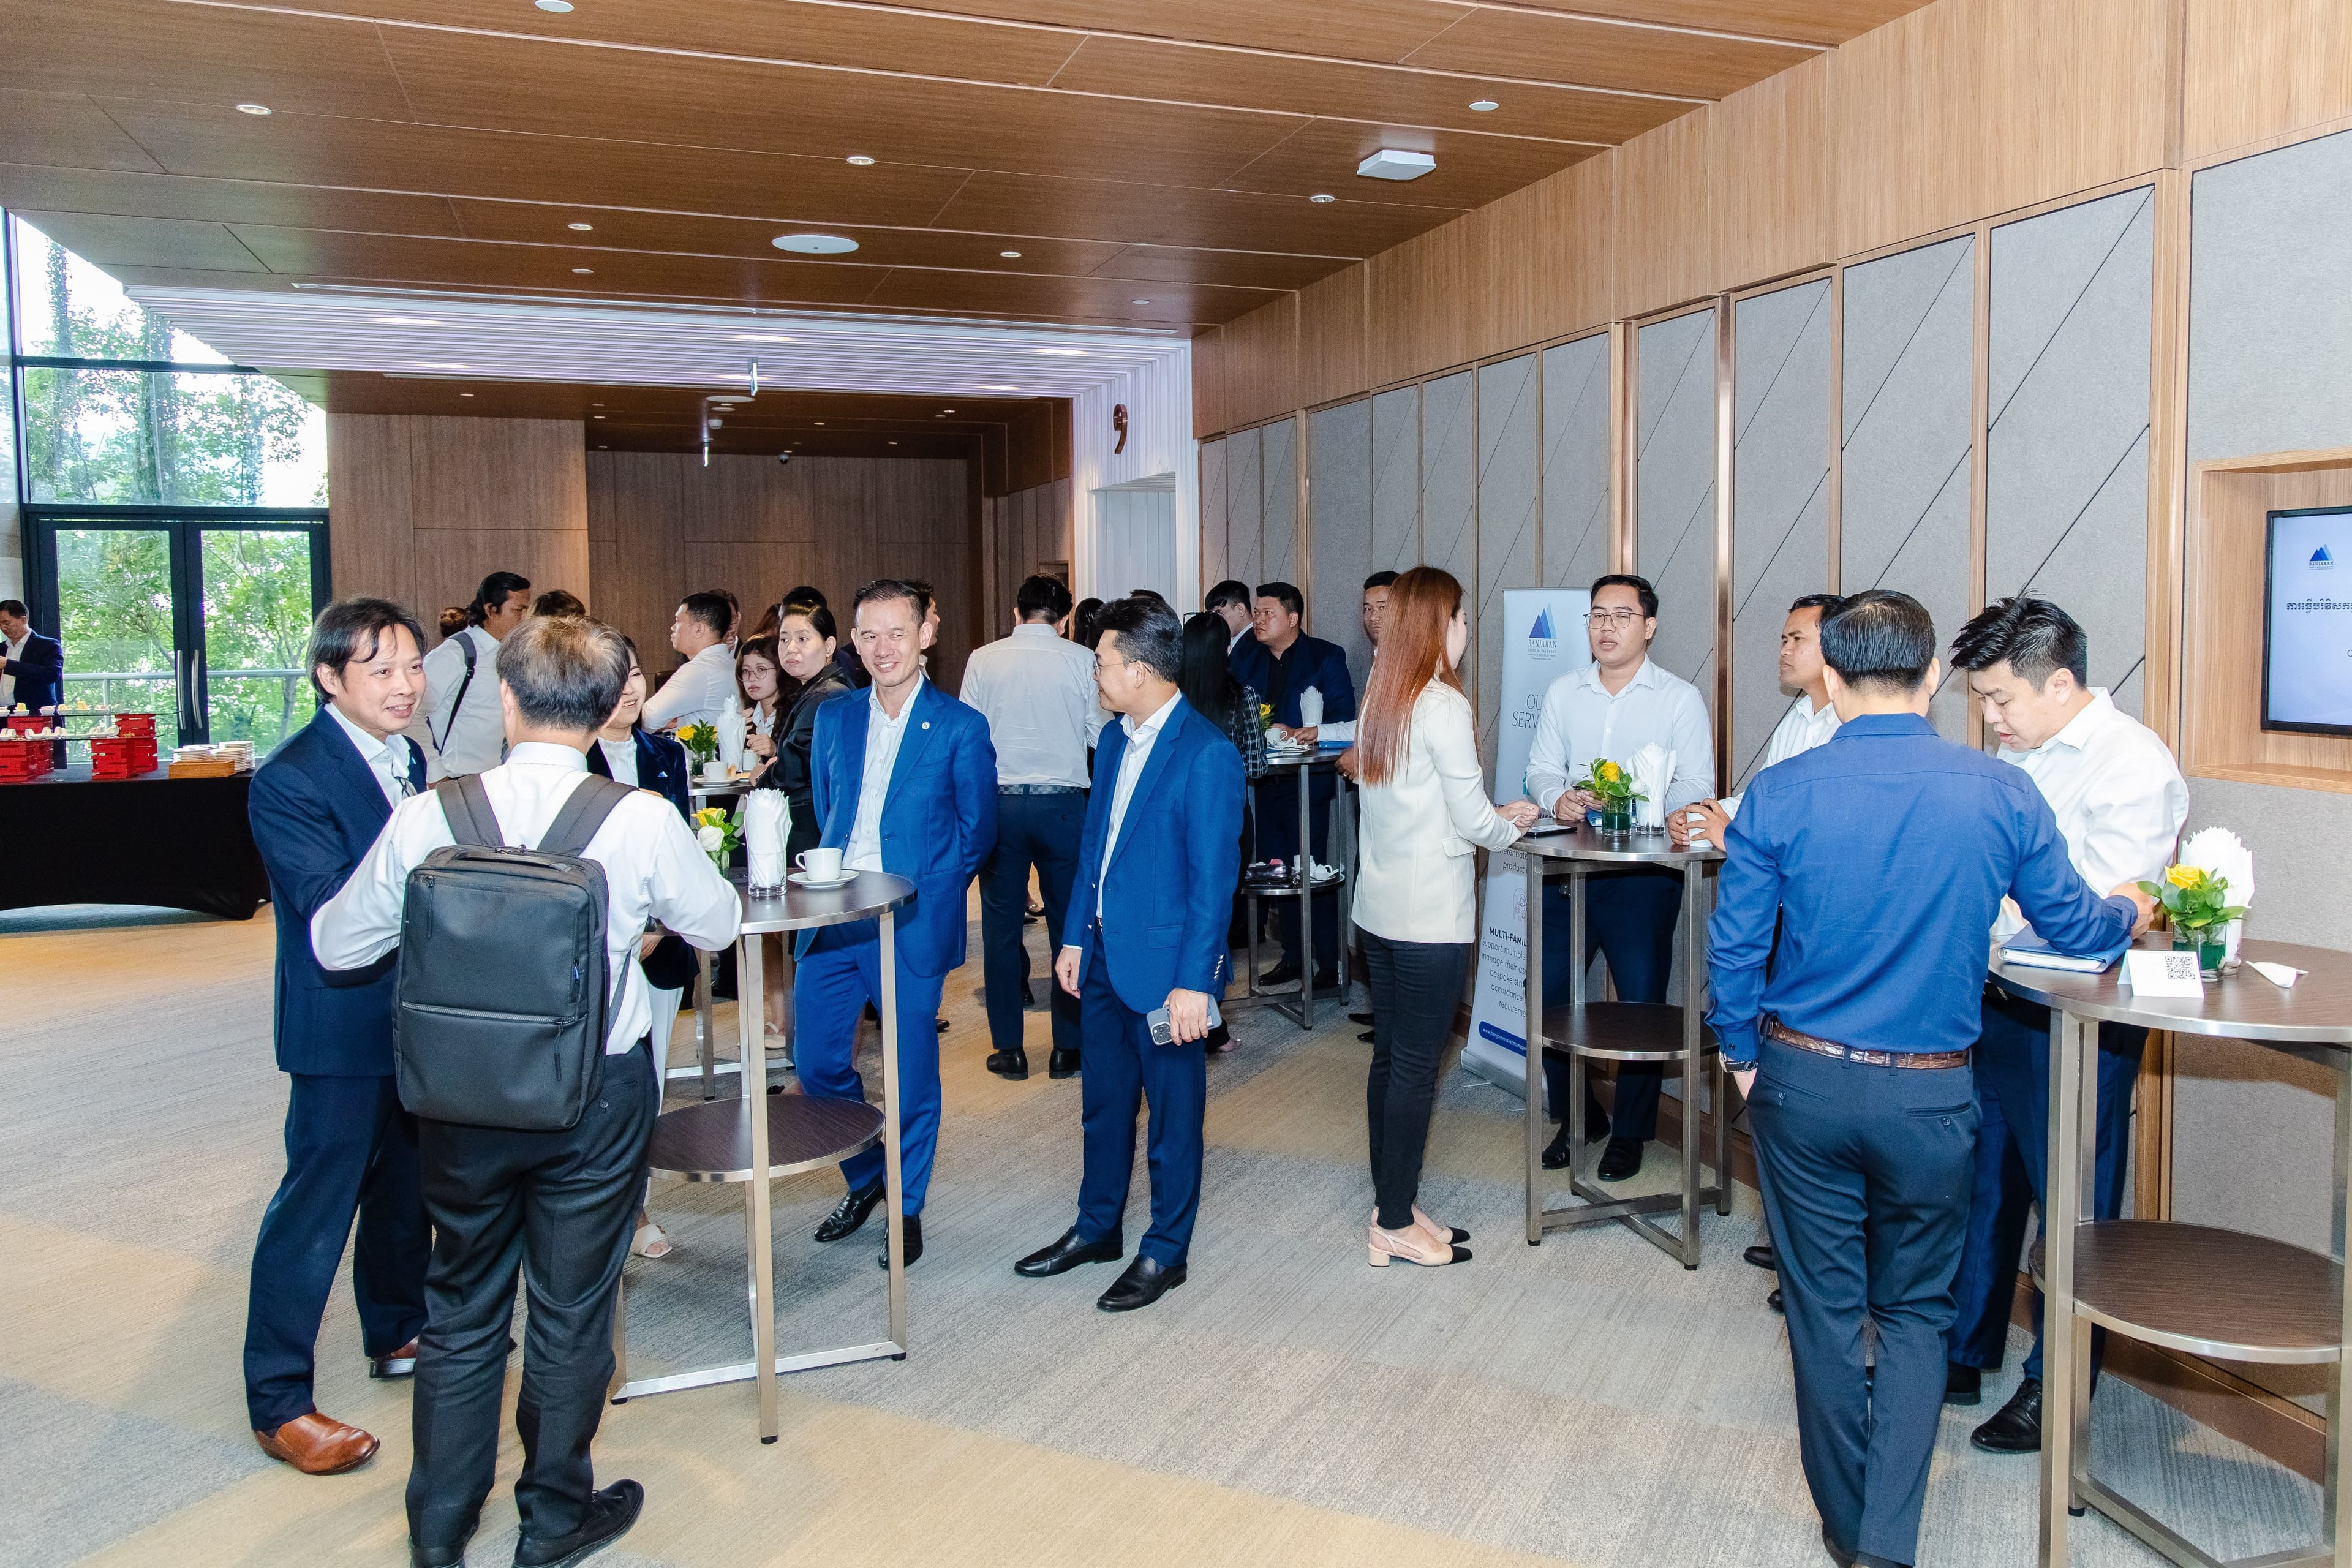
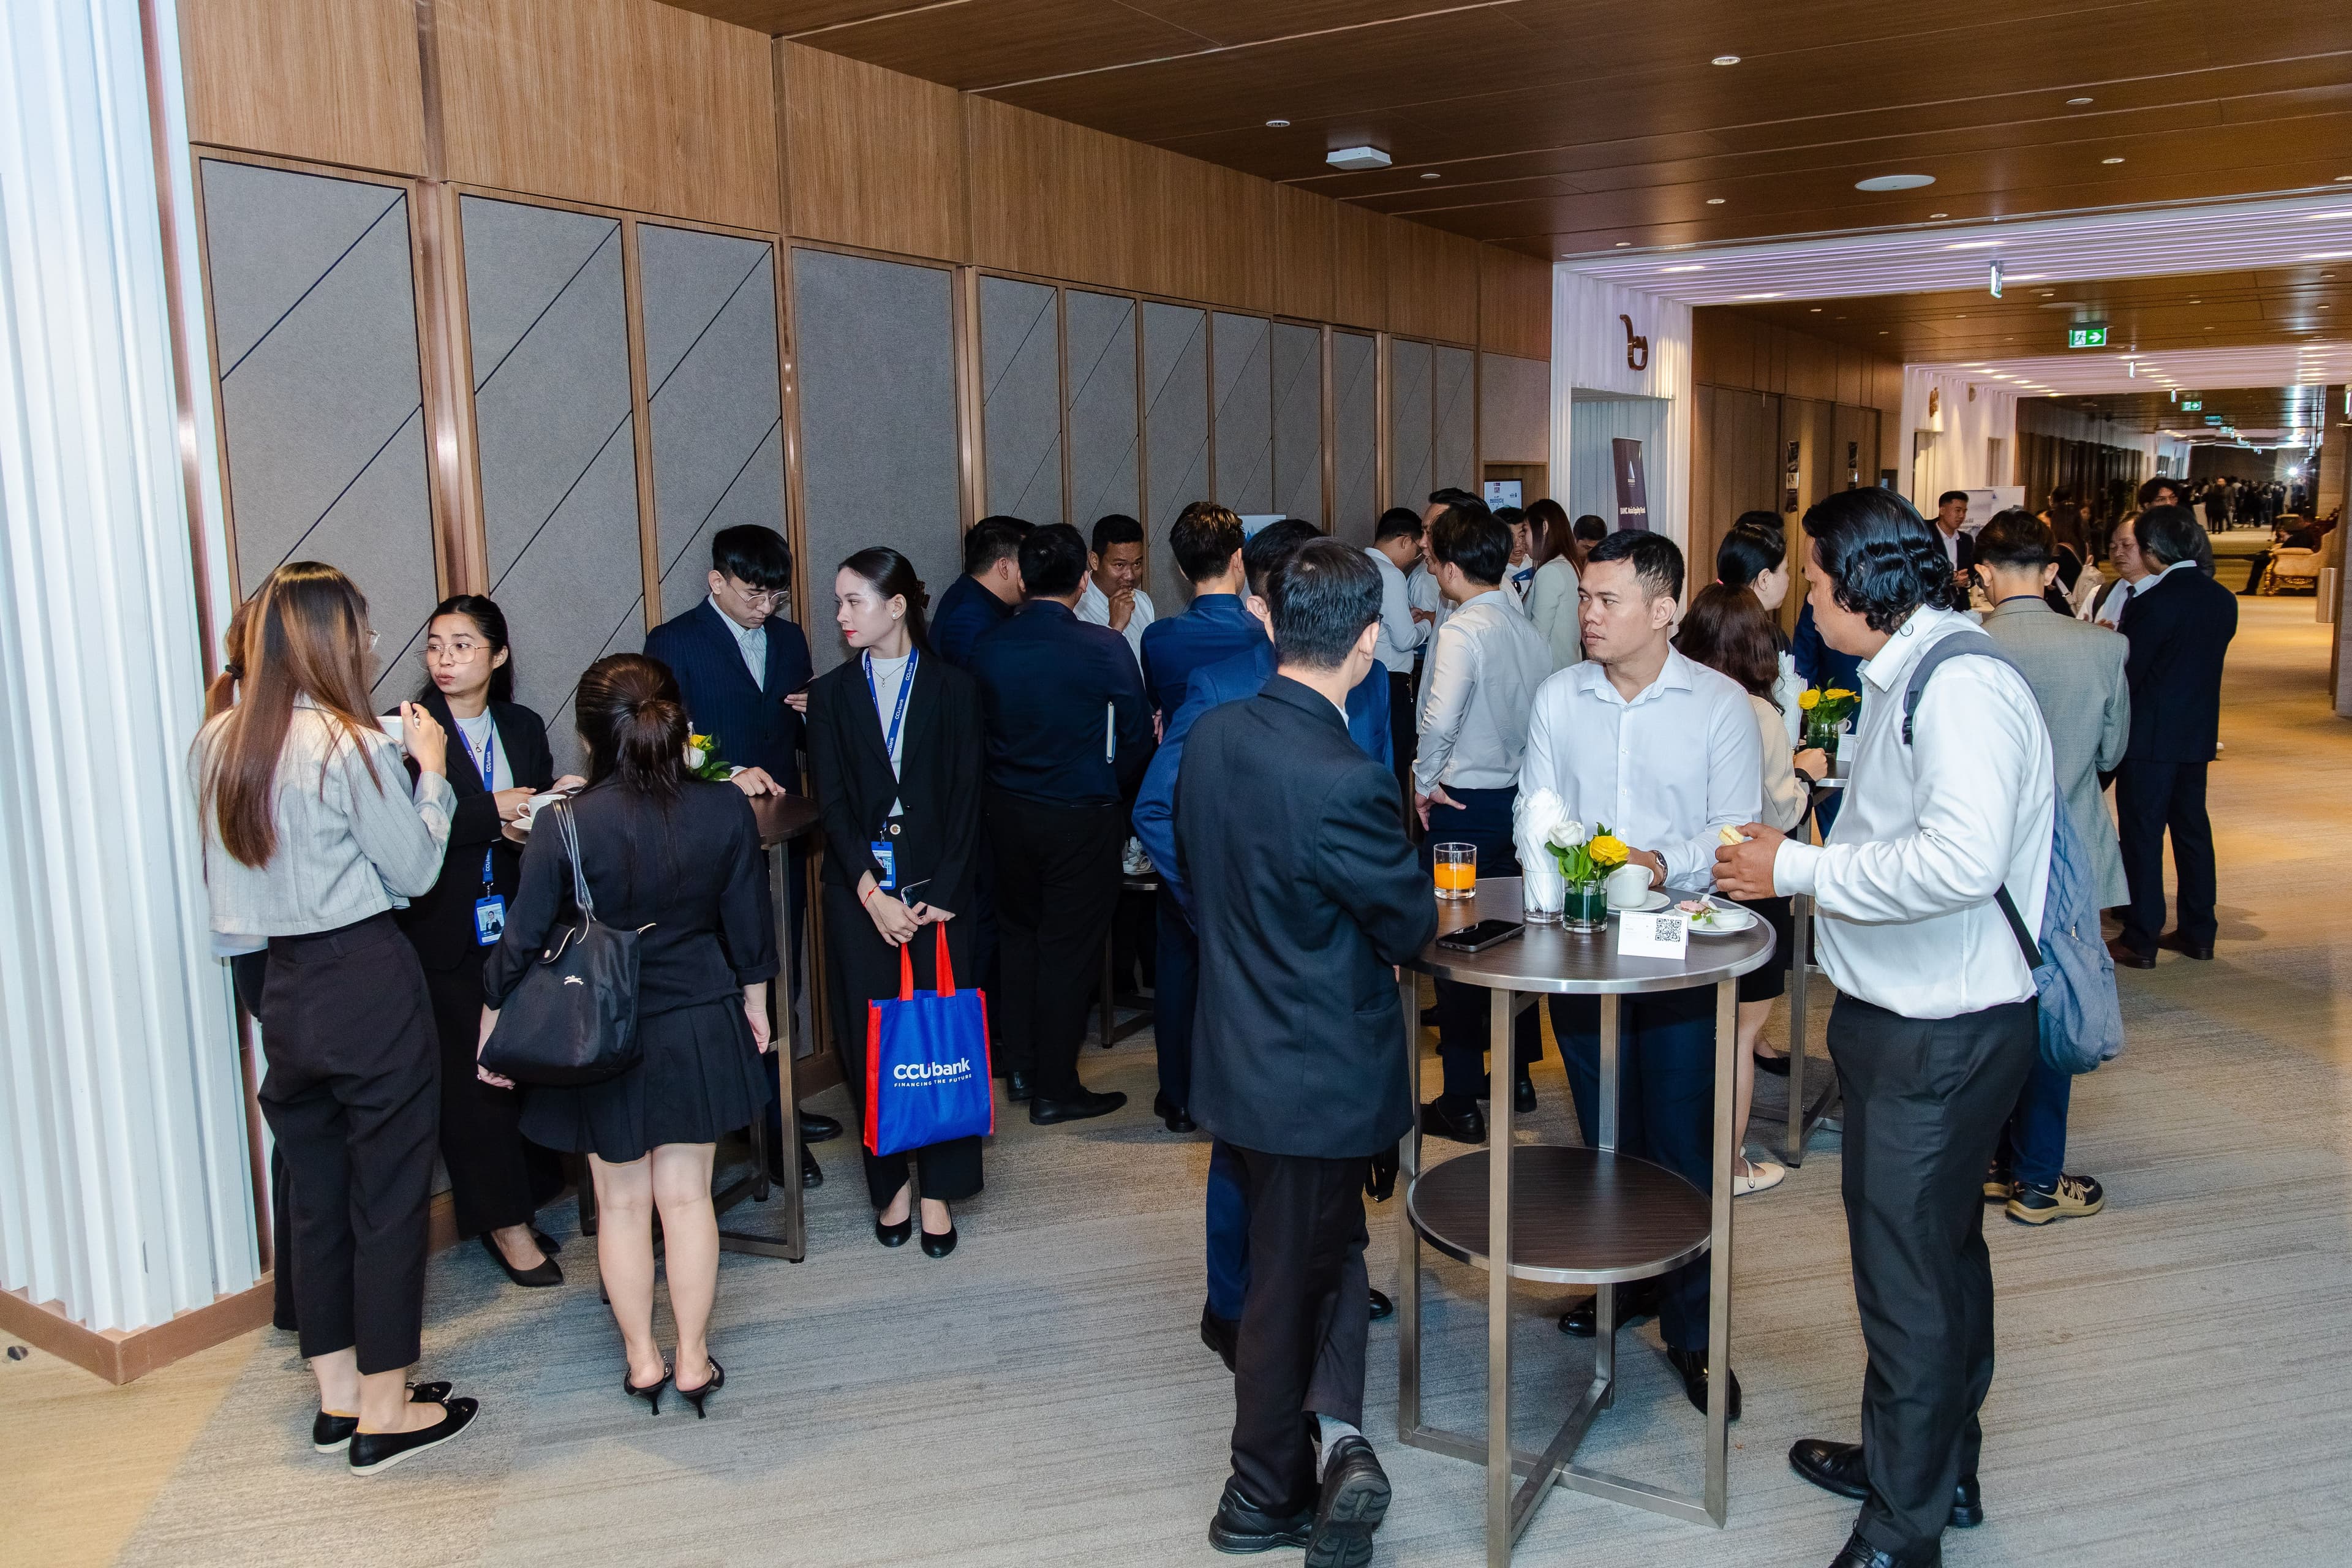
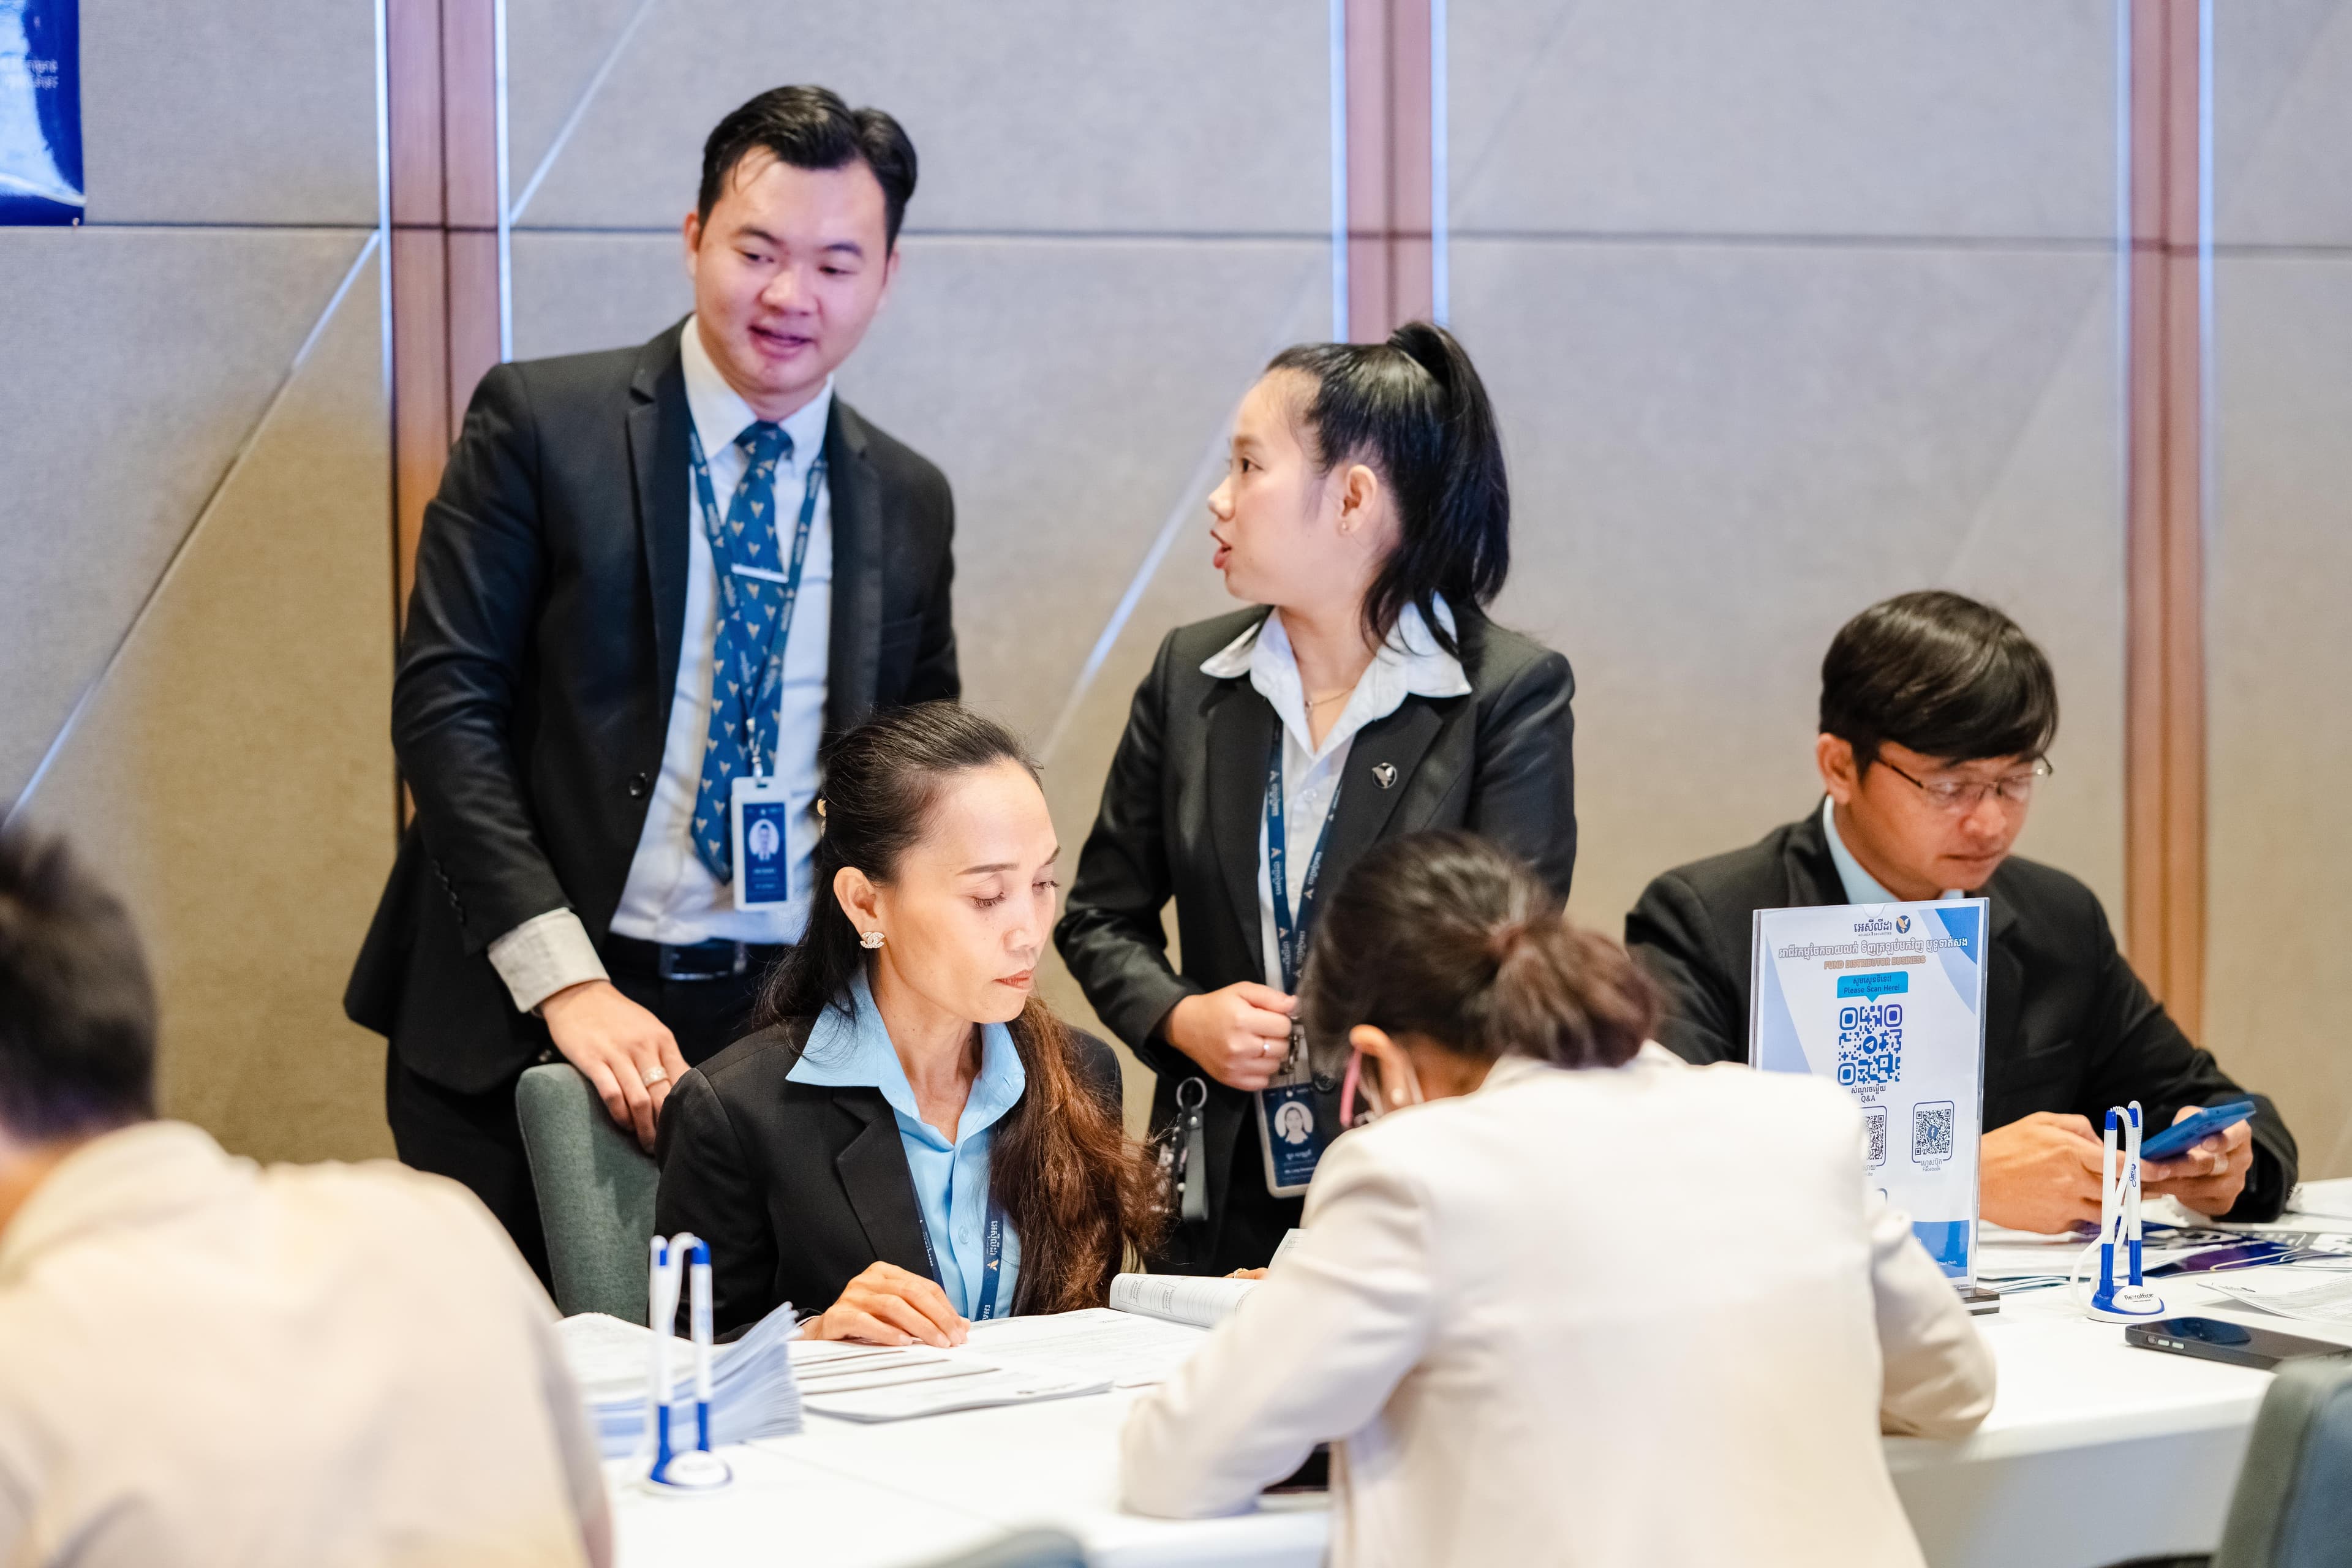
2024 年 10 月 10 日上午,富亚资产管理 (柬埔寨) 有限公司. (BAMC) 与重要合作伙伴爱喜利达证券有限公司联合隆重举办了 “2024 年柬埔寨首支集体投资计划基金认购路演” 活动。本次活动非常荣幸地邀请到柬埔寨证券交易监管机构政府代表兼总干事Sou Socheat阁下亲临指导并担任主礼嘉宾。

此项具有里程碑意义的活动标志着柬埔寨金融行业发展的重要阶段,我们正式向公众推出 富亚亚洲股票基金。活动通过深度讲解和互动讨论,向机构投资者、行业专家以及有意拓展投资机会的个人投资者全面展示了集体投资计划基金的潜力与价值。

路演深入介绍了集体投资计划基金的优势与特色,展示其如何推动更广泛的市场参与,并促进柬埔寨资本市场的持续发展。同时也体现了我们致力于推出创新型金融产品,以满足本地与国际投资者多元化需求的坚定承诺。

此次活动不仅是富亚资产管理有限公司的重要里程碑,也彰显了柬埔寨金融市场的快速扩集体投资计划基金在推动区域经济增长与投资机遇方面日益重要的作用。

我们对所有参与者的支持与出席表示衷心感谢。未来,我们将继续秉持使命,为投资者提供更便捷的投资渠道,并为柬埔寨经济的长远发展贡献力量。

分享

更多洞察

Banjaran AMC Conducts Second CIS Training Session for NSSF Officers and Staff
活动2026年11月6日

Banjaran AMC Conducts Second CIS Training Session for NSSF Officers and Staff

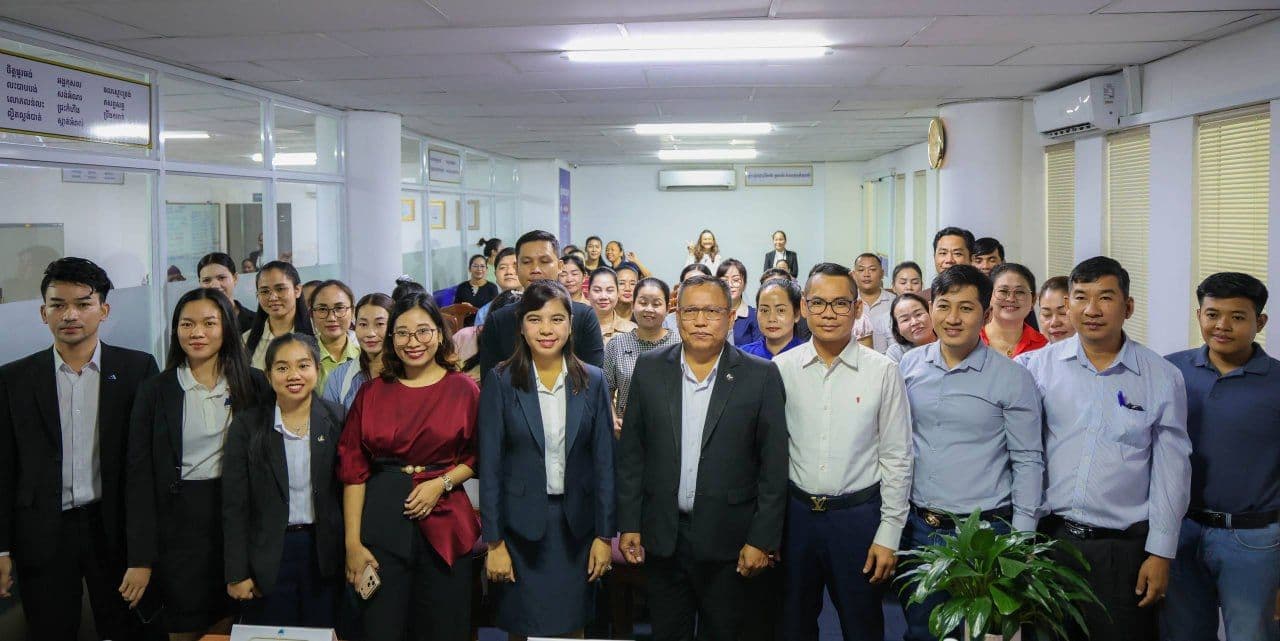
On the afternoon of 6 November 2026, under the direction of the management of Banjaran Asset Management (Cambodia) Plc., Mr. Nhem Sopaul, Head of Corporate Affairs, led a team from the Company in conducting the second training session on “Collective Investment Schemes (CIS)” for the officers and staff of the National Social Security Fund (NSSF) on 6 November 2026. During the training session, Mr. Sok Chantola, Sales & Marketing Deputy Manager; Mr. Taing Hoy, Internal Audit Senior Executive; and Mr. Veasna Monireach, Operation Senior Executive, delivered presentations on “Introduction to Banjaran AMC & CIS Landscape”, “BAMC Asia Equity Fund (BAEF)”, and “Investment Strategy & Key Value of Banjaran AMC”. The presentations provided participants with a better understanding of collective investment schemes, the Fund's investment approach, and the key values of Banjaran AMC. The training was organized to enhance participants' understanding of CIS, introduce the investment opportunities offered through BAEF, and raise awareness of investment funds and the development of Cambodia's capital market. Banjaran Asset Management (Cambodia) Plc. remains committed to promoting financial literacy, sharing investment knowledge, and contributing to the development of Cambodia's capital market through educational initiatives and knowledge-sharing activities.

1 分钟阅读阅读更多
2026 October Market Outlook: Asia Markets – AI Valuation Concerns and Rising Geopolitical Risks
Market Outlook2026年11月2日

2026 October Market Outlook: Asia Markets – AI Valuation Concerns and Rising Geopolitical Risks

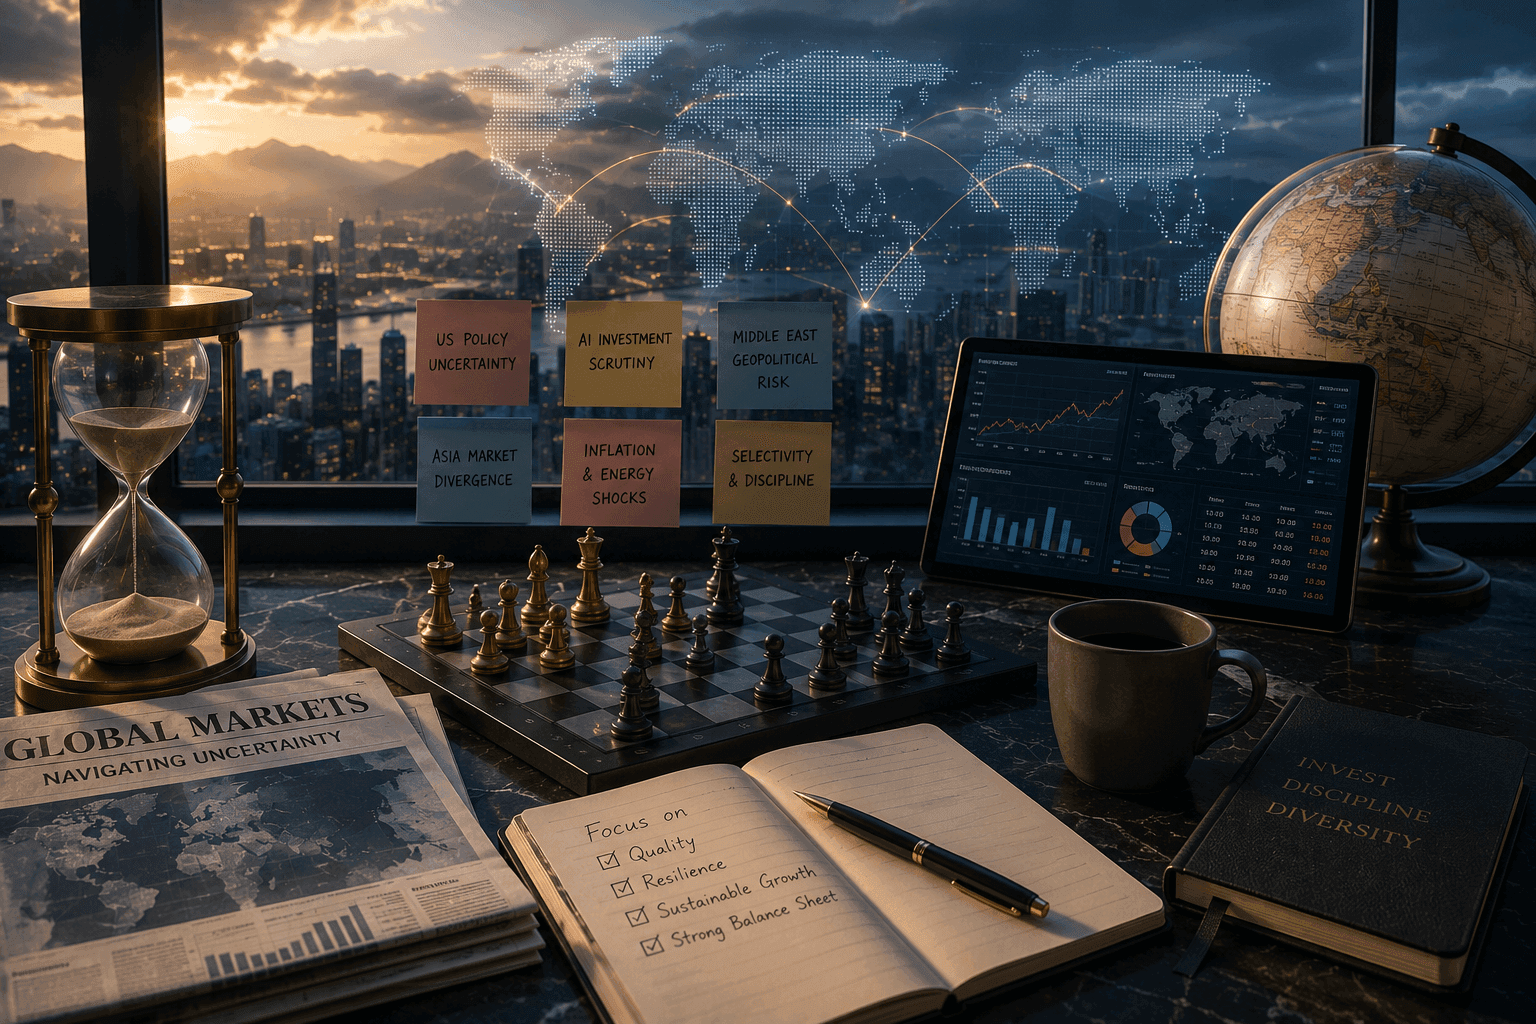
The direction of US monetary policy remains a key source of uncertainty. Minutes from the September Federal Open Market Committee (“FOMC”) meeting indicated that a further rate increase before year-end remains possible. However, Chair Warsh has declined to commit to a path, identifying the October and December meetings as the key decision points. Ahead of the next FOMC meeting on 27–28 October, the International Monetary Fund has cautioned that uncertainty over US monetary policy could keep Asian financial markets volatile. The recent sell-off has also brought the financing of AI investment into sharper focus. Chair Warsh noted that large technology companies raising funds in the bond market are adding to competition for capital. In our view, investors are likely to place greater scrutiny on the returns these companies generate from their AI spending. Developments in the Middle East remain a key swing factor for oil prices and inflation. Before the conflict began in late February, the Strait of Hormuz carried around one-fifth of global oil supply. Within Asia, the most significant development has been in Indonesia. On 15 October, index provider MSCI Inc. launched a consultation on reclassifying Indonesia from Emerging Market to Standalone Market status, citing insufficient progress on market transparency, concentrated shareholdings and weak enforcement. This contrasts with FTSE Russell, which reaffirmed Indonesia’s emerging market status. The Jakarta Composite Index fell 8.0% following the announcement, which triggered a trading halt. MSCI has also frozen certain index changes for Indonesian securities, including new additions, until further notice. The announcement adds to a difficult year for Indonesia, whose stock market has fallen more than 30% to become the world’s worst performing this year, according to Bloomberg, while Moody’s and Fitch have both revised the sovereign rating outlook to negative. With the consultation open until 30 April 2027, analysts expect foreign outflows to continue. In North Asia, the October sell-off highlighted how exposed South Korea and Taiwan have become to swings in AI sentiment after very strong gains over the past year. The KOSPI and TAIEX rose 86.7% and 80.6% respectively over the past year, and the TAIEX’s price-to-earnings ratio has expanded to 27.9 times from 23.1 times. Singapore again demonstrated its defensive qualities, with the Straits Times Index declining only 0.5% on 15 October, a far smaller fall than its North Asian peers. Overall, investor sentiment has shifted from chasing AI momentum towards greater caution on valuations, funding costs, and geopolitical risk. In this environment, we remain focused on businesses with strong balance sheets, sustainable earnings and pricing power, which we believe are better positioned to navigate persistent inflation and energy price shocks. We continue to apply a disciplined, bottom-up approach to stock selection and to maintain diversification across geographies and themes.

3 分钟阅读阅读更多
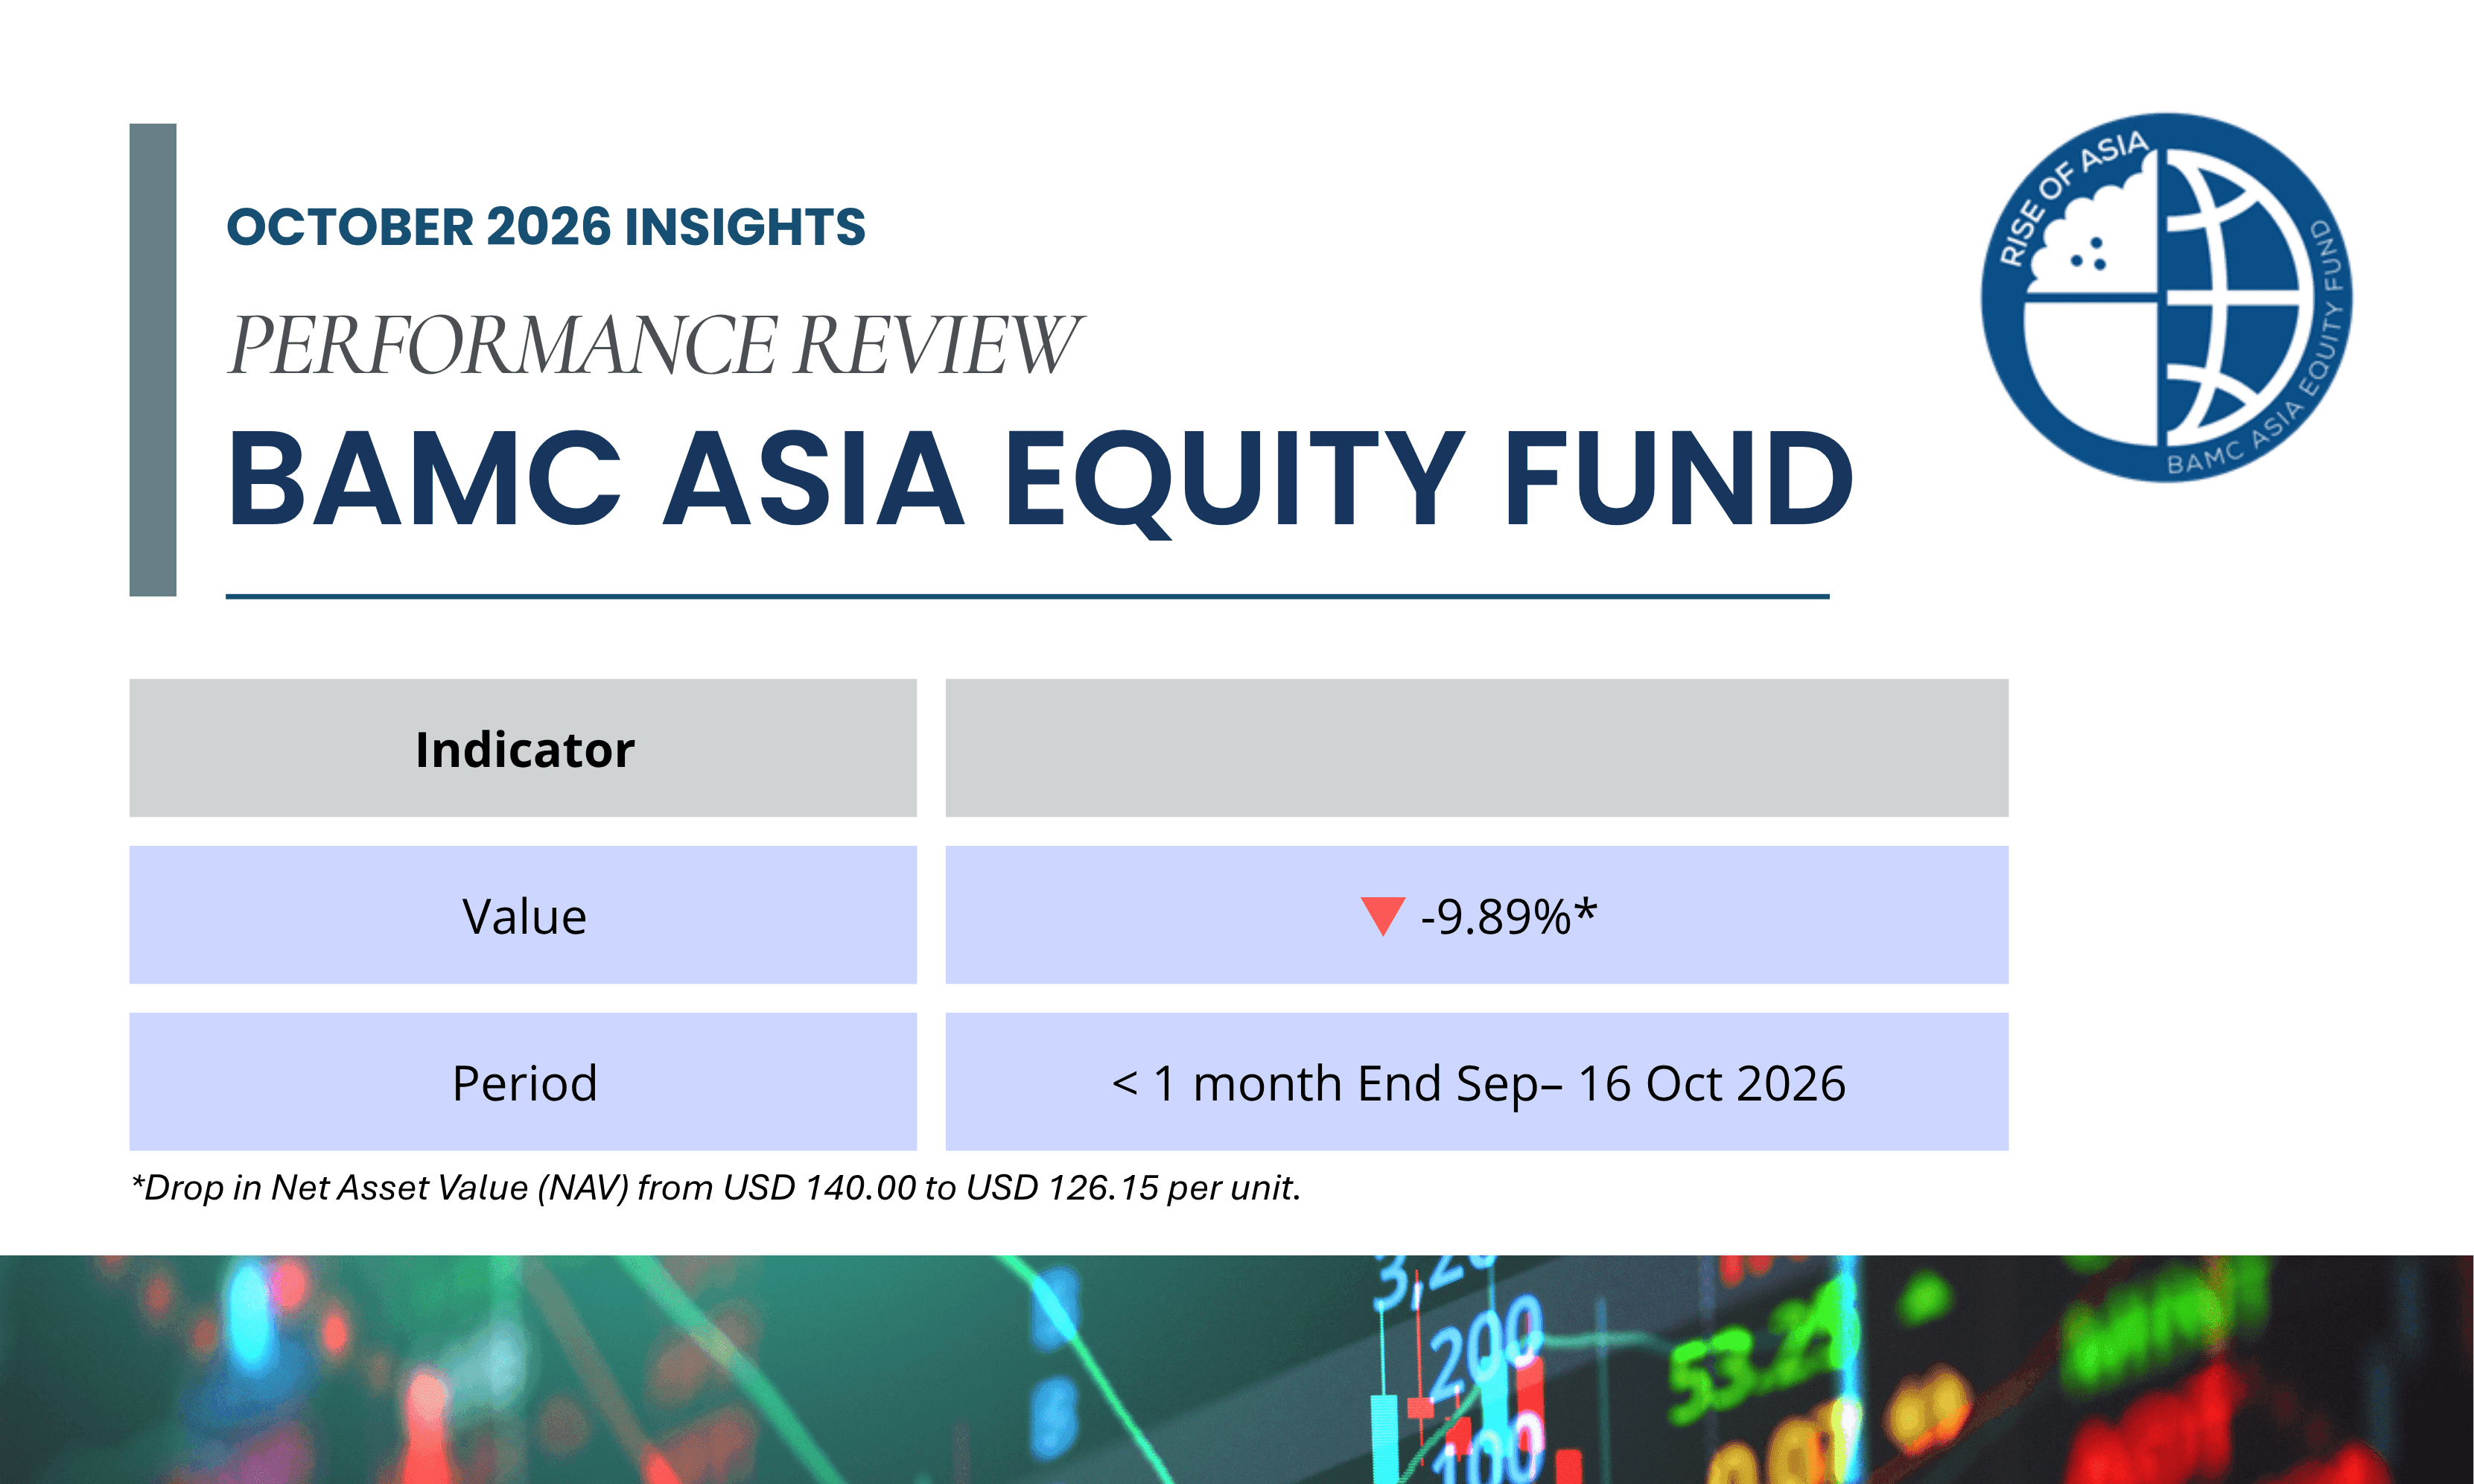
BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026
公告2026年10月23日

BAMC Asia Equity Fund (BAEF) Performance as of 16 October 2026

Markets in October Since end September, global equities have faced pressure from higher borrowing costs and growing scrutiny of the returns from AI related spending. Stronger than expected US inflation reinforced expectations of further Federal Reserve tightening, weighing particularly on technology and semiconductor valuations. Elevated oil prices added further pressure on inflation concerns. Overall, technology-heavy Asian markets bore a greater share of the selling in October’s global tech weakness. Our exposure to Asian equities reflects our focus on the region’s long-term growth opportunities. Short-term volatility is an inherent risk of this approach, but our investment decisions remain anchored in companies’ fundamentals and their potential to generate sustainable returns over time. Portfolio underperformance Against this backdrop, BAEF’s main drag was its concentration in Korean and Taiwanese equities and semiconductor related holdings, which together accounted for 32.3% of the portfolio and approximately 4% of the calculated drag. The Korea ETF and Samsung alone contributed roughly 2%. Korea was particularly affected by the unwinding of AI-related positions. On 15 October, its benchmark equity index fell approximately 8%. Samsung’s weakness came despite guidance for a substantial increase in third-quarter operating profit, suggesting that concerns over valuations, financing conditions and competition outweighed the near-term earnings improvement. The drop was compounded by sharp falls in several Singapore small caps and financials. Addvalue fell 22.9%, UOB Kay-Hian 25.2%, OCBC 10.3%. OCBC faced a specific catalyst when Citi downgraded the stock from “neutral” to “sell”, citing risks to third-quarter earnings, pressure on net interest margins from higher deposit costs, and the potential normalisation of exceptionally strong first-half wealth-related income. Addvalue’s share price weakness is due to profit-taking after a strong run. Singapore’s semiconductor-related suppliers to chipmakers fell harder than the larger chipmakers; Frencken fell 14.9%, UMS 14.8% and AEM 9.9%. Together, these holdings constituted approximately 14% of the portfolio and implied another 2.3% of drag. Like the global technology sell-off, broader concerns over the AI investment cycle were weighing on sentiment beyond individual companies’ reported performance. There were few meaningful offsets in the portfolio as gains elsewhere were insufficient to counter the losses. Why we still hold these stocks Despite the recent weakness, we retain these holdings because the underlying earnings drivers remain relevant to our investment horizon. The sell-off has weakened share prices more than the underlying medium- to long-term investment case. In semiconductors, the correction has coincided with continued growth in demand for AI compute. TSMC’s latest results and guidance pointed to sustained demand for advanced chips, while Samsung’s earnings guidance reflected stronger memory sales and pricing. These developments support maintaining exposure to the sector, although we recognise that strong operating performance does not eliminate valuation risk or the possibility of further share price volatility. Our Singapore semiconductor holdings provide exposure to different parts of this investment cycle. UMS benefits from equipment demand and increasing exposure to advanced packaging, AEM offers participation in increasingly complex semiconductor testing, and Frencken provides a more diversified manufacturing exposure. The rationale for retaining these positions rests on their prospective earnings as customers invest in additional capacity and advanced chip architectures, rather than an expectation that all semiconductor-related stocks will recover together. For the financial holdings, recent operating results provide a basis for distinguishing share price weakness from deterioration in the businesses. OCBC’s wealth-management and other non-interest income have helped offset pressure on lending margins, while its capital position continues to support business growth and distributions. UOB Kay Hian reported substantially higher first-half earnings, supported by stronger trading activity, commission income and interest income. We retain exposure to these earnings streams, while recognising that wealth related revenue and brokerage activity are market sensitive and that recent growth rates may not persist. We retain exposure to Addvalue to the long-term growth in satellite connectivity and space infrastructure. Recent share-price weakness appears to reflect, in part, profit-taking following a strong rally, while continued orders support the underlying growth outlook. In september, Addvalue announced US$15 million of new orders across its space connectivity and advanced digital radio business, bringing its order book to US$20.2 million. Converting these orders into earnings and cash flow remains central to our investment case. Overall, we remain selective and view the decline as a potential opportunity to top up positions rather as a reason to hold every position unchanged. Continued ownership must be supported by company fundamentals, an acceptable valuation, and grounded in earnings growth. Moving forward Looking ahead, we intend to increase exposure to quality large-cap and blue-chip companies to strengthen portfolio resilience amid continued volatility. We will prioritise businesses with sound balance sheets, sustainable earnings and cash flows, and durable competitive advantages. Further market weakness could provide opportunities to build positions at more attractive entry prices, while maintaining a disciplined approach to valuation. Disclaimer : This Document is issued for information and investor awareness purposes only to explain the factors contributing to the changes in BAEF’s NAV. It does not constitute investment advice, an investment recommendation, an offer, or a solicitation to buy, sell, or hold units of BAEF. The information provided herein should not be relied upon as the sole basis for any investment decision and does not guarantee future performance. Investors should refer to the Fund’s official offering documents and disclosures and carefully assess their own investment objectives and risk tolerance before making any investment decision.

4 分钟阅读阅读更多
2026 September Market Outlook: Navigating Market Divergence
Market Outlook2026年10月1日

2026 September Market Outlook: Navigating Market Divergence

The Fed maintained a restrictive, data-dependent stance through August and subsequently raised the federal funds target range by 25 basis points to 3.75-4.00% citing persistent inflationary pressures. Updated projections point to the possibility of one further increase in 2026. Elevated long-dated US Treasury yields continue to present a valuation risk particularly for growth, technology and AI-related companies, whose expected cash flows lie further in the future. At the same time, continued corporate earnings delivery and investments in strategic technologies along the tech supply chain have so far helped the global economy absorb tighter financial conditions. Strong earnings guidance from major global technology companies supports the view that investment in data centres, advanced chips and supporting infrastructure remains resilient. Within Asia, performance has diverged meaningfully across countries. Singapore remains the region’s defensible market, with strong banking profitability and wealth management inflows attracting investor interest amid global uncertainty. Taiwan and South Korea’s technology sector continues to be major beneficiaries of surging AI-related demand. On the other hand, confidence towards China’s and Indonesia’s growth outlook remains fragile. China’s slow economic momentum is a result of a weak property market and slow domestic consumption, while Indonesia’s commodity price normalisation and concerns over capital outflows weigh on sentiment. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.

1 分钟阅读阅读更多
Banjaran AMC and ACLEDA Securities Host Golden Securities Investment Workshop in Chbar Ampov
路演2026年9月12日

Banjaran AMC and ACLEDA Securities Host Golden Securities Investment Workshop in Chbar Ampov

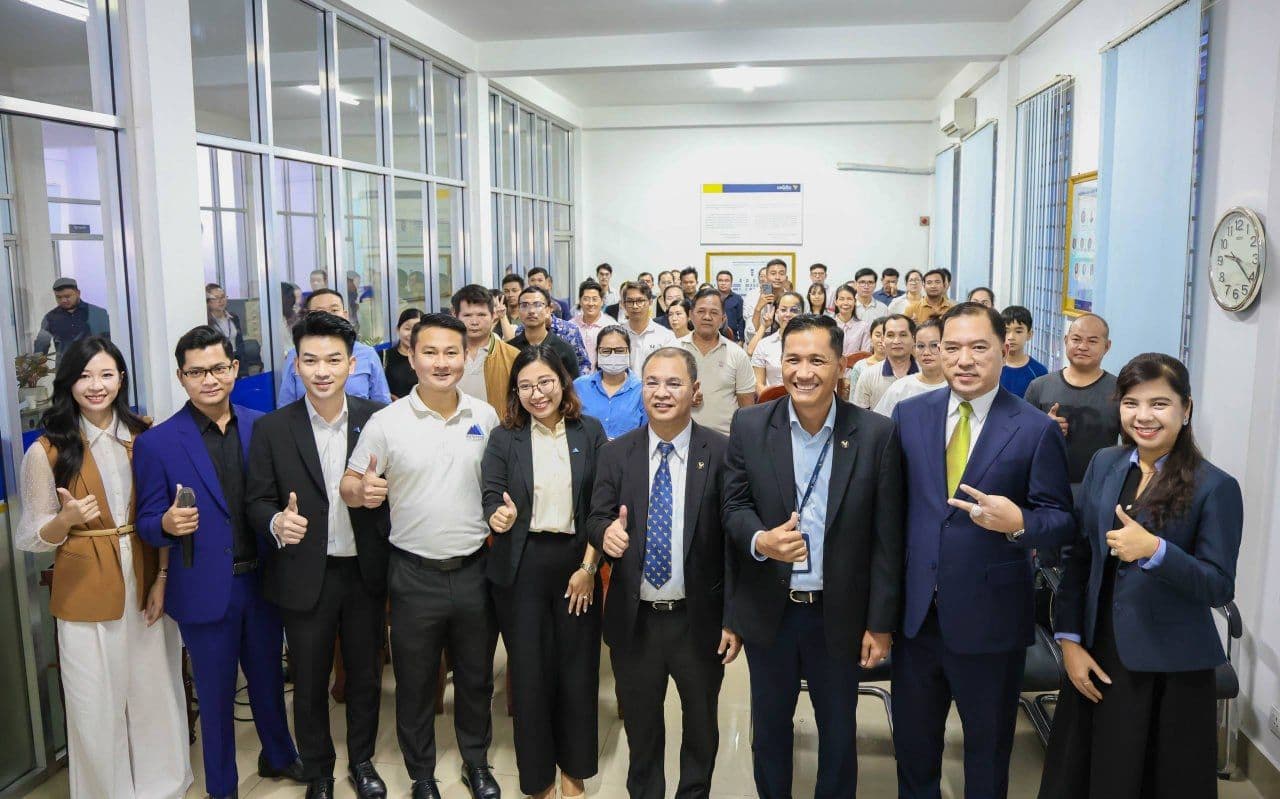
Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and the ACLEDA Bank Plc. Local Branch (Khan Chbar Ampov – Sangkat Chbar Ampov Ti Muoy), successfully hosted the Workshop on “Golden Securities Investment Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch (Khan Chbar Ampov – Sangkat Chbar Ampov Ti Muoy) on the morning of 12 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial

1 分钟阅读阅读更多
Banjaran AMC Brings BAEF Investment Opportunities to Investors in Phnom Penh Through 3rd Round Roadshow
路演2026年9月5日

Banjaran AMC Brings BAEF Investment Opportunities to Investors in Phnom Penh Through 3rd Round Roadshow

Banjaran Asset Management (Cambodia) Plc. in collaboration with ACLEDA Securities Plc. and ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01), successfully hosted the Workshop on “Golden Securities Investment by Opportunities” as part of the 3rd Round Roadshow. The workshop was held at the meeting hall of ACLEDA Bank Plc. Local Branch, (Khan Mean Chey, Sangkat Boeng Tumpun 01) on the morning of 05 September 2026. The workshop aimed to enhance public understanding of capital market investments and the BAMC Asia Equity Fund (BAEF), a Collective Investment Scheme (CIS). We sincerely appreciate the support of our partners and the active participation of all attendees. Special thanks to Mr. Sok Chantola, Deputy Sales & Marketing Manager of Banjaran Asset Management (Cambodia) Plc. on the topic “BAMC Asia Equity Fund (BAEF)”. We look forward to welcoming you to our upcoming events. #BanjaranAMC #BAEF #CIS #Investment #Strategic #Financial

1 分钟阅读阅读更多