

洞察力
获取最新资讯、专家分析及市场展望,抢先洞察行业动态。
新闻中心
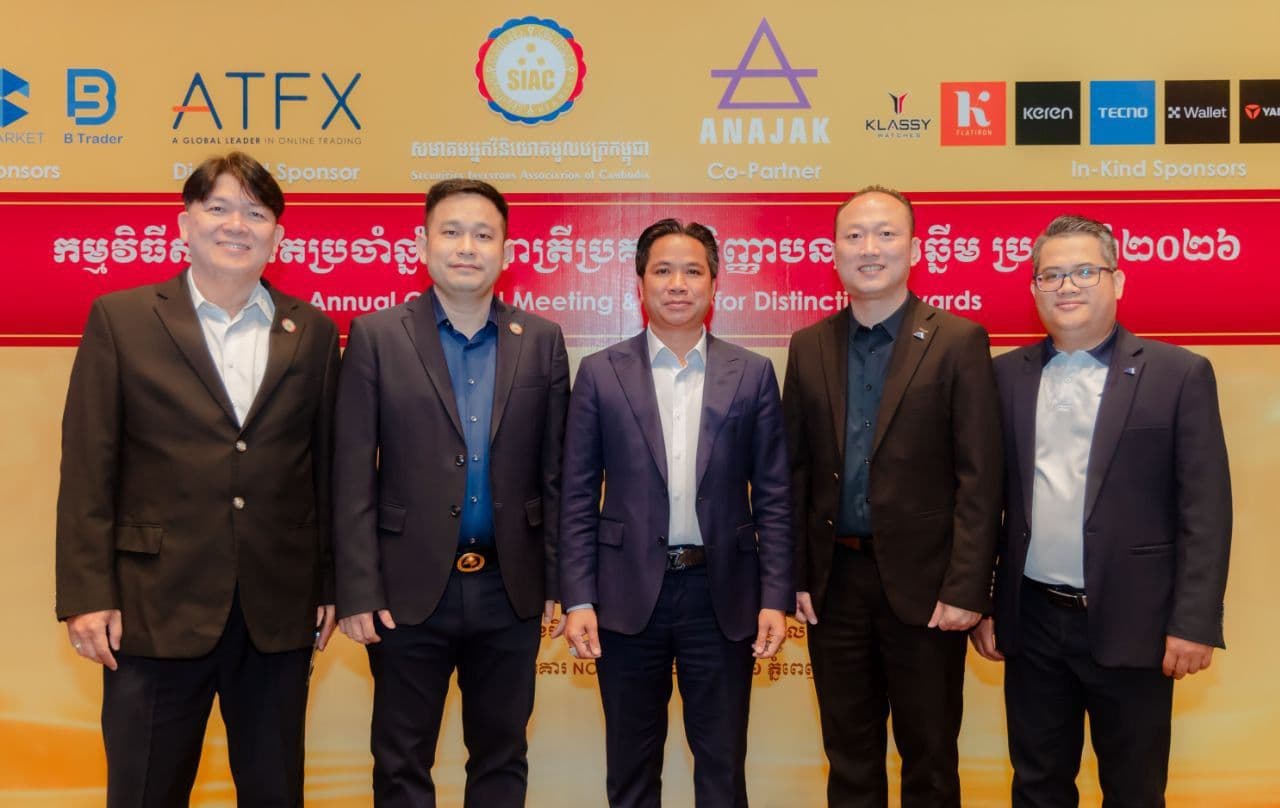
Annual General Meeting and Gala for Distinction Awards of Securities Investors Association of Cambodia (SIAC)
On 6 March 2026, Mr. Eric Loo, Chief Executive Officer, and Mr. Nhem Sopaul, Corporate Manager of Banjaran Asset Management (Cambodia) Plc., had the honor of attending the “Annual General Meeting and Gala for Distinction Awards of Securities Investors Association of Cambodia (SIAC),” held at the NOVOTEL Hotel. The event was presided over by H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC) and Honorary President of SIAC. The event was also attended by Management and Senior Officials of SERC, the President of SIAC, presidents or representatives of relevant associations in the securities sector, presidents or founders of companies in the securities industry, representatives of the Cambodia Securities Exchange, and representatives of other related securities companies. During this distinguished event, Banjaran Asset Management (Cambodia) Plc. was honored to receive an Certificate of Distinction from SIAC, presented under the presidency of H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of SERC and Honorary President of SIAC.
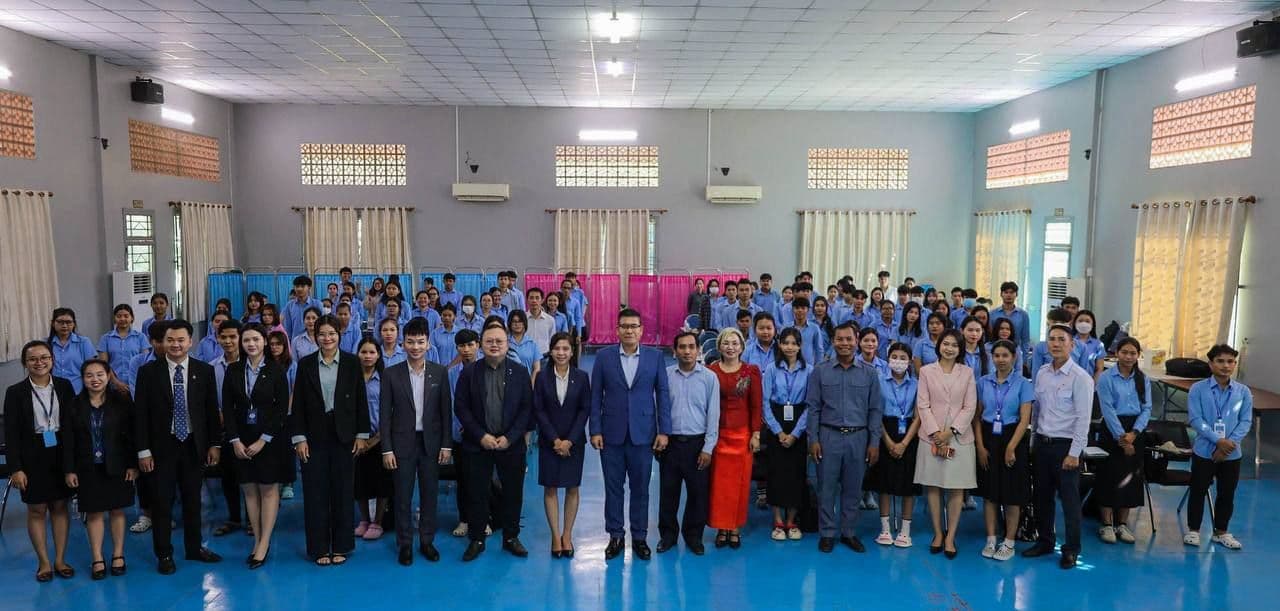
Workshop on "Smart Investment" at National Institute of Social Affairs
On 10th of March 2026, representatives from Banjaran Asset Management (Cambodia) Plc. participated in a workshop on "Smart Investment" Organized by ACLEDA Securities Plc., in collaboration with the Securities and Exchange Regulator of Cambodia (SERC) held at the National Institute of Social Affairs. During the session, Mr. Sok Chantola, Deputy Sales & Marketing Manager, delivered key details presentation on “Investment in Collective Investment Scheme (CIS)”. Sharing insights on investment opportunities and financial planning to future generation.
Cambodia-ASEAN Business Summit 2026 (Part 2)
4th March 2026, the Cambodia-ASEAN Business Summit 2026 was successfully held, under the theme “Transforming ASEAN: Innovation, Integration and Industrial Evolution.” The summit was presided over by The Prime Minister of the Kingdom of Cambodia, Samdech Moha Borvor Thipadei Hun Manet, at Sofitel Phnom Penh Phokeethra. Co-organized by the Cambodia Chamber of Commerce , ASEAN Business Advisory Council Cambodia , and International Chambers and Business Associations in Cambodia , the summit brought together government leaders, policymakers, business executives and thought leaders from across ASEAN, representing diverse industries and sectors, to strengthen regional collaboration and further encourage foreign investors to explore investment opportunities in Cambodia. Banjaran Asset Management (Cambodia) Plc. was honored to participate in the summit, with CEO, Mr. Eric Loo, and Mr. Mok Chinly, Legal and Compliance Manager, as well as, Legal and Compliance Officer, Mr. Taing Hoy, in attendance. Their presence reflects Banjaran AMC’s continued commitment to supporting Cambodia’s financial ecosystem and engaging with regional leaders to explore opportunities that contribute to the Kingdom’s growing investment landscape within ASEAN.
Cambodia-ASEAN Business Summit 2026
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the Cambodia-ASEAN Business summit 2026, with CEO, Mr. Eric Loo, and Mr. Mok Chinly, Legal and Compliance Manager, as well as, Legal and Compliance Officer, Mr. Taing Hoy, in attendance. Their presence reflects Banjaran AMC’s continued commitment to supporting Cambodia’s financial ecosystem and engaging with regional leaders to explore opportunities that contribute to the Kingdom’s growing investment landscape within ASEAN, held at Sofitel Phnom Penh Phokeethra on 4th March 2026. Throughout the summit presided over by The Prime Minister of the Kingdom of Cambodia, Samdech Moha Borvor Thipadei Hun Manet, the team had the opportunity to network with high-level government officials, policymakers, and key industry leaders, exchanging insights on regional integration, innovation-driven growth, and ASEAN’s evolving investment landscape. The summit served as a valuable platform for dialogue and collaboration, further reinforcing Cambodia’s role as a growing country for investment and innovation in the region.
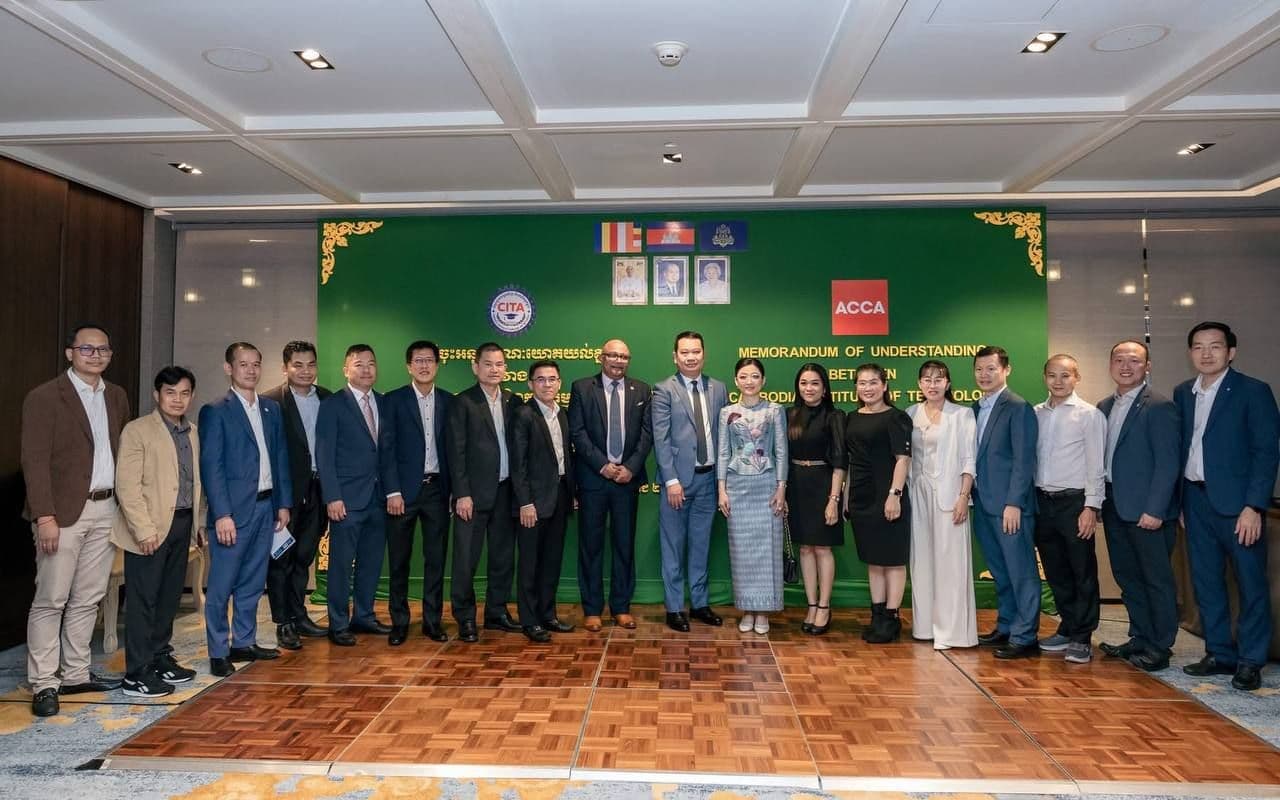
Strengthening Professional Education in Cambodia: A Landmark MOU Signing Ceremony
On 24th February 2026, we are honored to have witnessed a landmark moment for professional education in Cambodia! Our CEO, Mr. Eric Loo and Head of Growth & Strategy, Mrs. Edeza Banquilis, attended the official MOU signing ceremony between the Cambodia Institute of Technology and Agriculture (CITA), Business School of Accountancy (BSA) , and Association of Chartered Certified Accountants (ACCA) . The ceremony was a high-profile success, graced by H.E. Chea Kosal, Secretary of State and High Representative of H.E. Heng Sour, Minister of Labour and Vocational Training. At Banjaran AMC, we are proud to support initiatives that foster talent and drive sustainable economic development across the region.
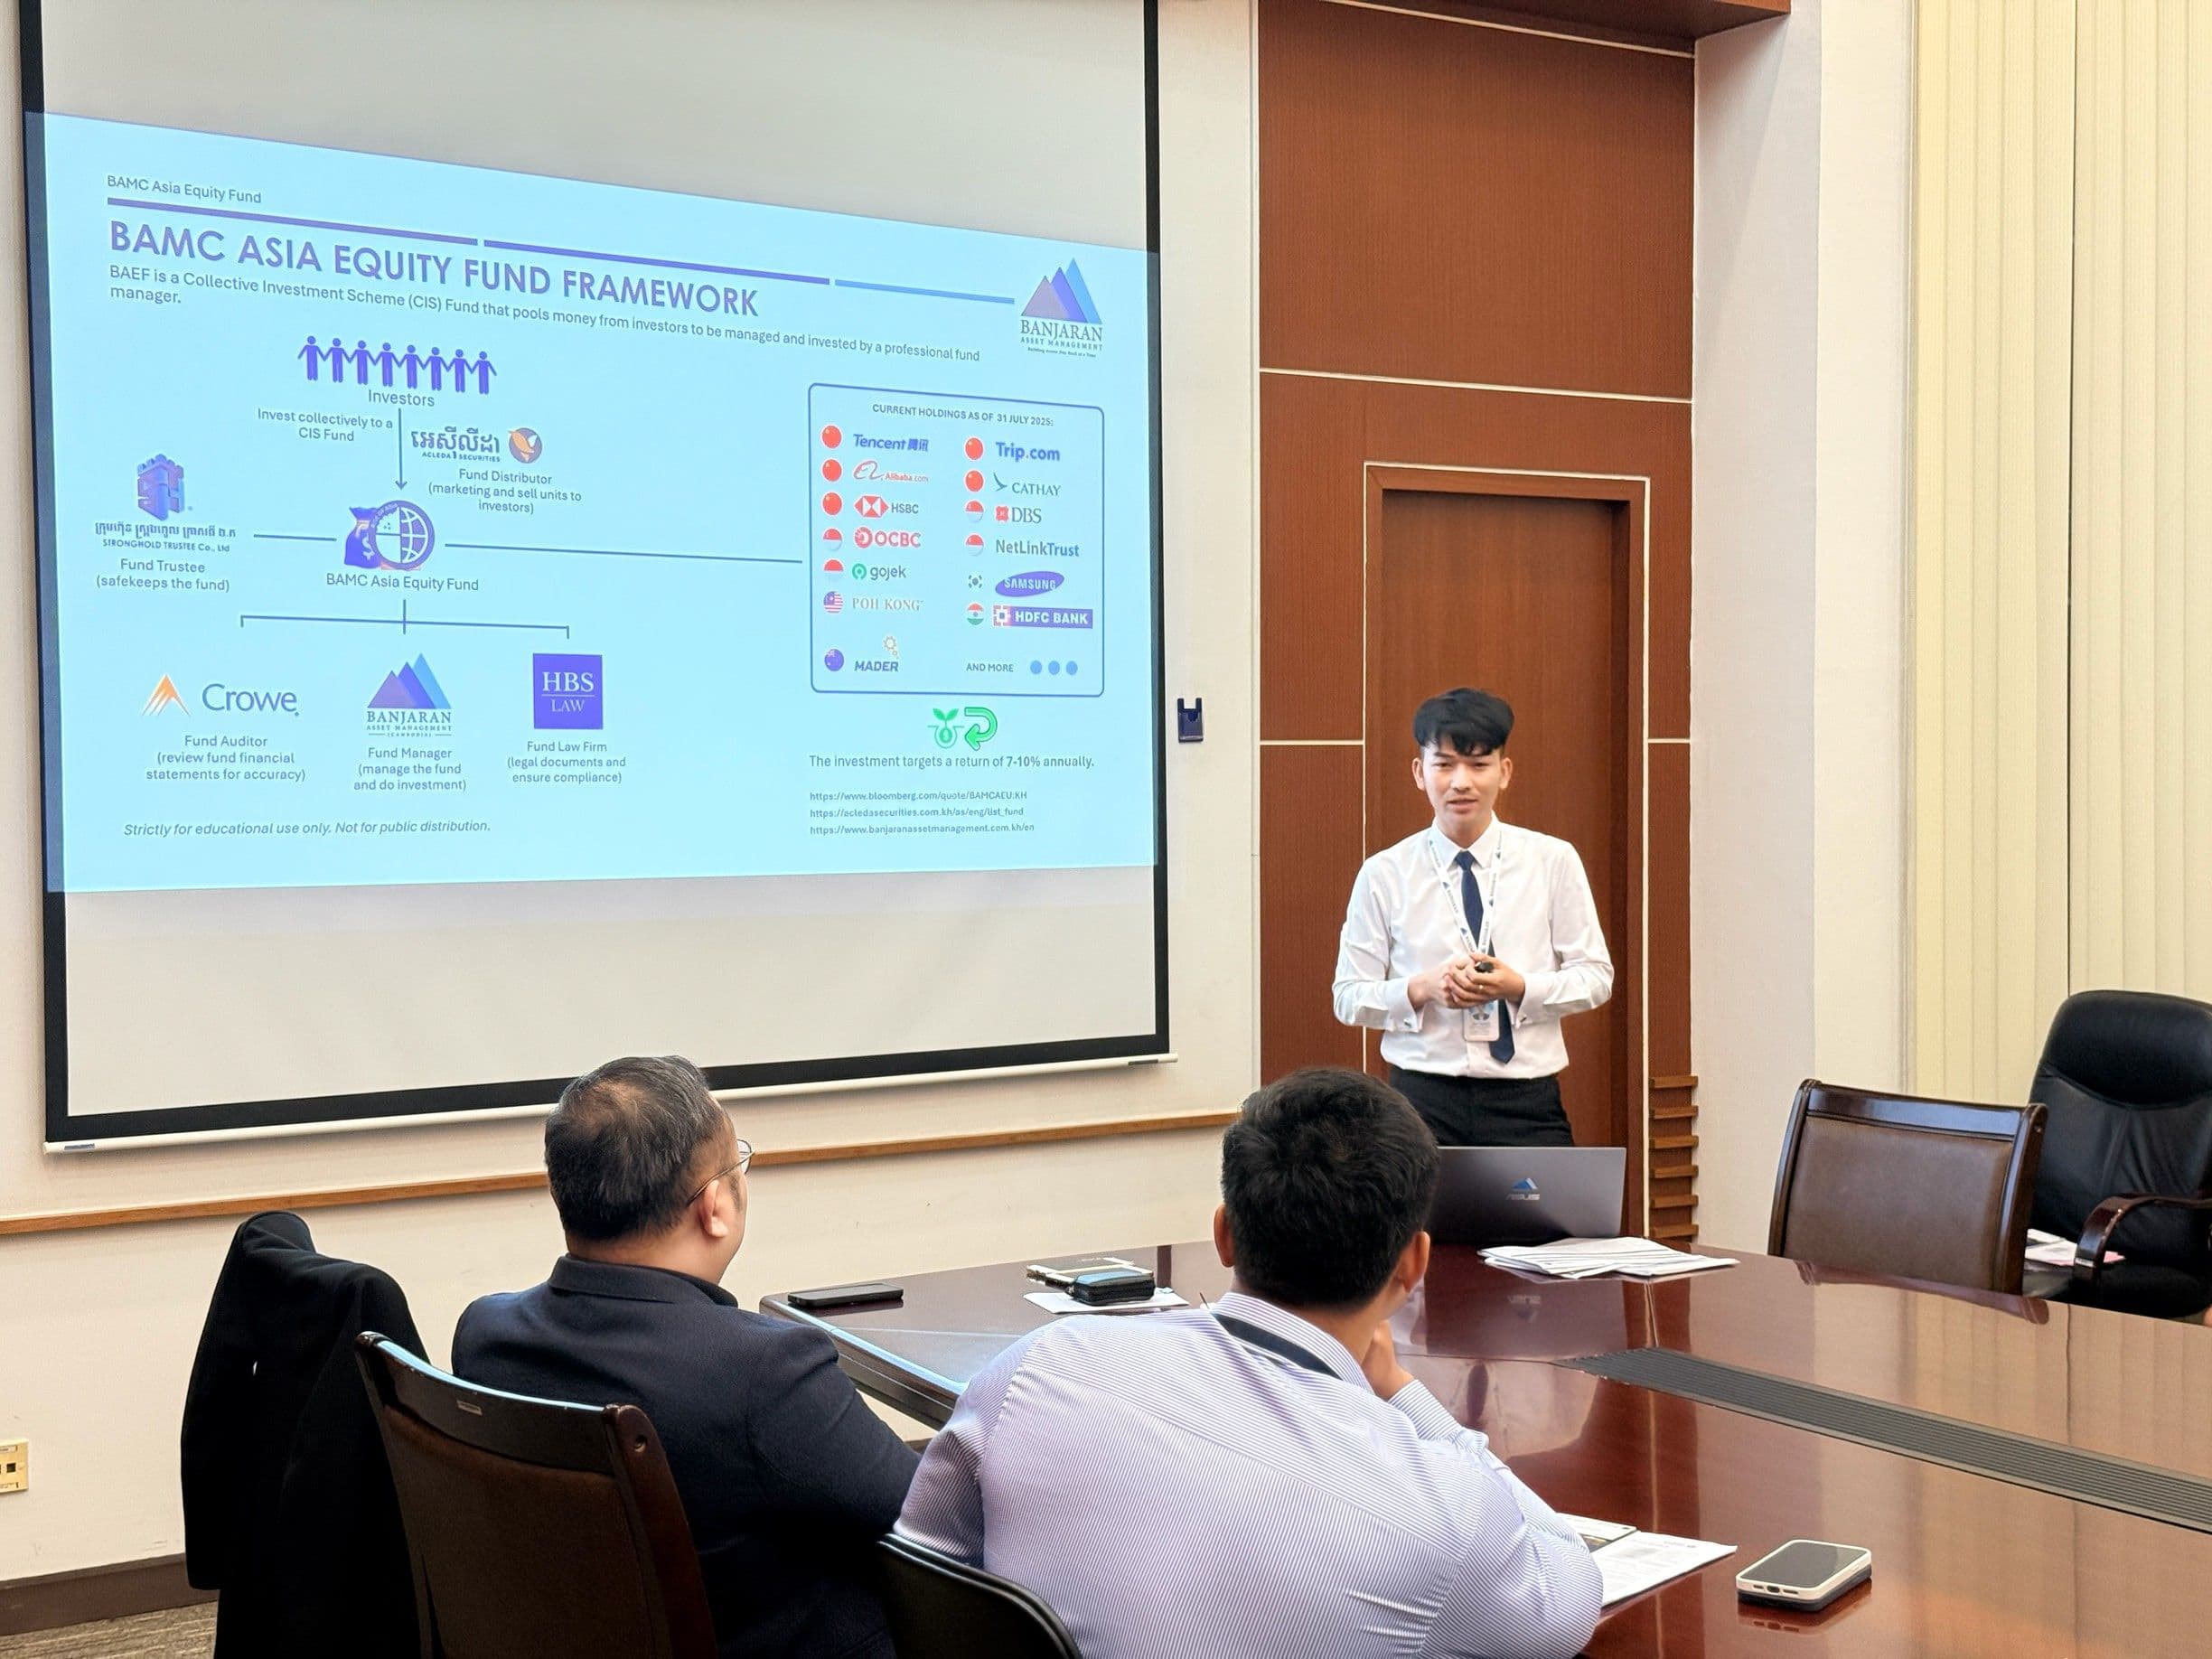
Let’s Talk Investment! Topic on: Collective Investment Scheme (CIS)
Thank you to everyone who joined us today for this session on 16th January 2026 at ACLEDA Securities Plc., centered on building a clearer understanding of Collective Investment Schemes and their role in long-term investing. We truly appreciate the participants for the opportunity to share practical investment insights and contribute to building greater financial confidence within the Cambodian market. We look forward to continuing this learning journey together in the future!
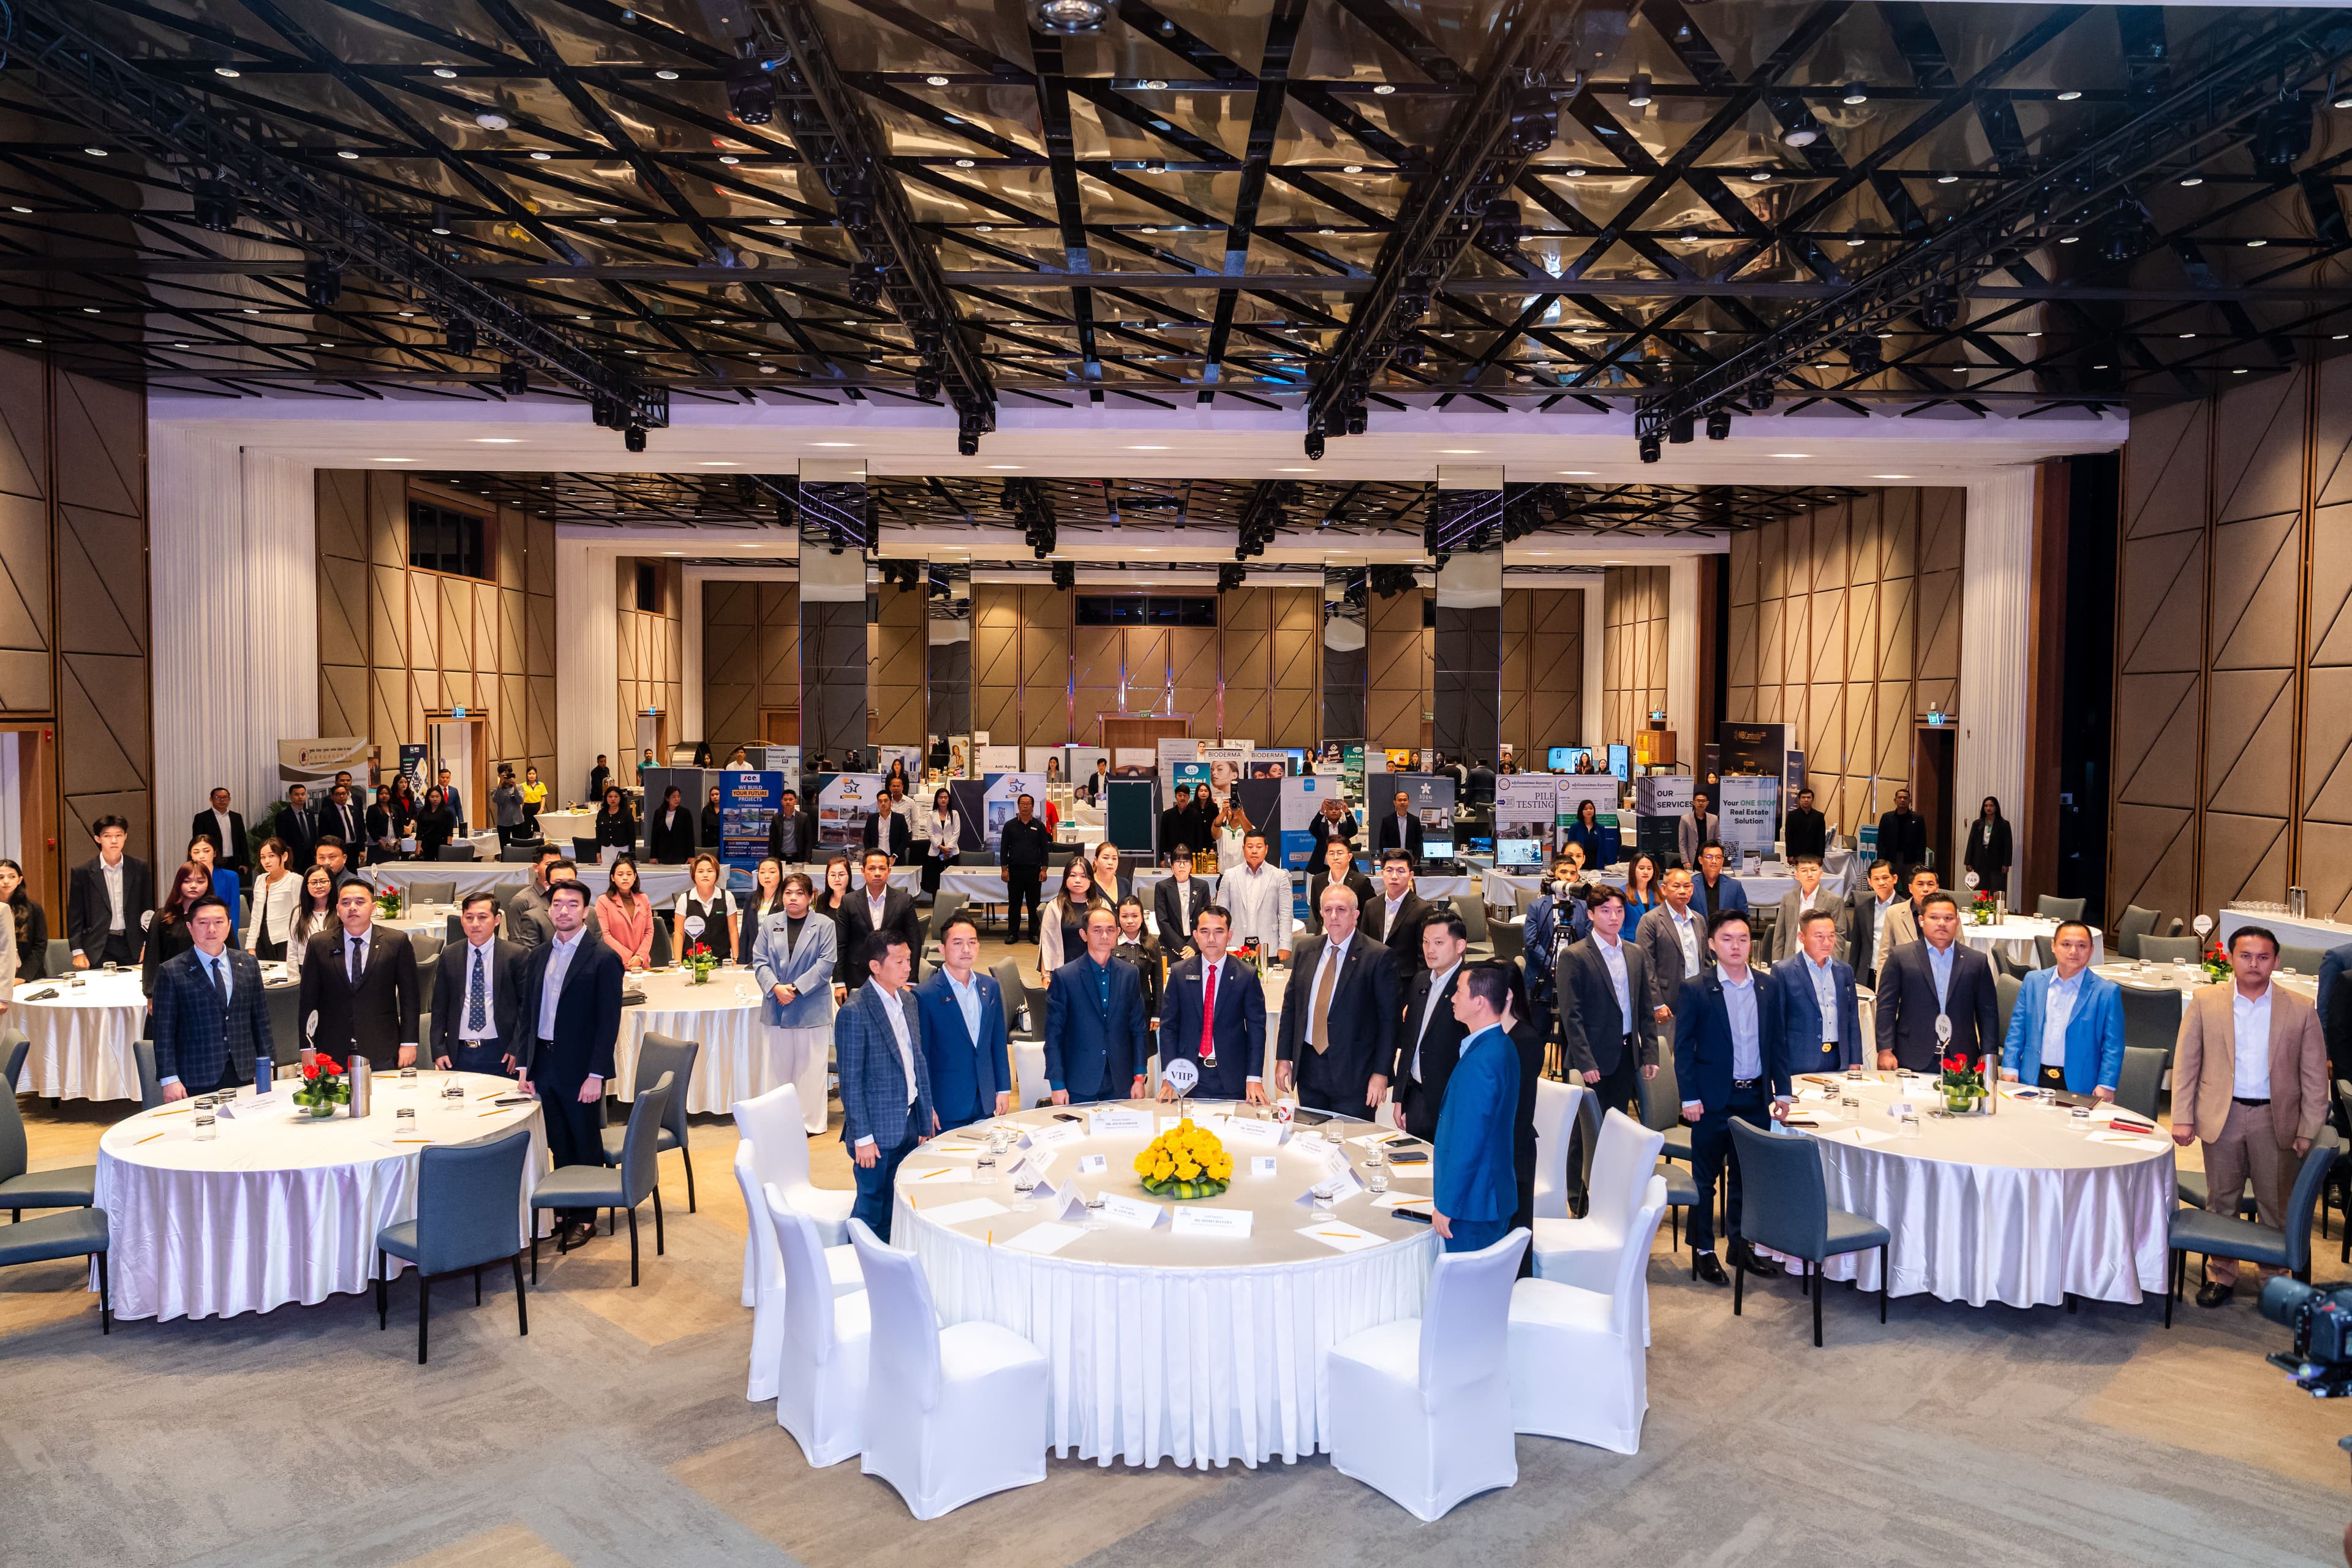
CorporateConnections柬埔寨年度博览会:建筑、商业服务、食品饮料及酒店业
富亚资产管理(柬埔寨)有限公司很荣幸参加了于2025年11月28日举行的‘2025年 CorporateConnections 柬埔寨年度博览会:建筑、商业服务、食品饮料及酒店业’。 我们很高兴设立展位,并与众多来访和参与我们活动的与会者进行交流。你们的兴趣和参与真正让我们出席此次活动变得充满意义。 请与我们保持联系,以获取更多即将到来的机会和活动信息!
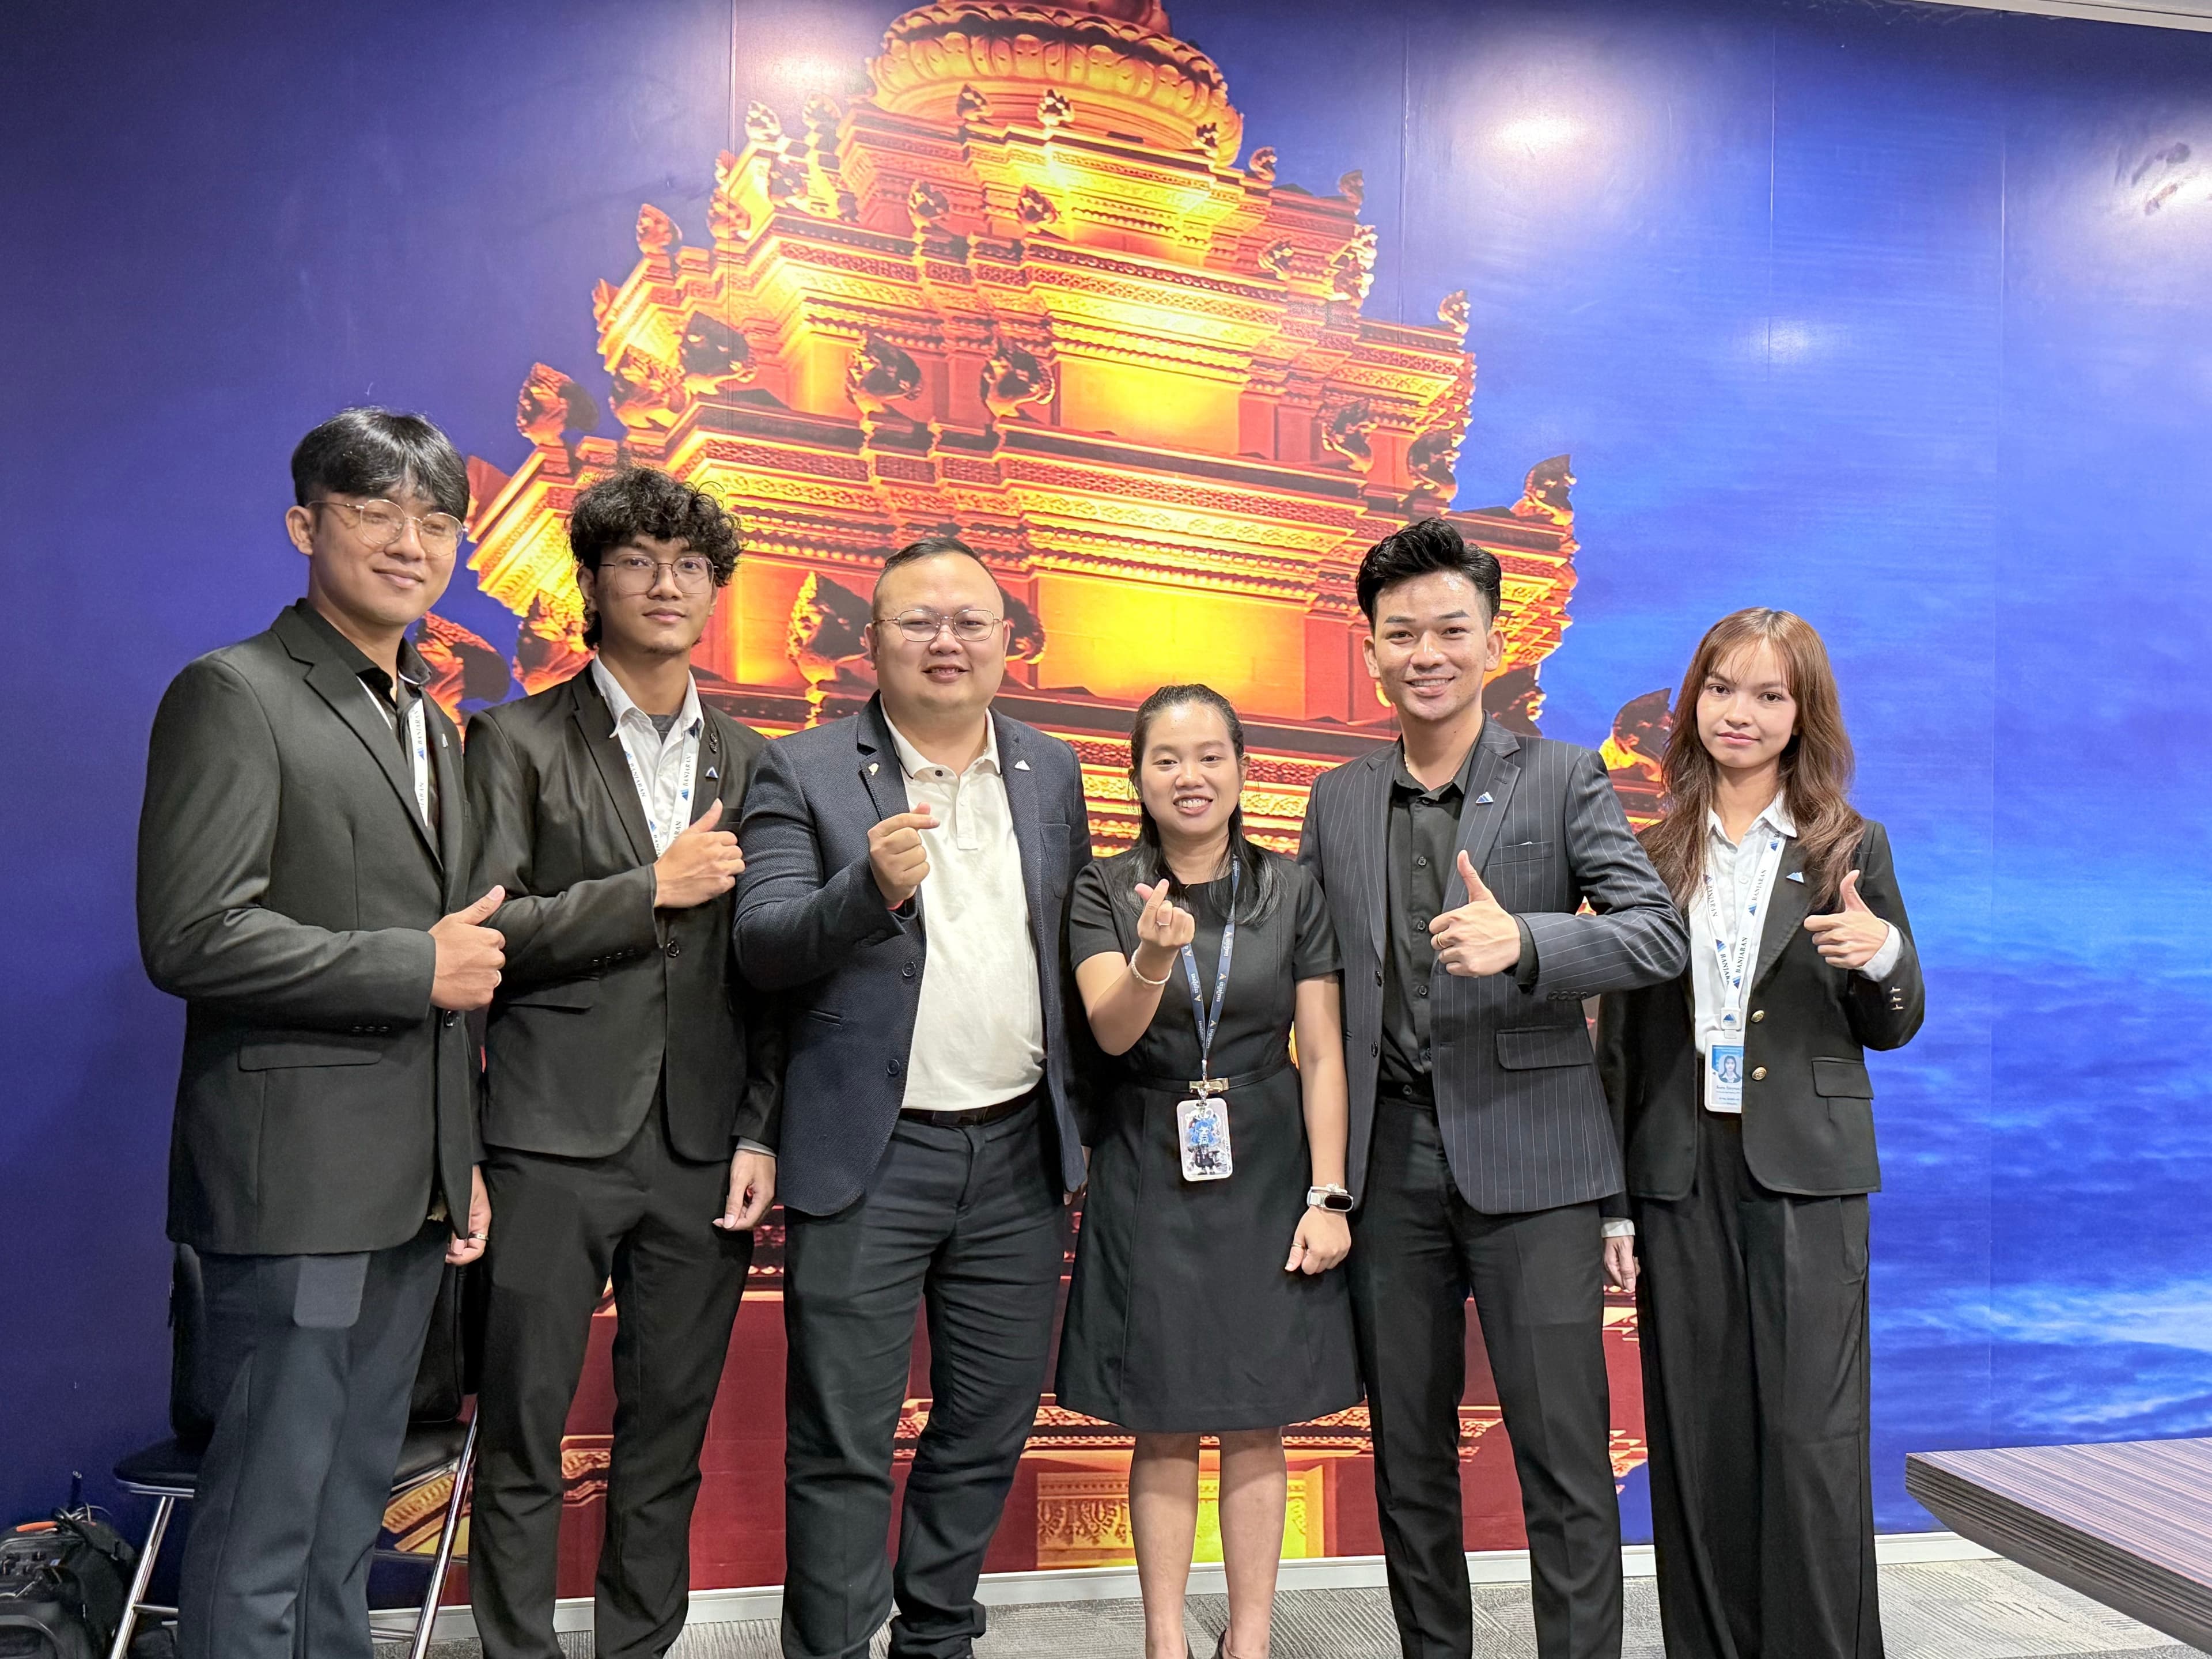
让我们谈谈投资!关于集合投资计划的见解!
感谢所有在2025年11月21日加入我们爱喜利达证券行活动的人。你们的提问、热情和参与让关于集合投资计划的讨论既引人入胜又充满意义。我们感谢有机会分享实用的投资知识,并帮助社区建立财务信心。 我们很高兴能在即将到来的12月会议中与您继续这一学习之旅。敬请关注,以免错过下一场活动!
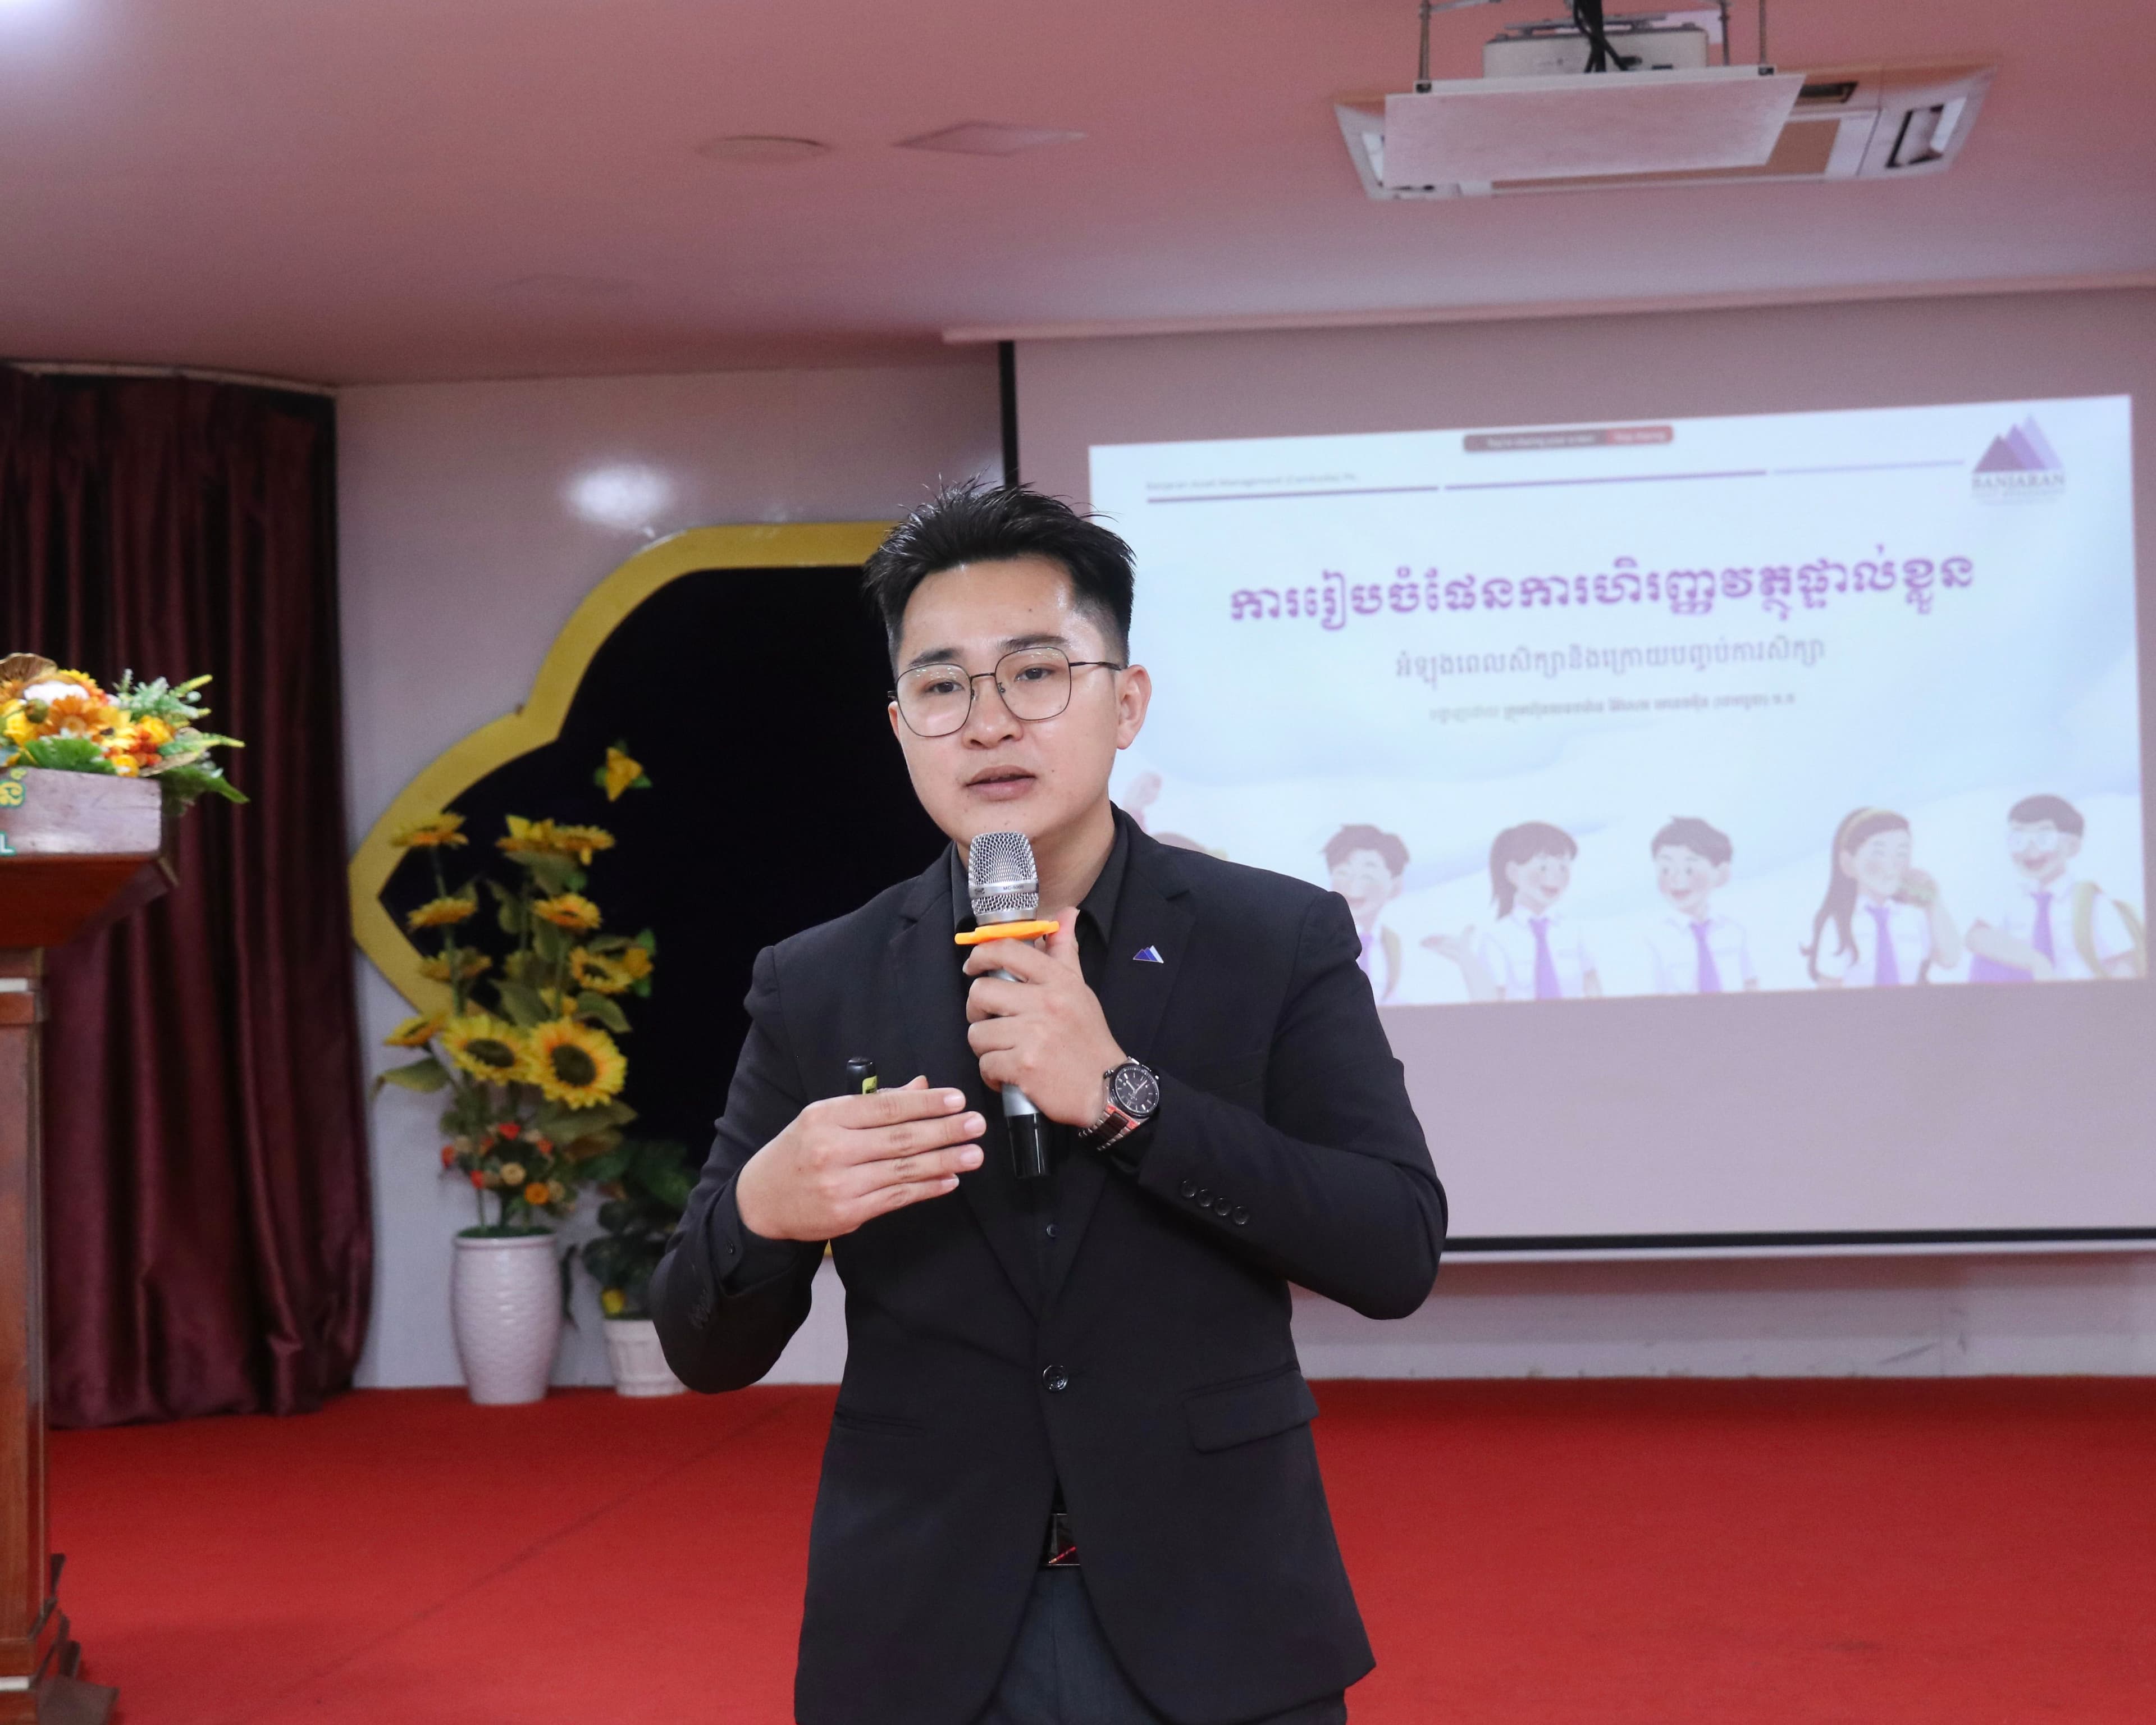
“提升证券业金融知识意识”培训课程(第二部分)
2025年11月12日下午,富亚资产管理(柬埔寨)有限公司的代表参加了由柬埔寨证券交易监管局(SERC)与韦斯莱学校(Santhormok 校区)合作举办的‘提升证券业金融知识意识’培训课程。 在此次培训期间,经富亚资产管理(柬埔寨)有限公司管理层批准,法律合规官 Taing Hoy 先生发表了关于‘毕业期间及毕业后的个人财务规划’的演讲,指导参与者如何有效地管理和规划其长期财务储蓄。 此次培训旨在提升学生的金融素养,鼓励他们养成良好的储蓄习惯,并践行明智的投资方式,帮助他们规划长期的财务稳定与保障。
市场展望
2026 October Market Outlook: Asia Markets – AI Valuation Concerns and Rising Geopolitical Risks
The direction of US monetary policy remains a key source of uncertainty. Minutes from the September Federal Open Market Committee (“FOMC”) meeting indicated that a further rate increase before year-end remains possible. However, Chair Warsh has declined to commit to a path, identifying the October and December meetings as the key decision points. Ahead of the next FOMC meeting on 27–28 October, the International Monetary Fund has cautioned that uncertainty over US monetary policy could keep Asian financial markets volatile. The recent sell-off has also brought the financing of AI investment into sharper focus. Chair Warsh noted that large technology companies raising funds in the bond market are adding to competition for capital. In our view, investors are likely to place greater scrutiny on the returns these companies generate from their AI spending. Developments in the Middle East remain a key swing factor for oil prices and inflation. Before the conflict began in late February, the Strait of Hormuz carried around one-fifth of global oil supply. Within Asia, the most significant development has been in Indonesia. On 15 October, index provider MSCI Inc. launched a consultation on reclassifying Indonesia from Emerging Market to Standalone Market status, citing insufficient progress on market transparency, concentrated shareholdings and weak enforcement. This contrasts with FTSE Russell, which reaffirmed Indonesia’s emerging market status. The Jakarta Composite Index fell 8.0% following the announcement, which triggered a trading halt. MSCI has also frozen certain index changes for Indonesian securities, including new additions, until further notice. The announcement adds to a difficult year for Indonesia, whose stock market has fallen more than 30% to become the world’s worst performing this year, according to Bloomberg, while Moody’s and Fitch have both revised the sovereign rating outlook to negative. With the consultation open until 30 April 2027, analysts expect foreign outflows to continue. In North Asia, the October sell-off highlighted how exposed South Korea and Taiwan have become to swings in AI sentiment after very strong gains over the past year. The KOSPI and TAIEX rose 86.7% and 80.6% respectively over the past year, and the TAIEX’s price-to-earnings ratio has expanded to 27.9 times from 23.1 times. Singapore again demonstrated its defensive qualities, with the Straits Times Index declining only 0.5% on 15 October, a far smaller fall than its North Asian peers. Overall, investor sentiment has shifted from chasing AI momentum towards greater caution on valuations, funding costs, and geopolitical risk. In this environment, we remain focused on businesses with strong balance sheets, sustainable earnings and pricing power, which we believe are better positioned to navigate persistent inflation and energy price shocks. We continue to apply a disciplined, bottom-up approach to stock selection and to maintain diversification across geographies and themes.
2026 September Market Outlook: Navigating Market Divergence
The Fed maintained a restrictive, data-dependent stance through August and subsequently raised the federal funds target range by 25 basis points to 3.75-4.00% citing persistent inflationary pressures. Updated projections point to the possibility of one further increase in 2026. Elevated long-dated US Treasury yields continue to present a valuation risk particularly for growth, technology and AI-related companies, whose expected cash flows lie further in the future. At the same time, continued corporate earnings delivery and investments in strategic technologies along the tech supply chain have so far helped the global economy absorb tighter financial conditions. Strong earnings guidance from major global technology companies supports the view that investment in data centres, advanced chips and supporting infrastructure remains resilient. Within Asia, performance has diverged meaningfully across countries. Singapore remains the region’s defensible market, with strong banking profitability and wealth management inflows attracting investor interest amid global uncertainty. Taiwan and South Korea’s technology sector continues to be major beneficiaries of surging AI-related demand. On the other hand, confidence towards China’s and Indonesia’s growth outlook remains fragile. China’s slow economic momentum is a result of a weak property market and slow domestic consumption, while Indonesia’s commodity price normalisation and concerns over capital outflows weigh on sentiment. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.
2026 August Market Outlook: Navigating Volatility
Concerns around the durability of AI-related capital expenditure and intensifying competition triggered a sharp sector sell-off after a mid-July peak. Investor sentiment turned more discerning on the back of earnings season, and questions arose regarding how sustainable the AI investment pace is without eating into cash generation. Capital rotated out of semiconductors and into energy, financials and value stocks, shifting to markets and names seen as less exposed to a single-theme correction. Layered on top was renewed Middle East escalation and its effect on rates expectations. Brent crude spiked back above $100/barrel intermittently after the US reinstated a naval blockade on Iran and announced plans to impose a levy on cargo transiting Hormuz, although the levy was never implemented. This revived inflation concerns and caused markets to price a reduced likelihood of further Fed easing. Elevated US bond yields further weighed on stocks. Looking ahead, renewed conflict or another AI-related pullback could swiftly unwind recent sentiment gains and force a repricing of both rates and earnings expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
2026 July Market Outlook: Navigating Crosscurrents
Central banks broadly maintained a data-dependent stance through the period and remained watchful even as global energy-driven inflation eased. The Federal Reserve reaffirmed its commitment to price stability even as growth prospects softened, while the European Central Bank similarly balanced improving headline inflation against still-elevated services prices. Closer to home, the Monetary Authority of Singapore raised its 2026 core inflation forecast on concerns that persistent price pressures could dampen household spending. The Hormuz disruption has driven inflation fears that outweigh traditional safe-haven demand. Gold and silver have moved in an unusual, counterintuitive pattern, falling rather than rallying as fighting escalated. In equities, investor sentiment shifted markedly as the AI-led rally that dominated the first half of the year gave way to a bout of volatility, prompting some rotation into value and cyclicals. Asian equities showed sharp dispersion rather than uniform resilience. In July 2026, Hong Kong’s Hang Seng emerged as the standout performer on continued strength in Chinese technology and AI names, while South Korea’s Kospi and Japan’s Nikkei slipped from June’s rebound as the memory-chip optimism and AI trade cooled. Looking ahead, markets remain caught between two competing narratives, a genuine easing of geopolitical and energy-driven inflation pressure, against the risk of renewed hostilities or a resurgence in AI-related volatility, which could quickly reverse recent gains in sentiment and reprice rate expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
2026 June Market Outlook: From AI-Led Momentum to Persistent Uncertainty—A Disciplined Path Forward
Stronger than expected inflation in the US led newly installed Fed Chair Kevin Warsh to reinforce expectations that any rate cut is more likely in late 2026 or into 2027. Despite this hawkish view, US equities pushed to fresh highs, led by technology stocks. This period also saw Space Exploration Technologies Corp.’s (“SpaceX”) record-setting initial public offering, becoming a focal point for risk appetite and growth sentiment, which further amplified market enthusiasm. In the near term, the success of the SpaceX listing is likely to add further liquidity into space, artificial intelligence (“AI”) infrastructure and adjacent sectors. Investor sentiment remains heavily concentrated in AI-related and technology names, and some investors view the Asian market as a way to increase exposure at more attractive valuations than US technology leaders. Strong momentum in Asia is led by Korea, Taiwan and Japan, which play a central role in the AI and memory chip supply chain. On the other hand, China continues to lag even with incremental policy support. In other key markets, UK equities underperformed their peers, and Eurozone technology stocks performed moderately amid weak macroeconomic data, where the pullback in oil prices eased some inflationary pressure. Markets remain highly sensitive to developments in the Strait of Hormuz, where disruptions and the current partial normalisation of shipping through the strait weigh on energy prices and inflation expectations. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macroeconomic uncertainty.
2026 May Market Outlook: From Record Highs to Rising Uncertainty—A Selective Path Forward
Major indices have reached new highs since the March dip. Strong corporate earnings have reinforced investor confidence and sustained the ongoing risk-on rotation into AI-related stocks. The technology sector now represents a larger share on the MSCI Emerging Markets Index than the S&P 500, underscoring the central role of Taiwan and South Korea in the AI supply chain. With inflation still elevated and growth looking uneven across regions, central banks are balancing financial stability and energy-driven price pressures. Expectations for rate cuts have been pushed out or replaced by further tightening of monetary policy. The new Federal Reserve Chair, Kevin Warsh, known to favour rate cuts, faces inflationary pressures in the US economy that work against the dovish narrative, making rate cuts unlikely. Other central banks, such as the Bank of Japan and the European Central Bank have kept its policy unchanged, but with upward revisions to inflation forecasts, investors expect rate hikes this year. Though markets have appeared resilient to geopolitical shocks, the continuation of the Strait of Hormuz blockage can dampen economic activity through supply chain disruption and entrenching inflationary pressures. Against this backdrop, maintaining well-diversified exposure across geographies and themes remains important. We continue to be highly selective in stock selection, adhering to a disciplined, bottom-up approach to portfolio construction that prioritises quality and resilience to macro uncertainty.