


លេខទូរសព្ទ្ទ
អ៊ីមែល
អាសយដ្ឋាន
:
:
:

Khmer
English - English
Khmer - ខ្មែរ
Chinese - 中文
English - English
Khmer - ខ្មែរ
Chinese - 中文
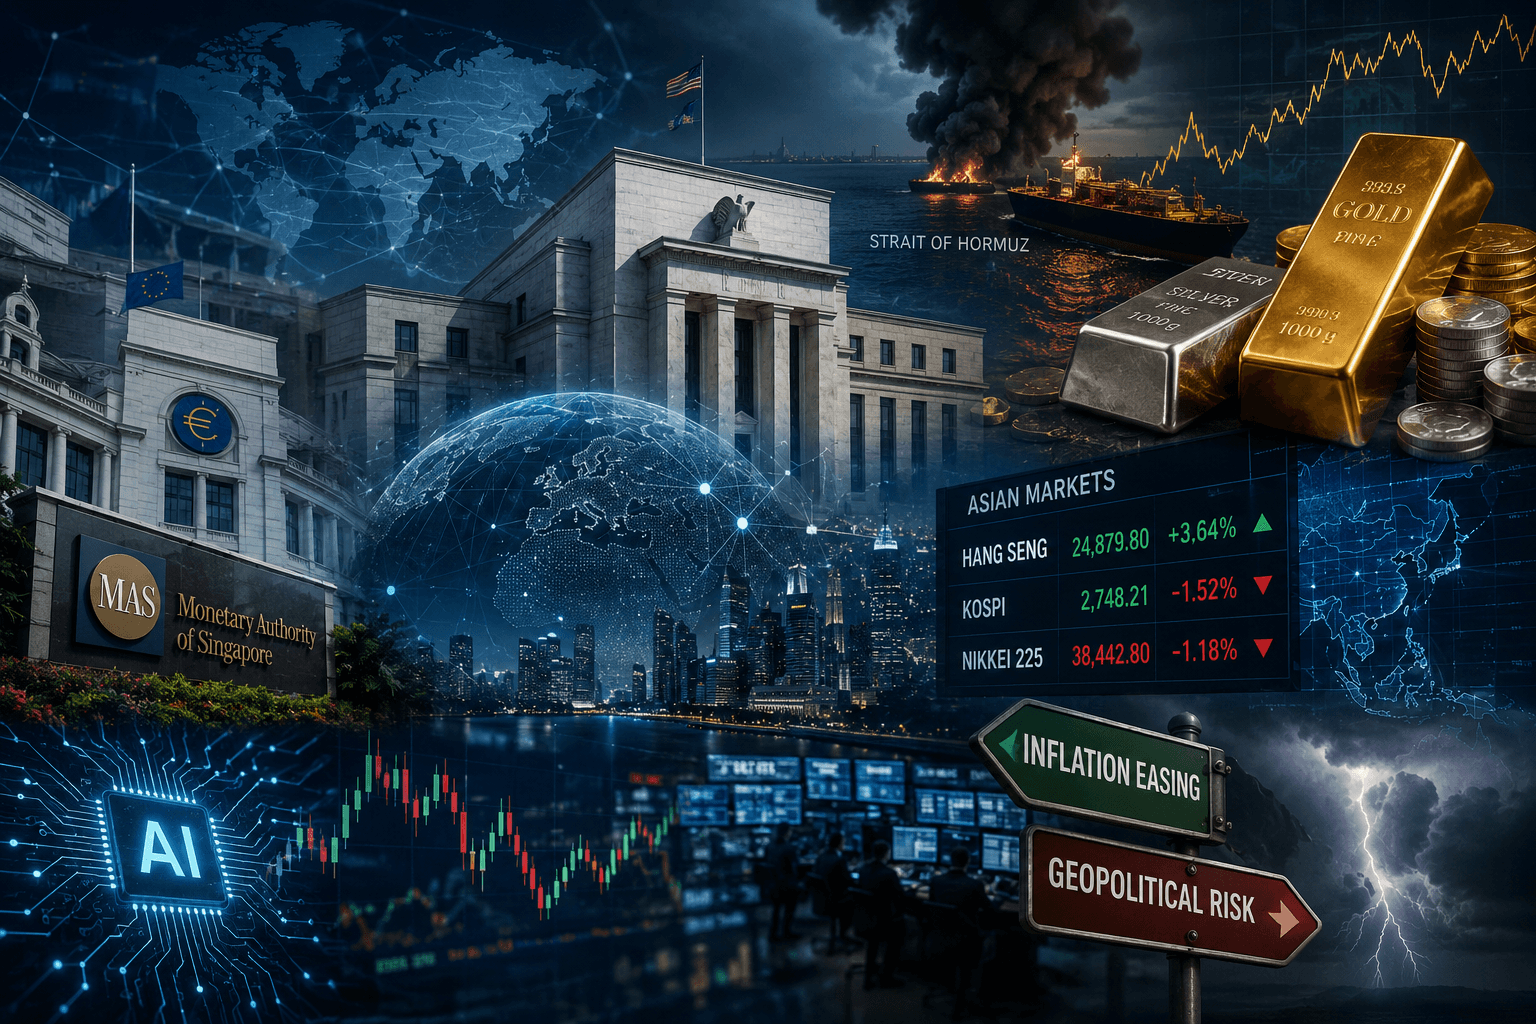

Central banks broadly maintained a data-dependent stance through the period and remained watchful even as global energy-driven inflation eased. The Federal Reserve reaffirmed its commitment to price stability even as growth prospects softened, while the European Central Bank similarly balanced improving headline inflation against still-elevated services prices. Closer to home, the Monetary Authority of Singapore raised its 2026 core inflation forecast on concerns that persistent price pressures could dampen household spending.
The Hormuz disruption has driven inflation fears that outweigh traditional safe-haven demand. Gold and silver have moved in an unusual, counterintuitive pattern, falling rather than rallying as fighting escalated. In equities, investor sentiment shifted markedly as the AI-led rally that dominated the first half of the year gave way to a bout of volatility, prompting some rotation into value and cyclicals. Asian equities showed sharp dispersion rather than uniform resilience. In July 2026, Hong Kong’s Hang Seng emerged as the standout performer on continued strength in Chinese technology and AI names, while South Korea’s Kospi and Japan’s Nikkei slipped from June’s rebound as the memory-chip optimism and AI trade cooled.
Looking ahead, markets remain caught between two competing narratives, a genuine easing of geopolitical and energy-driven inflation pressure, against the risk of renewed hostilities or a resurgence in AI-related volatility, which could quickly reverse recent gains in sentiment and reprice rate expectations. Against this backdrop, we continue to favour a diversified, bottom-up approach that balances exposure to structural AI and technology themes with quality, less crowded names to weather through volatility.
Related Market Outlooks
2026 August Market Outlook: Navigating Volatility
Concerns around the durability of AI-related capital expenditure and intensifying competition triggered a sharp sector sell-off after a mid-July peak. Investor sentiment turned more discerning on the back of earnings season, and questions arose regarding how sustainable the AI investment pace is without eating into cash generation. Capital rotated out of semiconductors and into energy, financials and value stocks, shifting to markets and names seen as less exposed to a single-theme correction.

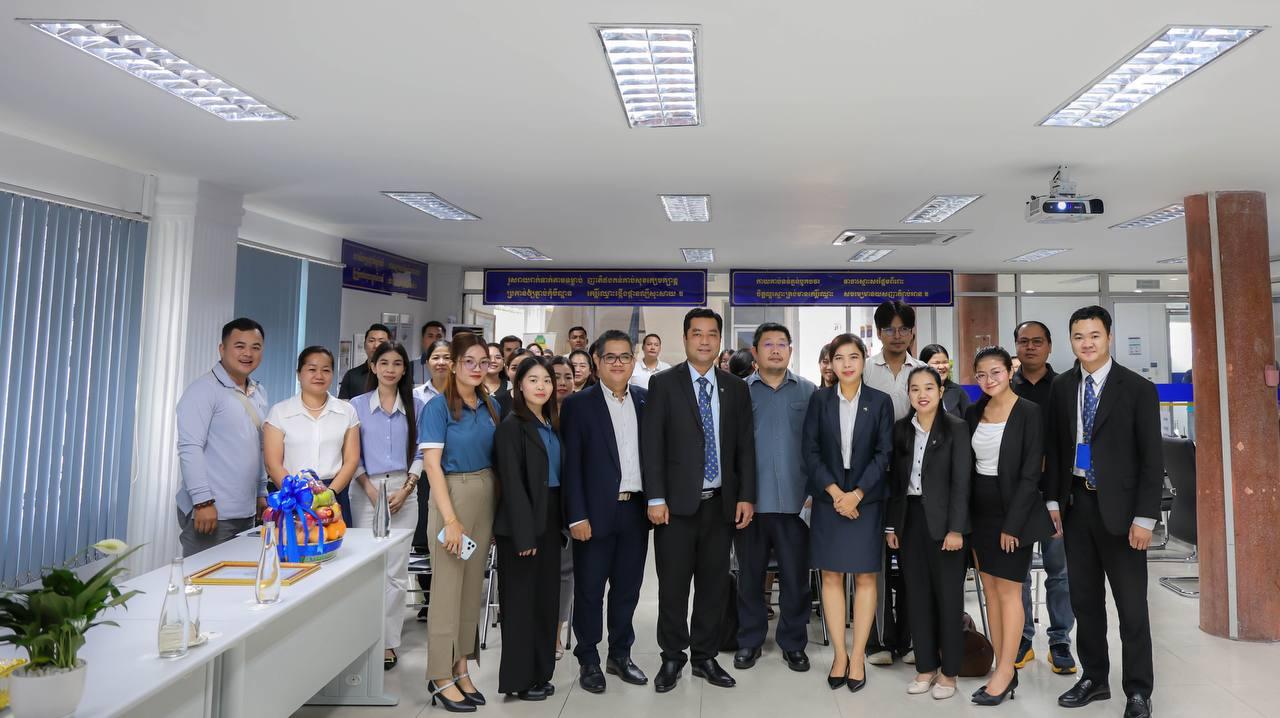
ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក បន្តរៀបចំសិក្ខាសាលា «ឱកាសមាសនៃការវិនិយោគមូលបត្រ» ក្រោមកម្មវិធីរ៉ូដសូវលើកទី៣ ដោយជោគជ័យ
នាព្រឹកថ្ងៃទី៤ ខែកក្កដា ឆ្នាំ២០២៦ ក្រុមហ៊ុនបេនចារ៉ាន អ៊ែសេត មេនេចម៉ិន (ខេមបូឌា) ម.ក សហការជាមួយ ក្រុមហ៊ុនមូលបត្រ អេស៊ីលីដា ម.ក សាខាក្រុមហ៊ុនក្នុងស្រុកធនាគារអេស៊ីលីដា ភីអិលស៊ី (ខណ្ឌបឹងកេងកង - សង្កាត់ទំនប់ទឹក) បានរៀបចំសិក្ខាសាលាក្រោមប្រធានបទ “ឱកាសមាសនៃការវិនិយោគមូលបត្រ” ប្រកបដោយជោគជ័យ ដែលជាផ្នែកមួយនៃកម្មវិធីរ៉ូដសូវលើកទី៣ ដែលបានរៀបចំឡើងនៅសាលប្រជុំរបស់សាខាក្រុមហ៊ុនក្នុងស្រុក ធនាគារ អេស៊ីលីដា ភីអិលស៊ី (ខណ្ឌបឹងកេងកង-សង្កាត់ទំនប់ទឹក)។
2026 June Market Outlook: From AI-Led Momentum to Persistent Uncertainty—A Disciplined Path Forward
Stronger than expected inflation in the US led newly installed Fed Chair Kevin Warsh to reinforce expectations that any rate cut is more likely in late 2026 or into 2027. Despite this hawkish view, US equities pushed to fresh highs, led by technology stocks. This period also saw Space Exploration Technologies Corp.’s (“SpaceX”) record-setting initial public offering, becoming a focal point for risk appetite and growth sentiment, which further amplified market enthusiasm. In the near term, the success of the SpaceX listing is likely to add further liquidity into space, artificial intelligence (“AI”) infrastructure and adjacent sectors.
2026 May Market Outlook: From Record Highs to Rising Uncertainty—A Selective Path Forward
With inflation still elevated and growth looking uneven across regions, central banks are balancing financial stability and energy-driven price pressures. Expectations for rate cuts have been pushed out or replaced by further tightening of monetary policy. The new Federal Reserve Chair, Kevin Warsh, known to favour rate cuts, faces inflationary pressures in the US economy that work against the dovish narrative, making rate cuts unlikely. Other central banks, such as the Bank of Japan and the European Central Bank have kept its policy unchanged, but with upward revisions to inflation forecasts, investors expect rate hikes this year.
2026 April Market Outlook: From Conflict Shock to Market Strength — What’s Driving the Recovery
Major indices across the countries tumbled in March but abruptly spiked in April upon the announcement of US-Iran peace talks, though the US Navy continues its blockade of the Strait of Hormuz. Record highs in the tech-heavy S&P 500 and strong US corporate earnings reaffirm the market’s resilience throughout the conflict, particularly for demand in technology.
2026 March Market Outlook: Markets Under Pressure as Geopolitical Tensions Rise
The US-Israel war with Iran has created a delicate balancing act between investing for resilient growth and managing geopolitical volatility. While a "soft landing" remains the baseline for many advanced economies, the landscape has grown more complex following the late-February shocks.On interest rate watch, the US Fed is expected to maintain a "higher-for-longer" stance to counter inflationary pressures from rising energy cost, and to a lesser extent the new 15% global tariffs. Markets are pricing in a sustained "war premium" in energy. With Brent crude hovering near $100, any further escalation in the Middle East could reignite global supply-side inflation, which may lead to extended high-interest-rate environment and hence leading to a sharp global economic slowdown.