

洞察力
获取最新资讯、专家分析及市场展望,抢先洞察行业动态。
新闻中心
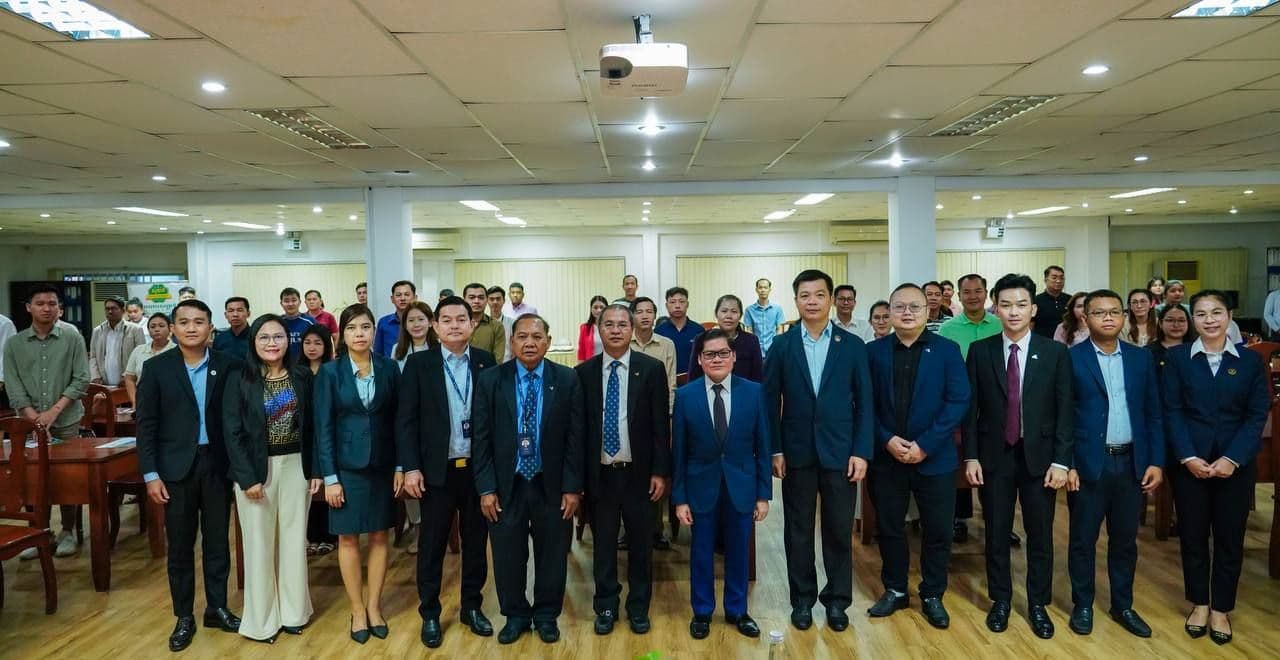
Roadshow at Boeng Keng Kang Ti Muoy Branch
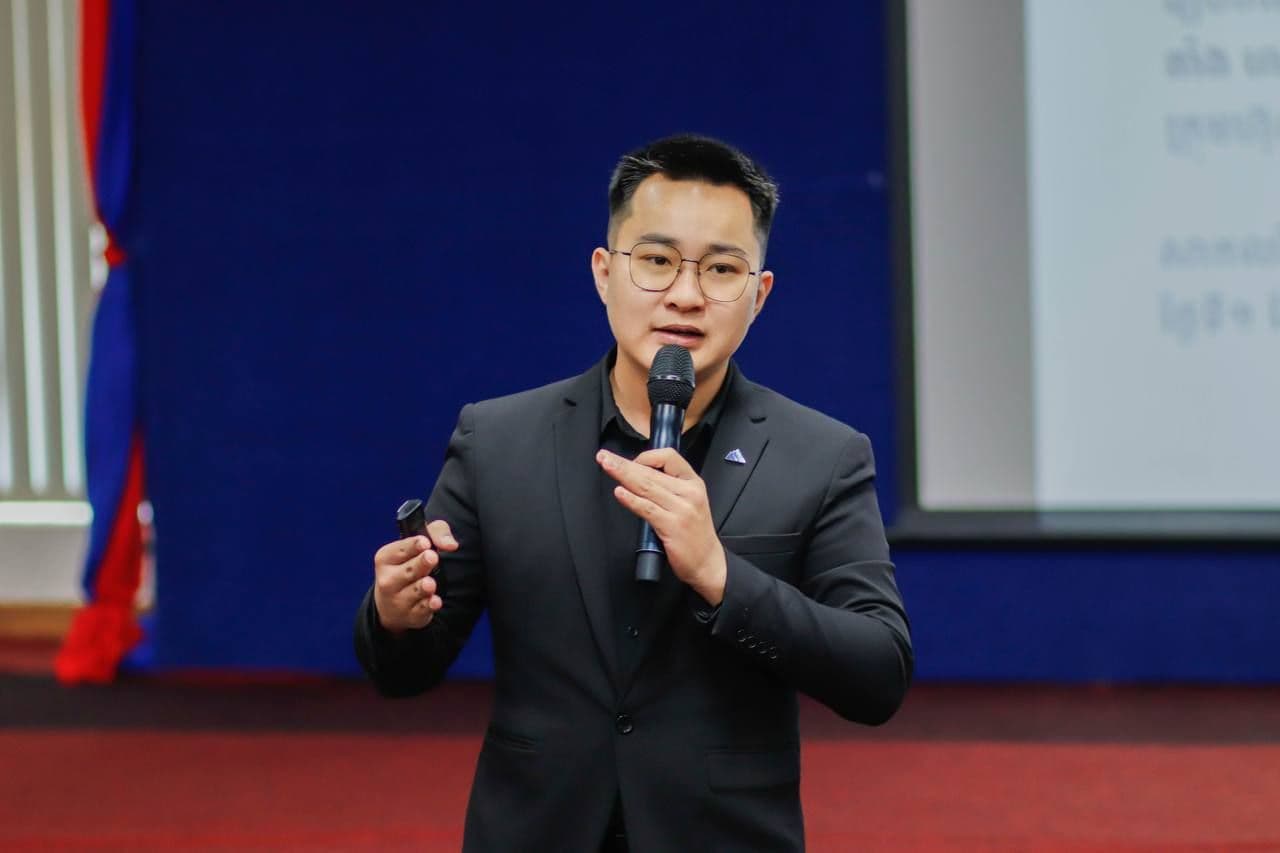
On the morning of 30th May 2026, Banjaran Asset Management (Cambodia) Plc., in collaboration with ACLEDA Securities Plc., Local Branch of ACLEDA Bank Plc. (Khan Boeng Keng Kang - Sangkat Boeng Keng Kang Ti Muoy) and ACLEDA Bank Plc. (AEON Mall Branch), successfully hosted the “Workshop on Golden Investment Opportunities” as part of the 3rd Round Roadshow, held at the meeting hall of the Boeng Keng Kang Ti Muoy Branch. We extend our sincere appreciation to all participants for their active engagement and insightful questions. Special thanks to our speaker, Mr. Sok Chantola, Deputy Sales & Marketing Manager, for delivering a clear, informative, and impactful presentation on the BAMC Asia Equity Fund (BAEF). We look forward to welcoming you to our upcoming events. Follow our News in Facebook
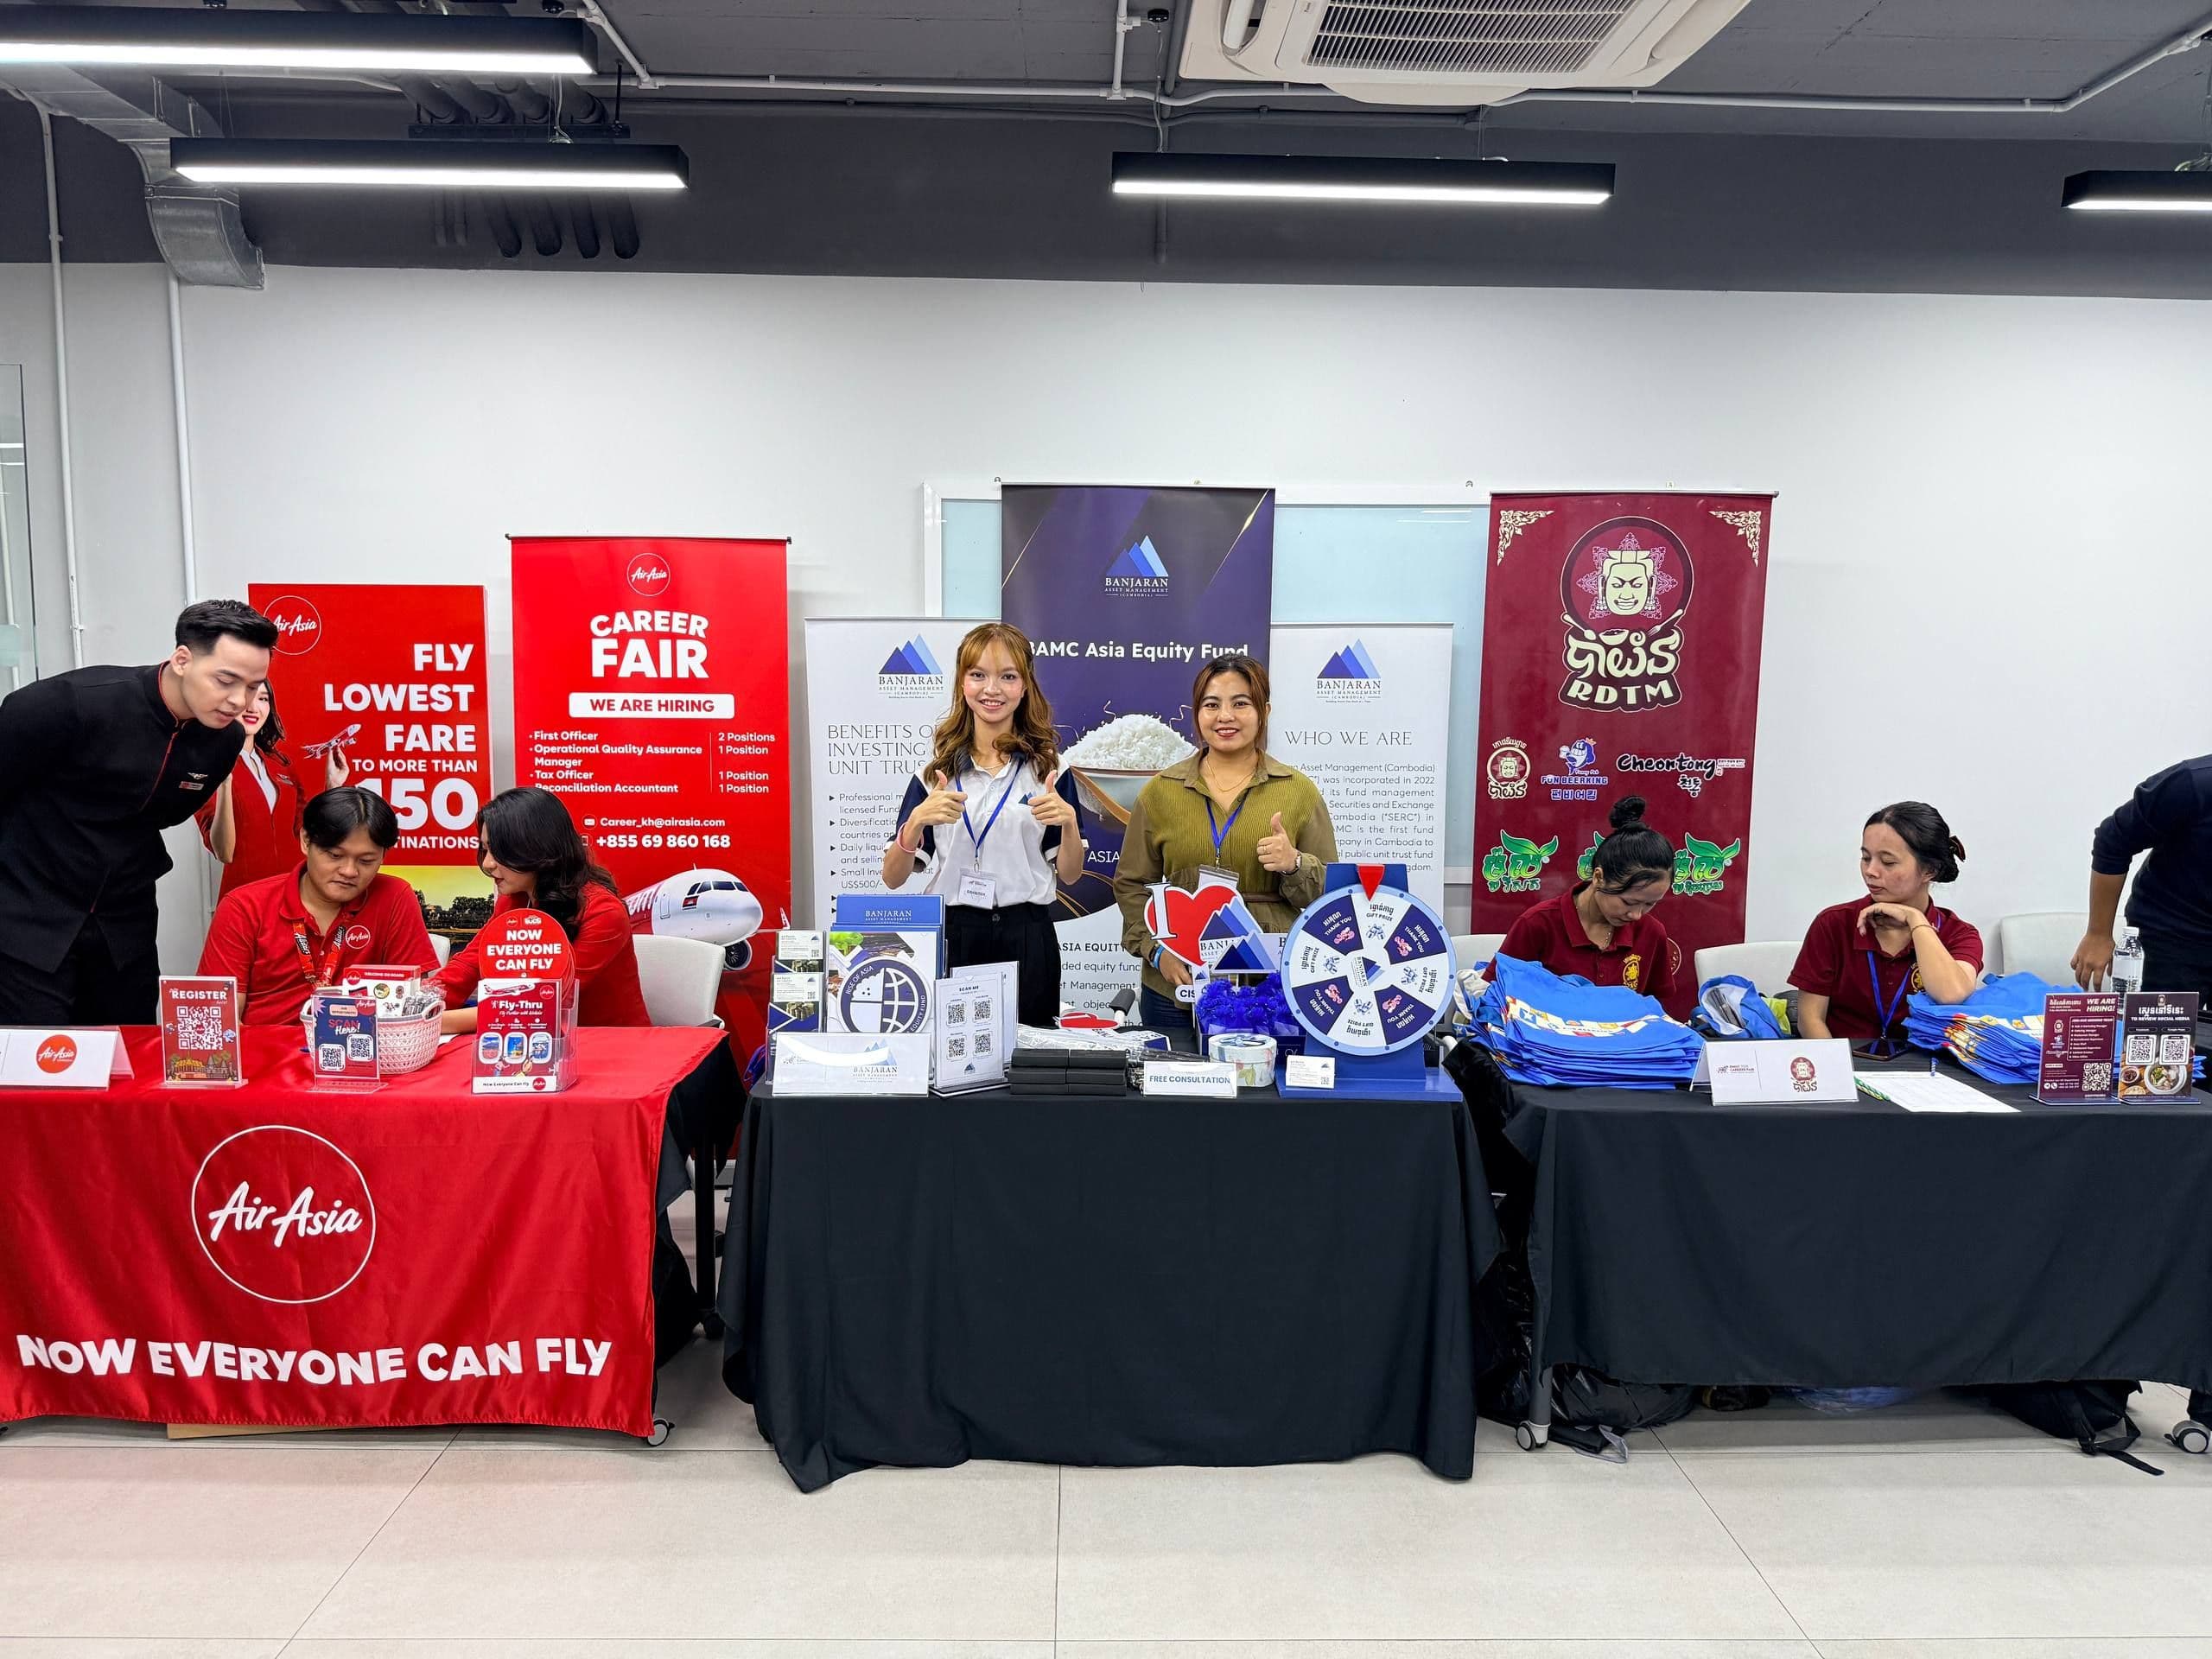
DMUC Careers Fair 2026
On 09th May 2026, Banjaran Asset Management (Cambodia) Plc. was honored to participate in the DMUC Careers Fair 2026 held at De Montfort University Cambodia (DMUC). We would like to thank DMUC for organizing this meaningful event and providing the opportunity to connect with students, fresh graduates, and young professionals. It was a great opportunity for our team to share career insights, engage with potential candidates, and introduce Banjaran AMC’s working environment and career opportunities. Thank you to everyone who visited our booth and interacted with our team. We truly appreciate your interest and support.
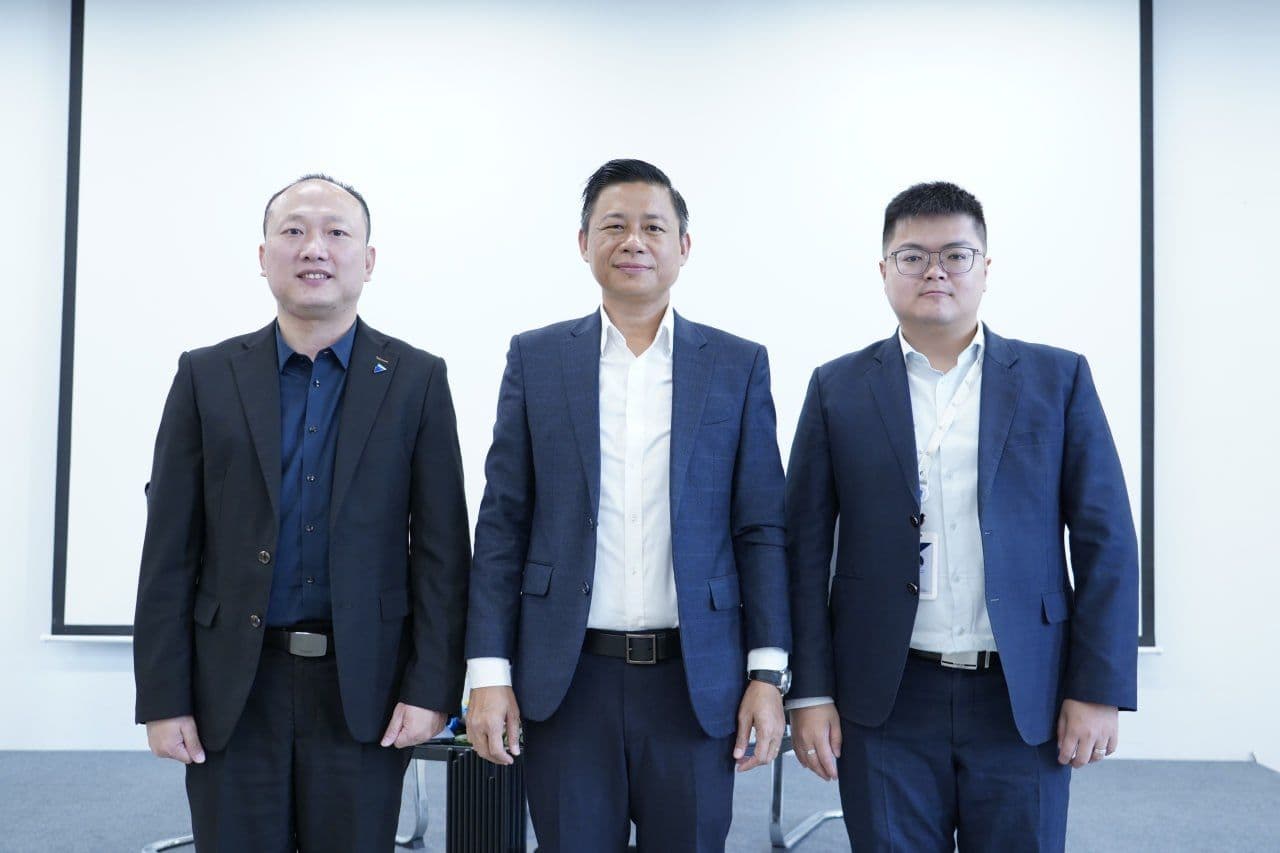
The Opportunities, Potential and Safety System of Investing in Fund Unit of CIS in Cambodia
On 07th May 2026, Mr. Eric Loo, Chief Executive Officer and Executive Director of Banjaran Asset Management (Cambodia) Plc., participated as a panelist in the panel discussion on “The Opportunities, Potential and Safety System of Investing in Fund Unit of CIS in Cambodia” during the Firms Doing CIS Business of the 31st Training and Examination and Continuing Professional Education in Securities Sector, at Business Development Center. The panel discussion highlighted the opportunities and potential of Collective Investment Schemes (CIS) in Cambodia, as well as the investor protection and safety framework supporting the development of Cambodia’s securities sector. For more references, please refer to SERC Page
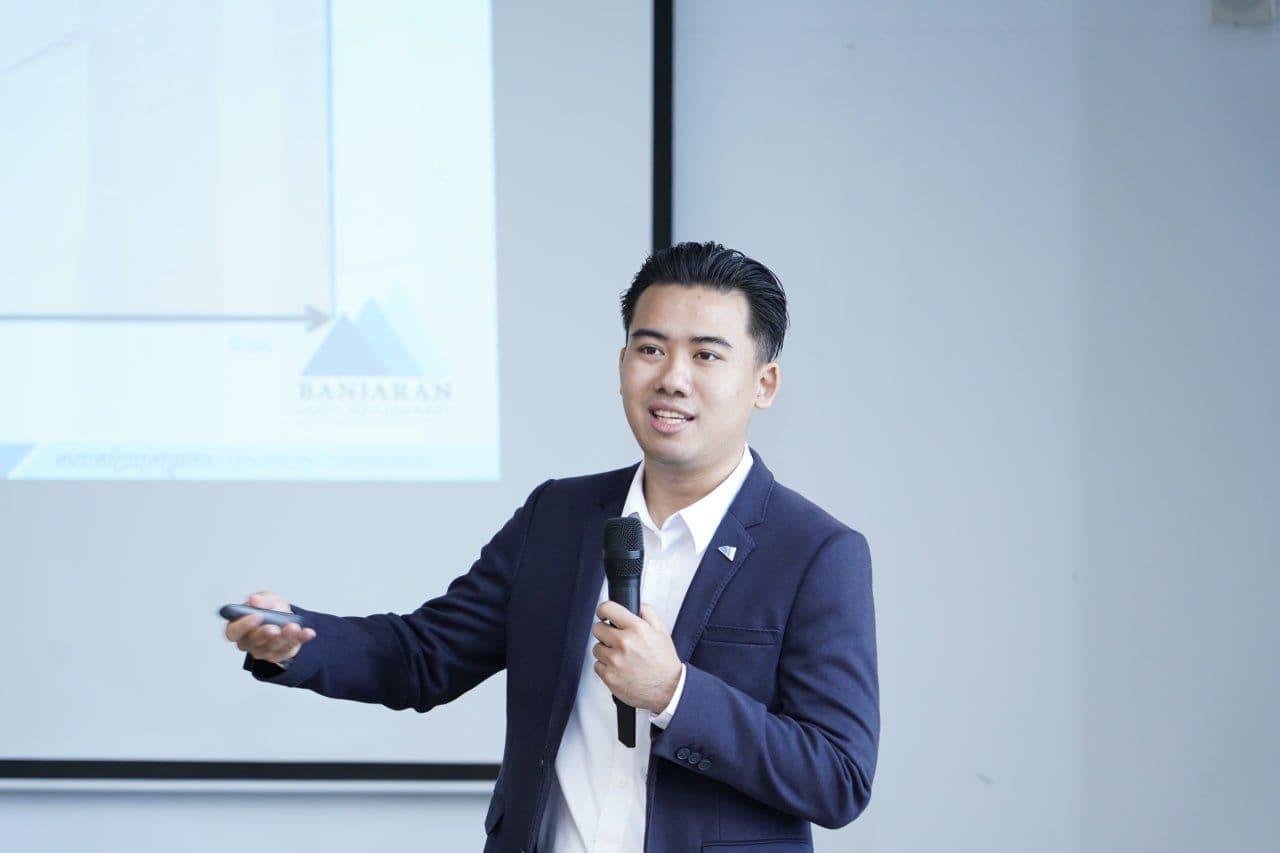
The 31st Training and Examination and Continuing Professional Education
On 07th May 2026, Mr. Veasna Monireach, Operation Officer of Banjaran Asset Management (Cambodia) Plc., delivered a presentation on “Asset Management and Funds” during the 31st Training and Examination and Continuing Professional Education in Securities Sector organized by the Securities and Exchange Regulator of Cambodia (SERC) at the Business Development Center. The presentation provided key insights on asset management and fund operations, focusing on the investment framework and key considerations for investors when evaluating investment opportunities in Cambodia’s securities sector.
The Offering of the First Collective Investment Scheme Fund Units in Cambodia
On 04th May 2026, Mr. Mok Chinly, Legal and Compliance Manager of Banjaran Asset Management (Cambodia) Plc., participated in sharing practical experience on “The Offering of the First Collective Investment Scheme Fund Units in Cambodia” during the 31st Training Course, Examination, and Continuing Professional Education Program in the Securities Sector organized by the Securities and Exchange Regulator of Cambodia (SERC) at the Business Development Center. The sharing session highlighted the establishment, registration, and offering process of BAMC Asia Equity Fund (BAEF), the first Collective Investment Scheme fund in Cambodia, as well as regulatory compliance, investor onboarding procedures, and operational experience in fund management within Cambodia’s securities sector.
The Cambodia REITs Opportunity
On the morning of 30 April 2026, Mr. Christopher Wong, Chief Investment Officer of Banjaran Asset Management Pte. Ltd. (Singapore), delivered a presentation on “The Cambodia REITs Opportunity” during the seminar on “The Offering of Real Estate Investment Trust of Collective Investment Schemes.” organized by the Securities and Exchange Regulator of Cambodia (SERC). The presentation highlighted the opportunities and regulatory framework relating to Real Estate Investment Trusts (REITs) in Cambodia, as well as the potential of Collective Investment Schemes in supporting the development of Cambodia’s capital market and enhancing accessibility to investment opportunities for general investors.
Potential of Sihanoukville Autonomous Port and Site Visit
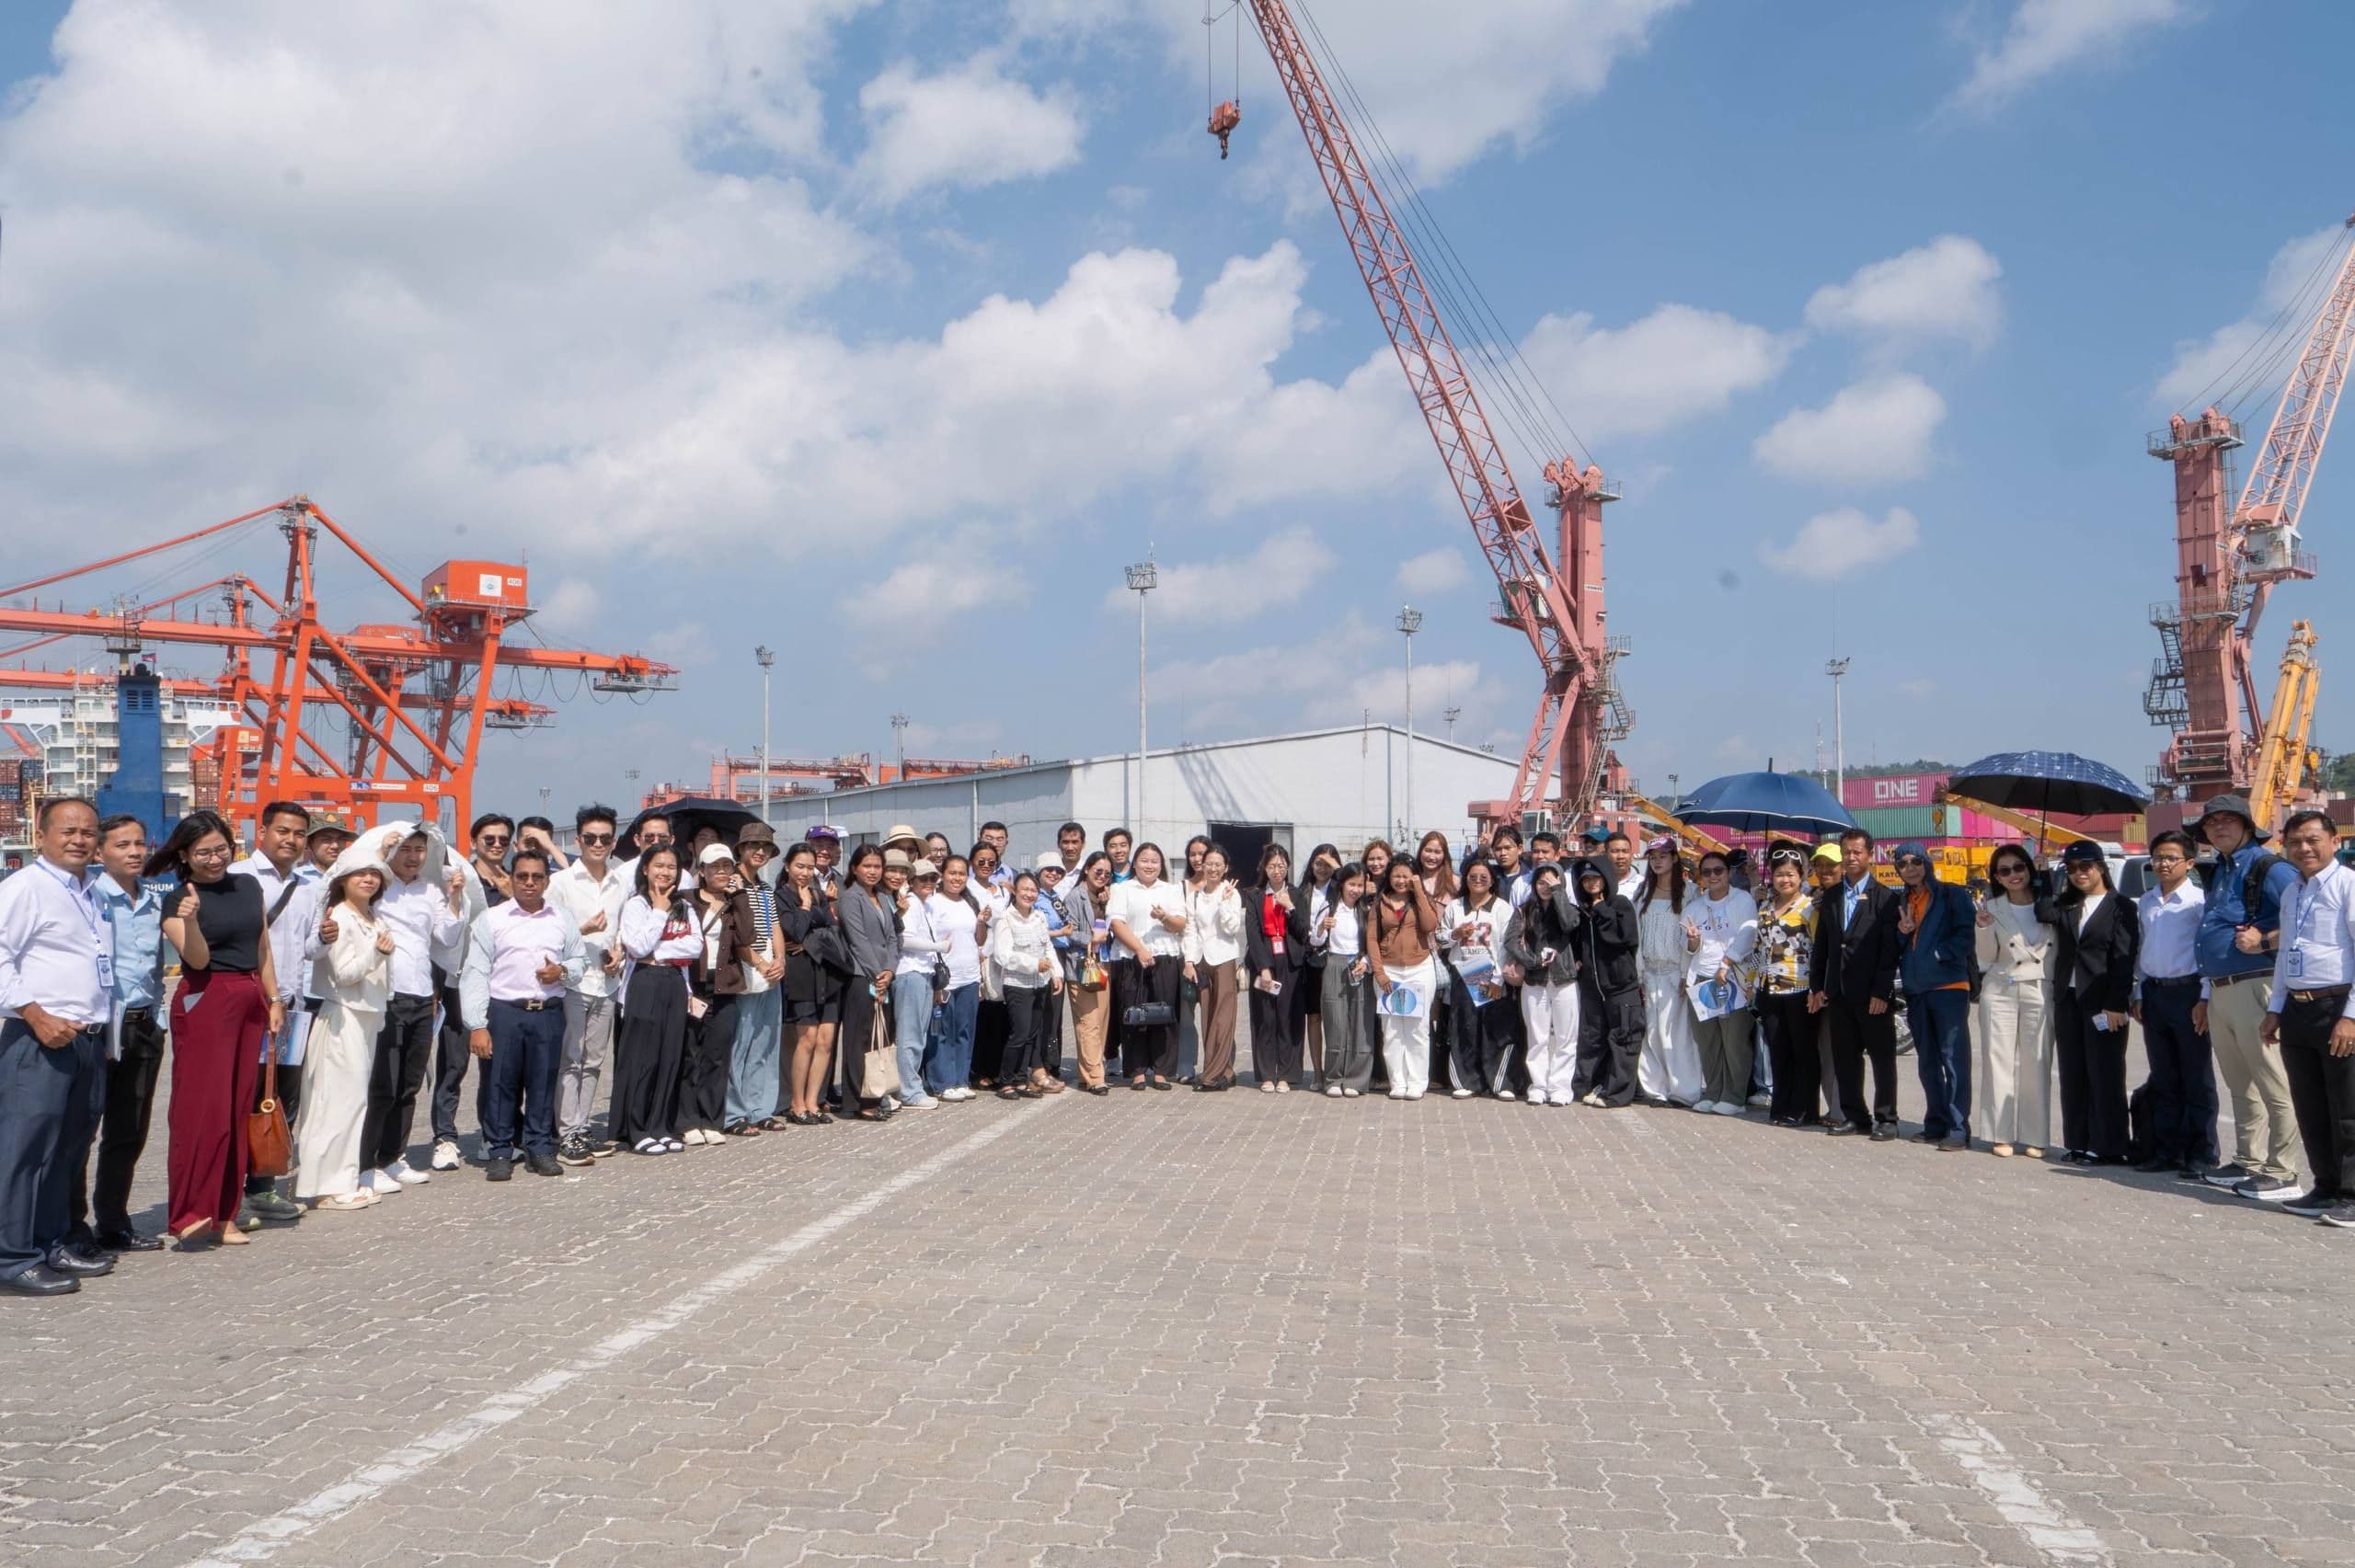
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the Listed Companies Forum on the topic: Potential of Sihanoukville Autonomous Port and Site Visit, organized by Cambodia Securities Exchange (CSX) on 06 April 2026. The forum, held at Sihanoukville Autonomous Port (PAS), was under the high presidency of H.E. Lou Kim Chhun, Delegate of the Royal Government of Cambodia in charge as Chairman & CEO of the Cambodia Securities Exchange (CSX), and H.E. Hong Sokhour, Delegate of the Royal Government in charge as CEO of the Cambodia Securities Exchange (CSX), highlighting the potential and business operations of the port. Our representatives, Mrs. Edeza Banquilis, Head of Growth & Strategy, and Mr. Sok Chantola, Deputy Sales & Marketing Manager, attended the event. The session and site visit provided valuable perspectives on Cambodia’s capital market growth and port development.
Ring the Bell for Gender Equality 2026
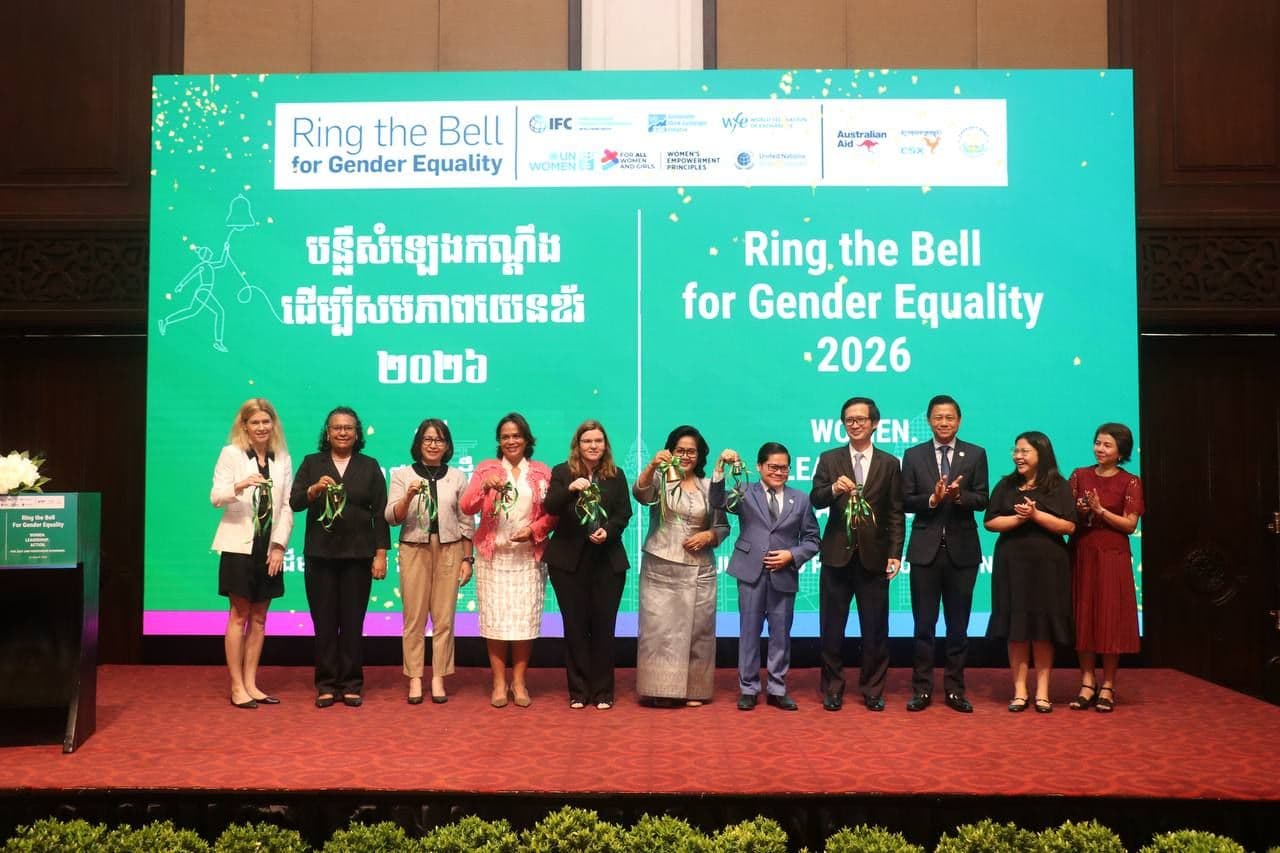
On 31 March 2026, Banjaran Asset Management (Cambodia) Plc. was honored to participate in the “Ring the Bell for Gender Equality 2026” event held at Sofitel Phnom Penh Phokeethra. The event featured the official Ring the Bell Ceremony, keynote sessions on women’s leadership in capital markets, and the launch of the Securities and Exchange Regulator of Cambodia (SERC). Scoping Survey on Gender-Responsive Finance and Sustainable Bonds. Our representative, Mrs. Nget Synat, Deputy Finance Manager, attended the session, gaining valuable insights and engaging in meaningful networking with industry professionals.
Training Program at ACLEDA University of Business
Banjaran Asset Management (Cambodia) Plc. was honored to participate in the recent “Smart Investing” training program held at ACLEDA University of Business on 1st April 2026. The event was organized by ACLEDA Securities Plc. in collaboration with the ACLEDA University of Business and was presided over by H.E. Sou Socheat, Delegate of the Royal Government in charge as Director General of the Securities and Exchange Regulator of Cambodia (SERC). During the session, Mr. Eric Loo, CEO and Executive Director, along with the team was present in supporting the financial literacy initiatives for the next generation. A key highlight featured by Mr. Taing Hoy, Legal and Compliance Officer, who delivered a comprehensive presentation on “Investment in Collective Investment Scheme (CIS)”, providing students with essential insights into financial planning and capital market opportunities.
市场展望
2026 April Market Outlook: From Conflict Shock to Market Strength — What’s Driving the Recovery
Major indices across the countries tumbled in March but abruptly spiked in April upon the announcement of US-Iran peace talks, though the US Navy continues its blockade of the Strait of Hormuz. Record highs in the tech-heavy S&P 500 and strong US corporate earnings reaffirm the market’s resilience throughout the conflict, particularly for demand in technology. Similarly, Asian markets tracked US gains and rallied in April; South Korea’s Kospi and Japan’s Nikkei were also driven by technology related optimism and de-escalation relief. Singapore’s central bank tightened monetary policy while the Bank of Japan cooled rate hike expectations. The situation in China remains mixed with continued weak domestic demand and an ongoing property sector drag, while local banks have outpaced broader market since the war broke out. As markets rebounded and risk sentiment improved in April, we remain highly selective in stock selection while diversifying across markets, maintaining our disciplined, bottom-up approach to portfolio construction.
2026 March Market Outlook: Markets Under Pressure as Geopolitical Tensions Rise
The US-Israel war with Iran has created a delicate balancing act between investing for resilient growth and managing geopolitical volatility. While a "soft landing" remains the baseline for many advanced economies, the landscape has grown more complex following the late-February shocks. On interest rate watch, the US Fed is expected to maintain a "higher-for-longer" stance to counter inflationary pressures from rising energy cost, and to a lesser extent the new 15% global tariffs. Markets are pricing in a sustained "war premium" in energy. With Brent crude hovering near $100, any further escalation in the Middle East could reignite global supply-side inflation, which may lead to extended high-interest-rate environment and hence leading to a sharp global economic slowdown. In China, it has largely stayed away from the Middle East war though it has urged US and Israel to de-escalate and stop its aggression against its ally, Iran. China is amongst the most affected countries by the closure of the Strait of Hormuz, though Iran has allowed some Chinese-flagged oil tankers to transit through. Meanwhile, all eyes are on the implementation of the 15th Five-Year Plan. Success hinges on whether Beijing’s "New Quality Productive Forces" can offset the structural drag of its property sector. After the February technology sector correction and in this current environment of heightened volatility, we remain highly selective in the technology sector while diversifying across markets, maintaining our disciplined, bottom-up approach to portfolio construction.
2026 February Market Outlook: From U.S. Policy Turmoil to Mixed Signals Across Asia
The geopolitical scene in the US has been uncertain and volatile. The January jobs report exceeded expectations, though employment gains were largely concentrated in the healthcare sector. Kevin Warsh, known for his hawkish stance, has been nominated as the next Federal Reserve Chair, though this remains to be confirmed by the Senate. In the past week, the Supreme Court has ruled against President Trump’s International Emergency Economic Powers Act (“IEEPA”) tariffs. In return, the Trump administration acted quickly to impose 10% global tariffs, and immediately raised to 15% that will remain effective for 150 days under a separate trade law. These developments have contributed to a weakening US dollar, which is further exacerbated by rising US-Iran military tensions. Gold extended its rally and reached new highs, while silver surrendered most of its gains. Investors remain cautious amid sharp swings in these traditional safe haven assets. In Asia, market performance has been mixed. Indonesia experienced its largest stock crash since 1998, whereas South Korea and Taiwan delivered strong returns. Markets have shown heightened sensitivity to the external macro environment, resulting in intermittent pullbacks. Most recently, Chinese stocks rose as IEEPA tariffs were removed as China is set to face lower duties on shipments to the US. The Shanghai Composite and Hang Seng indexes also experienced recent declines, as is expected due to thin trading volumes during the Lunar New Year holiday season. Overall sentiment towards Asian equity markets amid the uncertain global political climate remains positive. Against this backdrop, we continue to diversify across different markets and sectors while remaining selective to stock selection, particularly within the technology sector. We continue to maintain a disciplined, bottom-up approach in portfolio construction.
2026 January Market Outlook: A Month That Redirected Market Attention
The New Year began with subdued volatility, but the calm was subsequently shattered by geopolitical events, notably US’s desire to take over Greenland for its strategic Arctic Circle argument. Demand for gold and silver skyrocketed with prices hitting new fresh highs. However, these high precious metal prices can create a range of challenges for precious metal-dependent industries like solar panel makers and EV producers which use silver as part of their components in their production. This may further impact the profitability of the solar panel makers which are already facing an oversupply situation. Asian markets started the year mixed but with some positive moves. Several key themes are driving the markets, central amongst them is a strong Asian IPO pipeline especially in Hong Kong and India. Other country-specific themes that are driving the markets include the deployment of funds from the Equity Market Development Programme in Singapore. The Korean Kospi has exceeded their President’s target, with technology companies fueling the rally on accelerated semiconductor demand. China surprised with an export outperformance with a record 2025 trade surplus, plus resurgent interests in AI-related tech names. While in Japan, performance is mixed where there are concerns with the volatility and soaring yields in the Japanese Government Bonds market. In 2025, US technology stocks dominated investor attention for much of the year, later turning to precious metals commodities. This period also underscored the importance of diversification and currency exposure beyond the US. With growth now amplifying across global markets, moderate softening of the US dollar may act as a drag on returns from US assets. Against this backdrop, we retain our emphasis on broadening exposure to other markets and sectors while being mindful of our stock selection, particularly in the technology sector. We continue to maintain a disciplined, bottom-up fundamental approach in portfolio construction.
2025 December Market Outlook: Protecting Value as Risks Reprice.
The hawkish rate cut signaled the Fed’s caution, even as tariff-related inflation pressures appeared to be fading. November’s jobs report suggested a subdued consumer environment. Unemployment had risen to its highest level since 2021, and retail sales remained unchanged despite Black Friday sales. Though the Trump administration has softened its language on China, recent developments highlight the delicate truce in their trade war. The U.S. has restricted China’s access to technology, such as permitting limited Nvidia chip exports, and formed an international partnership to counter China’s rare earth dominance. Across Asia, the picture remains mixed. The weaker U.S. dollar alleviates pressure on currency weakness in countries like Indonesia, South Korea, India, and the Philippines. The Bank of Japan have responded to the Fed’s rate cut by raising interest rates by a quarter point in a widely expected decision. In China, the economy continues to be supported by sustained capital inflows and the boom in exports while pivoting away from dependence on U.S. consumers. This was in spite of the property sector slump, missed industrial production expectations, weak retail sales, and unchanging unemployment rates. Measures to drive consumption appear ineffective, and rising trade frictions with countries beyond the U.S are weighing on sentiment. Investors are increasingly watchful for signs of an AI-driven bubble, including circular financing risks inflating valuations, where such dynamics could unwind abruptly. Against this backdrop, investors face a strategic dilemma - rein in AI exposure ahead of a potential bubble popping, or double down to capitalize on game-changing technology breakthroughs. In response, we are positioning portfolios defensively and broadening exposure to other sectors. This includes increasing allocations to commodities such as silver and gold, which can serve as stores of value, and consumer staples, that tends to offer more resilient demand. We continue to maintain a disciplined, bottom-up fundamental approach in portfolio construction.
2025 November Market Outlook: AI Bubble Alert
Mega-cap chip making company Nvidia Corp (“Nvidia”) became the first company to hit $5 trillion market capitalisation, likely due to U.S. President Trump’s comments ahead of the trade talk with Chinese President Xi Jinping at the end of October. The talk resulted in a consensus on cooperation in expanding agricultural trade and pausing the rare-earths licensing regime for a year. Mid-November saw the conclusion of the record U.S. government shutdown, which lasted 43 days, and put an end to unpaid furlough and other government operations. Consequently, the October jobs report was cancelled due to insufficient data. The ambiguity around unemployment rates raised uncertainty about the state of the U.S. economy. Compounding concerns were exacerbated by growing anxieties about stretched valuations of an “AI bubble”, which led to a selloff towards the end of November. Similarly, the Asian equity market, primarily due to technology companies in the AI landscape, slumped after an initial rally in the previous month’s end. In the semiconductor space, South Korean company Samsung Electronics Co., Ltd. reported an 80% surge in profit and SK Hynix Inc. continued to lead in chip memory. In China, different industries continue to diverge as technology companies grow while consumption and property remain a drag. In response, China’s policymakers are evaluating various measures to support the housing market. The MSCI Emerging Markets Index fell sharply, and losses were led by the tech heavy Korean Kospi index where the aforementioned Korean companies posted steep declines. Looking ahead, we remain cautious of the volatility in the markets. Due to concerns about inflated valuations for technology companies, the pullback observed in late November may have been a profit taking move or a price correction. Investors remain watchful for indicators of the widely discussed AI bubble, and signals for a potential burst. Against this landscape, we maintain a disciplined and balanced approach, grounded in bottom-up fundamental analysis in our portfolio construction.